
Chile · Argentina · Lithium · Critical Minerals · Water · Regulation
Lithium in Argentina and Chile: Where Europe's Raw Material Interest Meets Local Reality
Argentina and Chile remain central to global lithium supply, but the 2026 story is increasingly about execution. Argentina is ramping operating plants, financing large expansions and consolidating new development platforms; Chile is translating its state-led strategy into joint ventures, CEOLs and new project structures. Water and local legitimacy remain supply variables in both systems.
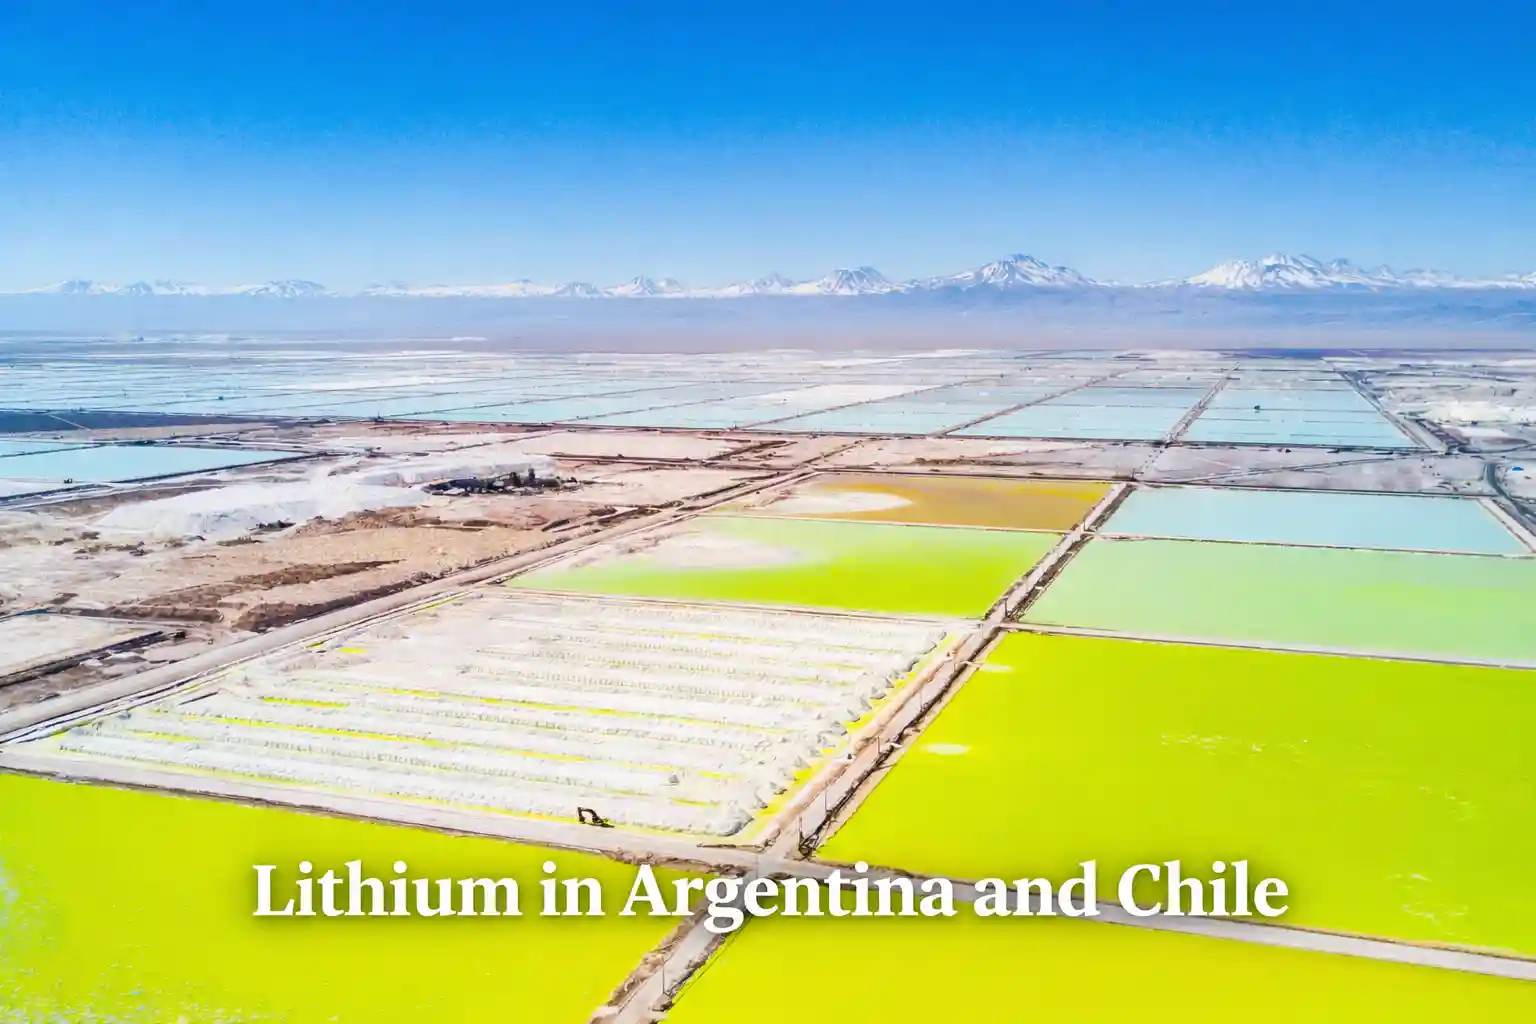
Lithium in Argentina and Chile matters for Europe, but 2026 makes the distinction between resource, approval, construction and stable production much sharper.
Argentina is moving several projects deeper into execution: Eramet’s Centenario plant reached about 90% of nameplate capacity in June; Cauchari-Olaroz produced 9,280 tonnes of lithium carbonate in Q2 and operated near design capacity; Rio Tinto secured US$1.175 billion in external financing for Rincon; and Minera Exar received RIGI approval to add 45,000 tonnes per year of LCE capacity at Cauchari-Olaroz.
Chile is moving differently. NovaAndino Litio is already established around the Salar de Atacama, Codelco obtained the amended CEOL for Maricunga, and the ENAMI–Rio Tinto Salares Altoandinos transaction received Chilean competition approval in July. Rio Tinto continues to expect the Maricunga and Altoandinos joint-venture closings in late 2026 or early 2027.
For the wider sector structure, see Econosur’s South America lithium and mining overview, the Chile market profile, the Argentina market profile and the analysis of why lithium is not one market.
Core market reading:
The Lithium Triangle is an attractive European supply-chain story. But on the ground, lithium supply depends on project-level execution: water governance, hydrological data, provincial capacity, indigenous consultation, regulatory continuity and the difference between a resource estimate and a mine that actually delivers.
September 2026: The Market Is Moving From Announcements to Execution
The project hierarchy is becoming easier to read. Argentina has seven lithium mines in production according to the national government’s 2025 export summary, while individual operators are publishing stronger evidence on operating performance, ramp-up, financing and expansion. By September, the market is also showing a second trend: consolidation of adjacent development assets into larger operator-led platforms.
At Centenario-Ratones in Salta, Eramet reported that production reached around 90% of nameplate capacity in June 2026. This is material because Centenario is one of the first large industrial DLE plants in the region. The result does not prove that DLE works identically across all salars, but it moves the technology discussion from pilot-scale promise toward operating evidence.
Rio Tinto’s Rincon project has also moved deeper into execution. In March, the company secured a US$1.175 billion financing package from IFC, IDB Invest, Export Finance Australia and JBIC for the US$2.5 billion project. Rio Tinto targets roughly 60,000 tonnes per year of battery-grade lithium carbonate, with first production expected in 2028 and a three-year ramp-up to full capacity.
In Jujuy, Argentina approved Minera Exar’s Cauchari-Olaroz expansion under RIGI on June 4. The approved plan adds 45,000 tonnes per year of LCE capacity. Lithium Argentina reported 9,280 tonnes of lithium carbonate production at Cauchari-Olaroz in the second quarter, with the existing operation performing near design capacity. For Stage 2, the company and Ganfeng are also engineering an initial 10,000 tpa modular DLE facility as part of a phased expansion. Argentina’s growth path is therefore not becoming a single-technology model: existing evaporation-based production, conventional infrastructure expansion and modular DLE can develop in parallel.
Argentina’s lithium question is changing from “How many projects exist?” to “Which operating systems can actually scale?”
In 2026, the useful evidence is no longer the project count. It is operating output, ramp-up performance, financing, approved expansion scope, infrastructure readiness and whether an operator can reproduce stable output after commissioning. That is a much narrower and commercially more useful market than the headline project pipeline.
A second September signal comes from the Ganfeng–Lithium Argentina partnership. On 24 August, the companies signed definitive agreements to consolidate Pozuelos-Pastos Grandes, Pastos Grandes and Sal de la Puna into a new PPG joint venture targeting 150,000 tonnes per year of LCE across three phases. Ganfeng is to hold 67% and act as operator, while Lithium Argentina holds 33%. On 15 September, Lithium Argentina confirmed the closing of a separate US$180 million strategic investment from Ganfeng. At that date, completion of the PPG joint venture itself was still expected by the end of September. The distinction matters: the financing closed; the project consolidation was still a pending transaction milestone.
Chile shows the opposite transition. Its national strategy is becoming structurally clearer, but several new assets remain one or more stages earlier than Argentina’s operating expansions. NovaAndino Litio, the Codelco–SQM company for the Salar de Atacama, was formally established at the end of 2025. In February 2026, Codelco obtained the amended CEOL for Maricunga, including a governance mechanism and contributions linked to nearby Indigenous communities.
For Salares Altoandinos, Chile’s competition authority approved the ENAMI–Rio Tinto joint venture on July 17. Even so, Rio Tinto’s latest half-year reporting moved the expected closing of both the Maricunga and Altoandinos transactions to late 2026 or early 2027, subject to remaining regulatory approvals and conditions.
Chile has reduced policy ambiguity faster than it has reduced project-stage risk.
The state-participation architecture is now visible: NovaAndino in Atacama, Codelco–Rio Tinto in Maricunga and ENAMI–Rio Tinto in Altoandinos. But these projects sit at different points on the execution curve. For suppliers and buyers, “Chile lithium” is therefore becoming a portfolio of distinct procurement clocks rather than one national opportunity.
The European framing of lithium in the Southern Cone tends to be strategic and linear: secure access, diversify supply chains, reduce dependency, protect industrial futures. From Brussels or Berlin, this reads as a commodity question with a relatively clear direction of travel.
That framing is not wrong, but it is incomplete. In the salt flats of northern Argentina and Chile's Atacama, the variables that determine whether a project actually delivers at volume extend well beyond geology and reserve estimates. Near the top of that list is water.
The United States Geological Survey estimates that Argentina and Chile held 13.6 million tonnes of reported lithium reserves at the start of 2026, about 37 percent of the global total of 37 million tonnes. Their identified resources amounted to 41 million tonnes, or roughly 27 percent of the global total of 150 million tonnes.
Production is substantial but much smaller than the resource headline. The USGS estimated 2025 mine production at 23,000 tonnes of lithium content in Argentina and 56,000 tonnes in Chile. Together, the two countries represented about 27 percent of reported world production excluding the withheld United States figure.
Argentina’s high-altitude project map spans Jujuy, Salta and Catamarca, but the number of announced or developing projects is much larger than the group producing at commercial scale. Chile already has a larger operating base centred on the Salar de Atacama. This difference between resources, planned capacity and functioning production is central to the market analysis.
Two Models That Europe Conflates
Chile and Argentina are regularly discussed under the same heading in European supply chain analysis. The convenience of the "Lithium Triangle" framing, which adds Bolivia as a third vertex, produces a geographic shorthand that obscures a fundamental difference in how the two countries are managing their lithium sectors.
Chile has moved toward a state-framed model. By September 2026 this is no longer only a strategy document: NovaAndino Litio is established in the Salar de Atacama, Maricunga has an amended CEOL, and the Salares Altoandinos partnership has received Chilean competition approval. The model combines state participation with private mining and technology partners, community-governance mechanisms and project-specific execution stages.
Argentina operates differently. Lithium governance is project-driven and provincially distributed, while national instruments such as RIGI increasingly influence project economics and investment timing. Rincon and the Cauchari-Olaroz expansion show how a federal incentive layer now sits on top of provincial permitting, water governance and community processes. Regulatory consistency and execution capacity still vary by province and project.
For external investors or offtake buyers, reading Argentina as a unified lithium market is a category error. The operative unit is the project and its provincial context, not the country.
Companies and Projects Shaping the Market
The lithium market in Argentina and Chile is organised through companies, project vehicles and public institutions rather than through national resource figures alone. The relevant questions are who operates, who controls the asset, which project is already producing and which capacity still depends on commissioning or future permits.
China is also embedded in ownership, financing, technology and offtake relationships. Econosur examines that wider layer in Chile’s copper and lithium connection with China.
From Project Pipeline to Actual Production
Reserve size, project announcements and nameplate capacity describe different stages of the market. In 2025, the USGS estimated combined mine production in Argentina and Chile at 79,000 tonnes of lithium content. Current company operating data add another layer: Cauchari-Olaroz produced 9,280 tonnes of lithium carbonate in Q2 2026 and was operating near design capacity. These figures use different units, but together they reinforce the same point: future projects and expansion claims have to be separated from measured output.
Eramet’s Centenario-Ratones plant shows the distinction clearly. The plant is designed for 24,000 tonnes of lithium carbonate per year at full capacity. It produced 6.7 thousand tonnes in 2025, then continued its ramp-up through 2026 and reached around 90% of nameplate capacity in June. Eramet still guides toward 17–20 thousand tonnes of 2026 production and close to full nameplate capacity by year-end. The project therefore provides operating evidence without erasing the distinction between annual production and design capacity.
The units must also be separated. USGS mine-production figures are reported as lithium content, while companies frequently communicate capacity in lithium carbonate equivalent. Comparing them without conversion creates false market impressions.
Project-status rule:
A resource estimate proves geological presence. A permit allows a project to advance. Nameplate capacity describes design ambition. Stable production requires commissioning, process reliability, water management, infrastructure, trained operators, suppliers and a functioning route to market.
Rio Tinto adds another useful project-status comparison. The company reported first production at the Fénix 1B expansion and Sal de Vida in the first half of 2026, while construction of the full-scale Rincon plant continues. These assets sit inside the same corporate lithium portfolio but at different operating stages. Treating them as one block of “future capacity” would hide the real execution sequence.
"Access to lithium is not decided underground. It is decided at the surface — in water allocation, regional governance, and the capacity to treat local legitimacy as a production requirement rather than a public relations exercise."
Water: The Constraint That Isn't in the Prospectus
Brine mining, the dominant extraction method across the Andean salars, does not use freshwater in the conventional sense. It pumps lithium-rich brine from subsurface aquifer systems, concentrates it through evaporation, and processes the resulting mineral slurry. The water question, however, is not about freshwater consumption in isolation. It is about the hydrological integrity of some of the most complex and least-understood aquifer systems on the continent.
The Atacama and the Argentine Puna are among the most arid environments on earth. Their wetlands, flamingo populations, and indigenous agricultural systems depend on precise hydrological balances that connect subsurface brine with surface freshwater in ways that are still being mapped.
Research and civil-society analysis have raised recurring questions about the relationship between brine pumping, adjacent freshwater systems, cumulative extraction across a salar basin and the quality of baseline hydrological data. These questions cannot be reduced to one generic litres-per-tonne figure because brine pumped, freshwater withdrawn, recycled process water and ecosystem impact are different measurements.
A valid permit, financing package or offtake agreement does not remove hydrological risk. Projects can still face delays, legal challenges, community opposition or additional regulatory review when impact data or cumulative basin effects are disputed. DLE also does not make the water question disappear: extraction yield, brine reinjection, freshwater use and basin-scale hydrology are separate variables. The distance between a bankable feasibility study and consistent production is therefore partly a water-governance question.
Water is not an environmental side issue. It is a supply-chain risk variable.
For European buyers, the risk is not only reputational. It is operational: a project can look attractive in reserve terms and still face delays, injunctions, community opposition or regulatory suspension if hydrological credibility is weak.
The Participation Gap — and Why It Is an Investor Risk
Argentina’s federal structure gives provincial governments a central role in mining permits and project administration. Indigenous consultation obligations add another layer where projects affect communities and territories covered by ILO Convention 169.
The quality of information, consultation, environmental review and long-term dialogue is not uniform across provinces or projects. When those processes are contested, legal and political exposure can emerge after investment decisions have already been made.
For buyers and investors, participation is therefore part of operational diligence. The relevant questions are whether communities received usable information, whether hydrological assumptions were disclosed, whether consultation can be demonstrated and whether the project has a durable process for handling future disputes.
The EU Critical Raw Materials Act frames lithium as a strategic priority with explicit supply diversification targets.
What the CRMA does not resolve, and cannot resolve through European legislation alone, is the question of whether the projects supplying that lithium are institutionally durable. A project that meets European due diligence requirements at the point of offtake signing but faces operational suspension two years later due to a water injunction or a community legal challenge does not deliver supply security. It delivers a different kind of risk, with longer lag time before it becomes visible.
The lithium story should be read alongside Econosur’s broader argument that lithium is not one market. Chile, Argentina and Bolivia follow different governance models, investment rules and execution paths for the same strategic resource.
For country-level context, see Chile market profile and Argentina market profile.
What Chile's Regulatory Trajectory Demonstrates
Chile’s National Lithium Strategy has moved from a policy announcement into a set of public-private structures with different maturity levels. The most advanced institutional case is NovaAndino Litio, formally established by Codelco and SQM around the existing Salar de Atacama production base.
This structure changes governance, control and the distribution of future value. It should not be read as a completely new greenfield mine. The underlying lesson is that company structure and project status have to be separated from production headlines.
Chile is extending that model beyond Atacama through planned partnerships with Rio Tinto. Maricunga now has the amended CEOL required to advance, while Salares Altoandinos received Chilean competition approval in July. The remaining transaction closings are now expected in late 2026 or early 2027. Argentina remains more decentralised: operators work through provincial systems while RIGI adds a national investment layer. At the same time, the PPG agreements show that decentralised provincial development can still produce larger operator-led platforms when adjacent assets, financing and ownership structures are consolidated.
The 2025 production figures show the difference in operating maturity. Chile produced an estimated 56,000 tonnes of lithium content, compared with 23,000 tonnes in Argentina. This does not prove that one regulatory model is universally better. It shows that Chile enters the next phase with a larger established production base, while Argentina’s growth case depends more heavily on successful ramp-ups.
The Signal for European Capital
For European companies, investors and institutions operating under the CRMA, the Andean lithium corridor presents a genuine opportunity and a misread risk profile. Europe is moving beyond diversification targets toward project financing, strategic-project support and stronger offtake logic. That makes project quality in Argentina and Chile more important, not less. The misread is still assuming that reserve size and permitting status are the primary variables determining supply reliability.
The operational variables that determine whether a project delivers on schedule and at projected volume are institutional: the quality of water governance in the project's provincial context, the substantive integrity of indigenous consultation processes, the provincial government's capacity to enforce and adjudicate environmental compliance, and the hydrological data underpinning the project's impact assessment.
These are not due diligence checkboxes. They are the factors that distinguish projects that will produce lithium at scale from projects that will generate legal proceedings, community opposition, and reputational exposure for their European offtake partners.
The Andean salt flats are not a simple procurement frontier. They are a test of whether European raw material strategy can engage seriously with the conditions under which critical minerals actually become available, not just on paper, but at volume, over time.
That test is not primarily geological. It is institutional, hydrological, and political. The projects that will deliver are those where these dimensions have been worked through, not assumed away.
Europe’s useful unit of analysis is not the Lithium Triangle. It is the financeable, operable project.
By 2026, Argentina and Chile offer enough project evidence to distinguish geology from execution. A European buyer should ask which plant is producing, which expansion is financed, which permit is final, which joint venture is still waiting to close, which water model is proven and where procurement authority actually sits. That is the level at which supply security becomes measurable.
European supply-chain strategy needs project-level reality checks.
For lithium in Argentina and Chile, the relevant evaluation is not only country reserves. It is whether each project has credible water data, durable community processes, enforceable environmental governance, stable institutional support and a realistic route from permit to production.
This analysis separates resources, reserves, approvals, financing, design capacity, construction, ramp-up and actual production. Those categories are not interchangeable.
- U.S. Geological Survey — Mineral Commodity Summaries 2026: Lithium — 2025 mine production, reported reserves and identified resources.
- Argentina Ministry of Economy — Resolution 825/2026 — formal RIGI approval for Cauchari-Olaroz expansion by 45,000 tonnes per year of LCE.
- Argentina Ministry of Economy — Resolution 735/2025 — Rincon RIGI approval and 53,000–60,000 tonnes per year capacity framework.
- Rio Tinto — Rincon financing, March 11, 2026 — US$1.175 billion financing package, US$2.5 billion project, first production expected in 2028.
- Rio Tinto — H1 2026 project update — first production at Fénix 1B and Sal de Vida and continued Rincon construction.
- Eramet — H1 2026 results — Centenario reached about 90% of nameplate capacity in June.
- Lithium Argentina — Q2 2026 results, 11 August 2026 — 9,280 tonnes of Q2 lithium carbonate production at Cauchari-Olaroz, operation near design capacity, and Stage 2 modular DLE development.
- Lithium Argentina — PPG joint-venture agreements, 24 August 2026 — definitive agreements for a 67/33 Ganfeng–Lithium Argentina structure targeting 150,000 tpa LCE across three phases.
- Lithium Argentina — Ganfeng strategic investment, 15 September 2026 — closing of the US$180 million investment; PPG JV completion remained expected by end-September.
- Codelco — NovaAndino Litio established — formal Codelco–SQM company structure for Salar de Atacama.
- Codelco — amended Maricunga CEOL, February 12, 2026 — project area, timelines, community contributions and governance mechanism.
- Chile Fiscalía Nacional Económica — ENAMI–Rio Tinto approval, July 17, 2026 — competition clearance for Salares Altoandinos JV.
- Rio Tinto — June 30, 2026 filing — expected Maricunga and Altoandinos transaction closings moved to late 2026 / early 2027.
- European Commission — CRMA Strategic Projects — strategic-project framework for diversified critical-mineral supply.
- International Labour Organization — Convention 169 — consultation framework for Indigenous and tribal peoples.
- Argentina Government — 2025 mining export record — seven lithium mines in production and US$905 million in lithium exports in 2025.
- Eramet — Centenario project overview — 24,000 t/y design capacity and DLE operating context.
- Rio Tinto — key project updates — Argentina and Chile lithium portfolio context.
From reserves to supply-chain reliability
Lithium in Argentina and Chile is not only a raw-material opportunity. It is a project-execution question shaped by water, regulation, institutional capacity, community legitimacy and European due diligence pressure.
Econosur prepares custom market analysis for companies, analysts and institutions evaluating critical minerals, lithium projects, South American supply chains, energy-transition exposure and country-specific operating risks.
Explore custom market analysisFAQ
Why does lithium in Argentina and Chile matter for Europe?
Lithium in Argentina and Chile matters because Europe needs diversified critical mineral supply chains. But supply reliability depends on water governance, regulation, local legitimacy, institutional capacity and the distance between reserves and functioning projects.
Why should Argentina and Chile not be treated as one lithium market?
Argentina and Chile follow different lithium governance models. Chile has moved toward a more state-framed and sequenced model, while Argentina is more project-driven and provincially distributed. The operational risk profile differs by country, province and project.
Why is water central to lithium project risk?
Water is central because brine extraction affects complex salar and aquifer systems in extremely arid environments. Project risk depends on hydrological data, cumulative impact assessment, community concerns and the credibility of environmental governance.
What should European buyers evaluate beyond reserves?
European buyers should evaluate project-level water governance, provincial institutional capacity, indigenous consultation processes, environmental compliance, hydrological baseline data and the ability of a project to produce reliably over time.
Which companies shape the lithium market in Argentina and Chile?
Chile’s operating base is shaped by SQM and Albemarle, while Codelco and NovaAndino Litio define the stronger state-participation model. In Argentina, Eramet, Rio Tinto, Ganfeng Lithium, Lithium Argentina and other operators form a more fragmented project market across Jujuy, Salta and Catamarca.
Why is planned capacity different from actual lithium production?
Planned capacity describes what a project is designed or approved to produce. Actual output depends on commissioning, ramp-up, process reliability, gas and power supply, water management, logistics, financing and operator execution. In 2026, Eramet’s Centenario reached about 90% of nameplate capacity in June, while other projects such as Rincon remain in construction and future ramp-up.
What changed in Argentina’s lithium market in 2026?
Argentina moved further from project pipeline to execution. Cauchari-Olaroz produced 9,280 tonnes of lithium carbonate in Q2 and continued near design capacity, while its Stage 2 expansion has RIGI approval for an additional 45,000 tonnes per year of LCE. Rio Tinto secured a US$1.175 billion financing package for Rincon, Eramet’s Centenario plant reached about 90% of nameplate capacity in June, and Ganfeng closed a US$180 million strategic investment in Lithium Argentina as the companies advance the PPG consolidation.
What changed in Chile’s lithium strategy in 2026?
Chile’s strategy became more operational. NovaAndino Litio is established for the Salar de Atacama, Codelco obtained the amended CEOL for Maricunga, and Chile’s competition authority approved the ENAMI–Rio Tinto Salares Altoandinos joint venture. Rio Tinto now expects the Maricunga and Altoandinos transactions to close only in late 2026 or early 2027.
Does DLE remove lithium water risk?
No. DLE can reduce processing time and change the technical water and brine balance, and Eramet has demonstrated industrial-scale ramp-up in Argentina. But project-level hydrology, brine reinjection, freshwater use, cumulative basin effects and community confidence still need to be assessed separately.
