
Lithium &
Mining in
South America
South America’s lithium market is shaped by different national models, project operators, state companies, extraction technologies and infrastructure constraints. The region already supplies a major share of global lithium and is expected to expand output further, but strategic value depends on turning resources into reliable production, processing and long-term supply. Econosur connects those layers with suppliers, procurement, infrastructure and project execution.
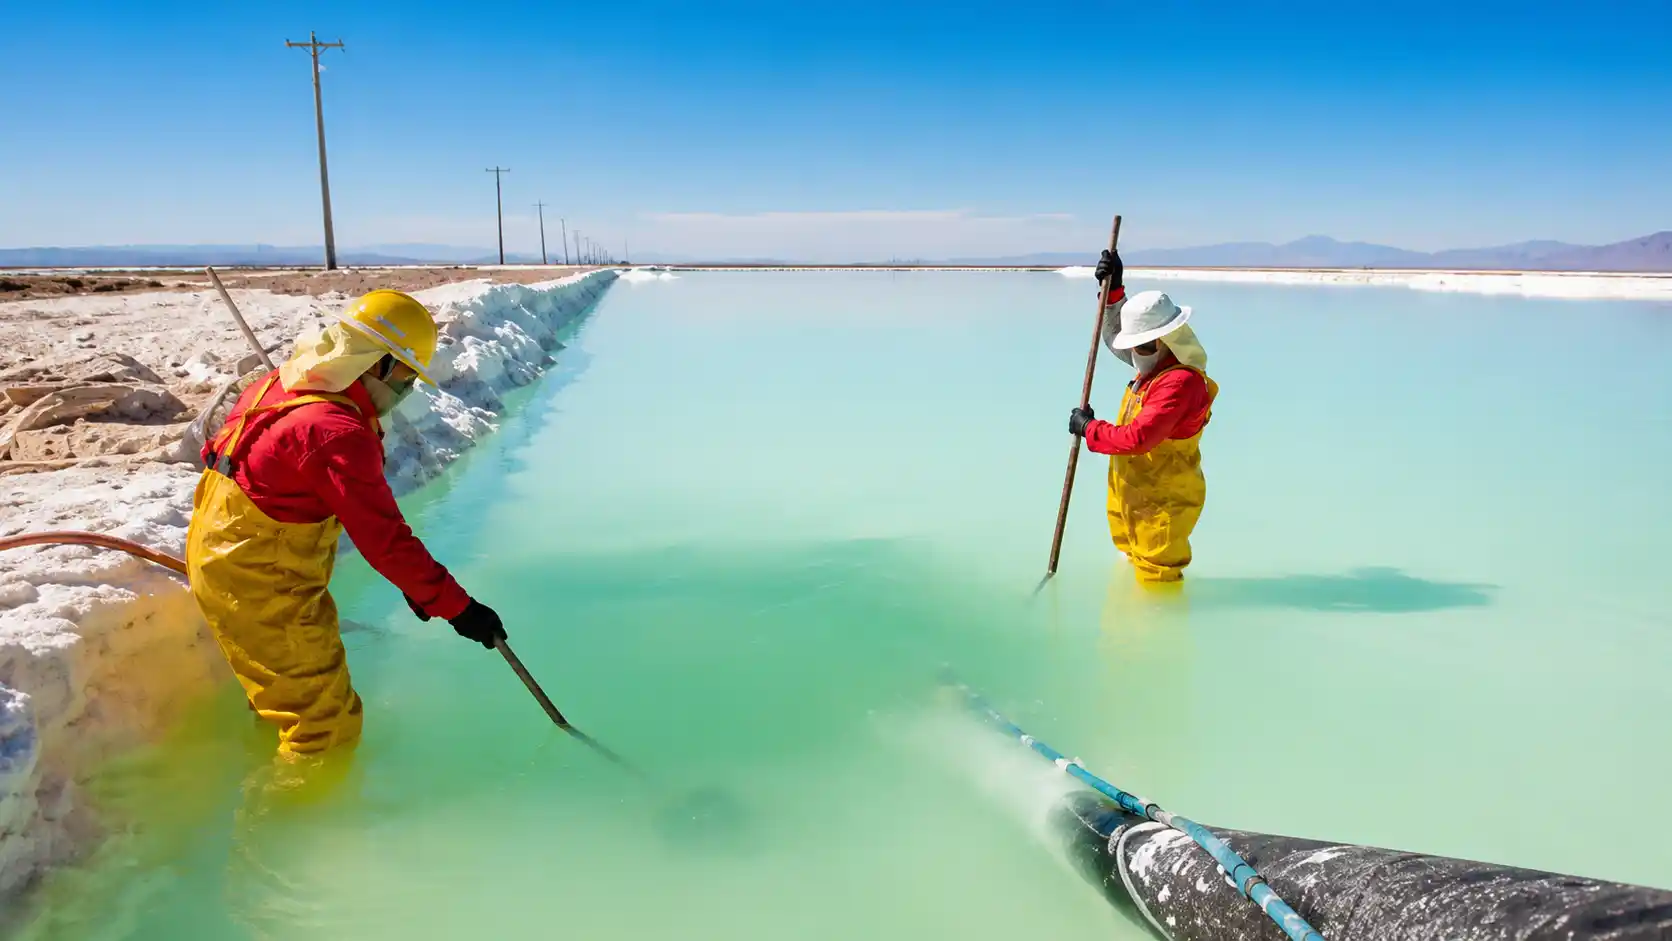
Lithium and mining are strategic sectors in South America, but they do not follow one unified market logic. Argentina, Chile and the wider regional mining layer are connected by resources, while operating models, extraction methods, infrastructure, state roles and project execution differ sharply. The Econosur analysis Lithium Is Not One Market explains why country labels alone do not describe the commercial reality. The broader supply-security context is developed in South America’s Strategic Resource Advantage in a Fragmenting World Economy.
The market is shaped by companies as much as by geology. Codelco, NovaAndino Litio, Eramet, SQM, Albemarle, Rio Tinto and other project operators determine how resources are financed, developed and connected to buyers. Water and infrastructure providers such as CRAMSA / Aguas Marítimas form a second commercial layer around extraction.
Latest Argentina analysis: who will supply the next expansion?
Argentina’s next lithium cycle is becoming a procurement question. Rio Tinto, Ganfeng and Lithium Argentina, Zijin, Eramet and POSCO operate across different project stages and sourcing models, while domestic supplier capacity is expanding around engineering, logistics, chemicals, equipment and services.
Econosur’s Who Will Supply Argentina’s Next Lithium Expansion? maps the project pipeline, DLE technology layer, supplier structure and the open question of where international specialist suppliers can still compete across Jujuy, Salta and Catamarca.
For a project-level view of how those procurement routes actually differ, the Rincón vs. Sal de Oro case analysis compares owner qualification, engineering and integration roles, regional contractors and the package-level buying points below the corporate supplier gateway.
Market signal: lithium is becoming a supply-security and execution market
Lithium now sits at the intersection of battery storage, electric mobility, industrial policy and supply-chain security. The IEA estimates that Latin America currently produces around one-quarter of global lithium supply and expects regional output to grow by nearly 50% by the end of the decade.
Demand remains structurally strong. The IEA’s 2026 outlook expects global lithium demand to more than triple by 2040 under stated policies, while project execution, refining and downstream capacity remain uneven. Resource abundance therefore matters only when production, processing, infrastructure, finance and buyer relationships align.
This is the lithium-specific version of the wider Econosur thesis in South America’s Strategic Resource Advantage in a Fragmenting World Economy: resource ownership creates potential, while control of execution and the supply chain determines who captures value.
September 2026 update: Argentina expands capacity while Chile advances new resource platforms
Argentina ended 2025 with seven lithium mines in production and record lithium exports of about US$905 million. The next expansion layer is now visible in approved projects: Cauchari-Olaroz received RIGI approval for an additional 45,000 tonnes per year of lithium-carbonate-equivalent capacity, while the Fénix Phase 1B expansion was approved for an additional 9,500 tonnes per year.
Rio Tinto has secured a US$1.175 billion financing package for its US$2.5 billion Rincón project in Salta. The project is designed around approximately 60,000 tonnes per year of battery-grade lithium carbonate capacity, with first production expected in 2028 and a multi-year ramp-up.
In Chile, ENAMI reported on 3 September that Salares Altoandinos now contains 4.46 million tonnes of lithium resources across La Isla and Aguilar, making it the country’s largest greenfield lithium resource platform by ENAMI’s assessment. Resource estimates are not reserves or production, but they materially increase the scale of Chile’s future project pipeline.
Why lithium is not one market
Argentina, Chile and Bolivia are often grouped together as if they were a single lithium story. In practice, they operate under different political, regulatory, geological and technological conditions.
Even within one country, lithium projects can differ sharply. Brine chemistry, altitude, water conditions, infrastructure access, power availability, logistics and processing choices all shape project viability. The market therefore has to be read project by project, not only country by country.
That is why lithium should not be treated as a generic South American opportunity. It is a differentiated operational landscape with distinct winners, bottlenecks and execution risks.
The relevant question is not whether South America has lithium. The relevant question is where lithium can become stable, scalable and investable production.
Lithium is not a single regional market. It is a set of different operating environments connected by global demand, but separated by local execution realities.
How country roles differ in the regional mining map
Argentina
Argentina combines 28 million tonnes of measured and indicated lithium resources in USGS 2026 with seven operating lithium mines at the end of 2025 and a broad expansion pipeline. Rincón, Cauchari-Olaroz, Fénix and other projects show that the commercial question has shifted from resource discovery toward financing, construction, ramp-up, procurement and operating reliability.
Chile
Chile combines the world’s largest reported lithium reserve base in USGS 2026 with an established Salar de Atacama production platform and new state-led resource development. ENAMI’s September update on 4.46 million tonnes of lithium resources at Salares Altoandinos expands the greenfield pipeline, while Codelco’s Maricunga framework and NovaAndino Litio extend the state’s operating role. Econosur’s Chile mining investment analysis shows how lithium sits beside a much larger copper-led reinvestment cycle.
Brazil
Brazil broadens the mining picture beyond lithium alone. Its importance comes from industrial scale, diversified mining capacity, processing potential and the ability to connect extraction with manufacturing and infrastructure.
Paraguay
Paraguay is not central to lithium extraction, but it matters through logistics, energy, river access and wider regional trade routes that can influence the mining support system.
Uruguay
Uruguay has a smaller direct mining role, but it remains relevant as part of the Southern Cone business environment, especially in logistics, institutional stability and regional market observation.
Regional layer
The mining map is shaped not only by deposits, but by energy, water, roads, ports, rail, technology providers, industrial users and export access across South America.
Which companies shape the lithium market?
South America’s lithium economy is controlled through a combination of state participation, private operators, international capital, technology choices and infrastructure providers. The company landscape therefore has to be read by function: resource control, project operation, extraction technology, processing, water, energy and market access.
Codelco
Chile’s state-owned copper company has become a central actor in the country’s lithium model. Its role connects public control, partnerships, project governance and the implementation of national resource policy.
Read the Codelco company insightNovaAndino Litio
The Codelco–SQM structure in the Salar de Atacama is a key test of how Chile combines state participation with existing operating capacity and long-term production. SQM reported 75.8 thousand tonnes LCE of Q2 2026 lithium sales from its Chile operations through Novandino, with battery-storage demand helping support volumes.
Read the NovaAndino Litio profileEramet / Centenario-Ratones
Centenario-Ratones provides an operational DLE case. Eramet reports 6.7 kt-LCE of lithium carbonate production in 2025 during its first ramp-up year, against nominal capacity of 24,000 tonnes per year, with full-capacity operation targeted by the end of 2026. The project illustrates why designed capacity and stable production must be kept separate.
Read the Eramet Centenario caseCRAMSA / Aguas Marítimas
Mining growth depends on infrastructure outside the mine. CRAMSA illustrates how seawater, desalination and transport corridors can become independent market layers serving multiple industrial users.
Read the CRAMSA company insight| Market role | Companies to track | Why the role matters |
|---|---|---|
| State control and partnerships | Codelco, ENAMI, provincial mining companies in Argentina | Licences, partnerships, public participation and project access depend on the institutional model. |
| Established brine production | NovaAndino Litio, SQM, Albemarle | Existing production, processing capacity and long-term contracts shape Chile’s current market position. |
| New projects and expansion | Eramet, Rio Tinto, Ganfeng Lithium, POSCO, Zijin Mining | Capital deployment, technology and ramp-up performance determine where new supply becomes commercially reliable. |
| Infrastructure and technical services | Water, power, EPC, automation, logistics and environmental-service providers | Many international suppliers enter through the operating system around the mine rather than through resource ownership. |
Marcus A. Volz perspective: the strategic asset is reliable lithium supply
The resource map is only the starting point. Argentina has the larger measured and indicated resource base, Chile has the larger reserve base and more mature production system, and individual projects use different technologies and commercial structures. None of those facts by itself identifies the strongest supplier opportunity.
The useful question is which project can produce battery-grade material reliably, at competitive cost, with water, energy, logistics, processing, financing and buyer relationships aligned. That is also where commercial access forms: engineering, supplier qualification, process packages, infrastructure, maintenance and traceability systems are decided before stable nameplate production is reached.
DLE should be treated with the same discipline. It can change recovery rates and process times, but lower environmental impact is not automatic. Water balance, reinjection, reagents, energy use and hydrogeology still need project-specific evidence.
This execution-focused view connects directly with South America’s Strategic Resource Advantage in a Fragmenting World Economy.
Three business questions that require deeper research
Public project data can show resources, ownership, announced capacity and technology choices. It does not show the complete commercial map. Three questions matter most for suppliers and industrial companies evaluating South America’s lithium market.
1 · Project timing
Which lithium projects are most likely to move from announced capacity into funded construction, commissioning and recurring procurement? This requires tracking permits, financing, FID, engineering maturity, technology validation, contractor appointments and evidence that project milestones are actually being executed.
2 · Supplier positioning
Where are technology providers, engineering firms and incumbent suppliers already embedded — and where can international companies still enter the qualification or specification process? The answer depends on extraction technology, project partners, EPC/EPCM structures, local-service expectations, approved vendors and the location of purchasing authority.
3 · Infrastructure dependency
Which water, power, logistics and processing constraints are likely to create separate supplier markets around lithium projects? This requires mapping who owns enabling infrastructure, which packages are procured by the operator or third parties, and whether infrastructure timing matches the mine and processing schedule.
Public sources show the project pipeline, but not the full commercial pipeline.
Corporate announcements and technical studies rarely reveal complete vendor lists, procurement calendars, qualification barriers, buyer preferences, package ownership or the point at which a planned investment becomes an actionable opportunity.
Subsectors covered by this industry theme
Lithium brines
Salt-flat based lithium projects, brine chemistry, altitude, water conditions and the operating logic of Andean extraction environments.
Direct lithium extraction
DLE can shorten process cycles and improve recovery in some brines, but it also adds technology, reagent, energy, reinjection and scaling questions. Environmental performance must be assessed project by project rather than assumed from the technology label.
Evaporation-based production
Established brine processing systems with long cycles, high dependence on local conditions and their own infrastructure and environmental implications.
Broader mining systems
Copper, industrial minerals and other extractive sectors that shape the wider business environment around investment, infrastructure and competitiveness.
Mining infrastructure
Energy, roads, water, logistics corridors, export routes, processing facilities and support systems that determine whether projects can operate at scale.
Industrial demand
Battery demand, automotive transitions, processing capacity and the question of whether extraction leads to broader industrial value capture.
Business opportunities around lithium and mining
The lithium market is relevant for mining operators, engineering firms, process-technology providers, water-management specialists, energy suppliers, logistics companies, industrial equipment manufacturers, chemical processors, investors and technical service providers.
The most accessible opportunity is often outside resource ownership. Pumps, valves, process control, power systems, roads, storage, chemicals, environmental services, camps, telecommunications, monitoring, maintenance and technical documentation form the operating layer around a project.
International companies first need to identify whether they are addressing a resource market, a project-execution market or a supplier market. That distinction determines which companies matter, where procurement authority sits, what evidence buyers expect and how the provider must present itself in the target market.
Resource layer: geology, deposit quality, brine conditions, mineral concentration and extractive potential.
Infrastructure layer: energy, water, roads, ports, camps, processing systems, transport routes and operational support.
Market layer: buyers, battery demand, industrial processing, export logic, regulation, financing and execution credibility.
Research services for South America’s lithium market
Econosur can structure custom research around a specific lithium project, operator, technology, supplier category, infrastructure dependency or procurement question. The current Argentina work also extends into targeted on-site research around Litio en Sudamérica 2026 in Jujuy, where project teams, suppliers and technology providers can be assessed against defined commercial questions. Typical assignments include:
Project-status verification
Check permits, feasibility, financing, RIGI status, FID signals, construction, commissioning, ramp-up and whether announced production milestones are advancing as described.
Supplier & technology mapping
Identify DLE and process-technology providers, engineering firms, EPC/EPCM contractors, equipment suppliers, water specialists, chemical suppliers and incumbent relationships.
Procurement & tender research
Track package timing, contracting routes, long-lead equipment, vendor requirements, supplier portals, qualification processes and commercially relevant tender signals.
Buyer & decision-chain mapping
Identify project owners, state partners, engineering firms, contractors, procurement teams and technical decision makers around a defined product or service category.
Infrastructure dependency analysis
Map water, electricity, roads, logistics, processing and export constraints that can determine project timing and create adjacent supplier demand.
Local capability assessment
Check domestic supplier coverage, service capability, local-content requirements and the points where imported or specialist capability may still be needed.
Company & competitor research
Compare operators, state partners, investors, technology providers, incumbent suppliers and competing commercial positions across Argentina, Chile and the wider region.
Primary-source verification & market checks
Combine official records, company documents and focused conversations with suppliers, contractors and technical specialists to test questions that public sources do not resolve.
Need project- or supplier-level lithium research?
Econosur connects lithium projects with ownership, technology, infrastructure dependencies, procurement timing, supplier positioning and execution risk across South America.
Explore custom market analysisFrequently asked questions about lithium and mining
Why does lithium and mining matter in Mercosur and South America?
Lithium and mining matter because they connect natural resources with industrial policy, export earnings, energy infrastructure, logistics and global demand for battery materials and critical minerals. The sector has strategic weight, but outcomes depend on execution rather than geology alone.
Is lithium one market across South America?
No. Lithium is not one market. Argentina, Chile and Bolivia differ in operating models, state involvement, investor logic, extraction methods, infrastructure conditions and project timelines. Even within one country, project realities can diverge sharply.
Which countries are most relevant for this sector?
Argentina and Chile are the main reference markets for lithium in the southern part of South America, while Brazil adds broader mining depth and industrial scale. Paraguay and Uruguay matter more through logistics, regional trade, energy and market access than through lithium extraction itself.
What matters beyond the resource base?
Resource quality is only one layer. Mining outcomes also depend on water, energy, roads, ports, processing, technology, permitting, community relations, regulation, financing and the ability to move from announcement to stable production.
How does direct lithium extraction differ from evaporation-based production?
Direct lithium extraction and evaporation follow different operational logics. DLE can shorten processing cycles and improve recovery in some brines, but it does not automatically mean lower environmental impact. Water balance, brine reinjection, reagents, energy use and hydrogeology remain project-specific. Evaporation-based models are more established but slower and highly dependent on local climatic and geological conditions.
Why are energy, water and logistics so important in mining?
Mining projects become viable only when extraction can be connected to power, water access, transport routes, processing, export infrastructure and operating stability. A deposit without the supporting infrastructure remains a weak market asset.
Which companies shape the lithium market in Argentina and Chile?
The market includes state actors, established brine producers, international project developers and infrastructure providers. Econosur follows Codelco, NovaAndino Litio, SQM, Albemarle, Eramet, Rio Tinto, Ganfeng Lithium, POSCO, Zijin Mining and companies supporting water, power, engineering and logistics.
Why is South American lithium becoming more strategically important?
Latin America currently produces around one-quarter of global lithium supply and the IEA expects regional output to grow by nearly 50% by the end of the decade. The strategic value depends on whether resources become reliable production connected to processing, infrastructure, finance, traceability and long-term buyers.
What supplier and procurement research does Econosur provide?
Econosur provides project-status verification, supplier and technology mapping, buyer research, procurement and tender research, infrastructure analysis and targeted market checks for companies working with South America’s lithium supply chain.
Need a lithium market, company or project analysis?
Econosur prepares sector briefs, company reports and custom analysis for organisations evaluating lithium markets, projects, suppliers and infrastructure in South America. The analysis can focus on Argentina, Chile, a specific company, a project or a defined supplier opportunity.
Explore custom market analysis