
Paraguay:
Hydropower,
Industry
and Logistics
Paraguay is a small domestic market with a growing regional operating role. Hydropower, maquila manufacturing, river logistics, the Bioceanic Corridor, agribusiness and Mercosur access connect the country to Brazilian demand and wider South American supply chains.
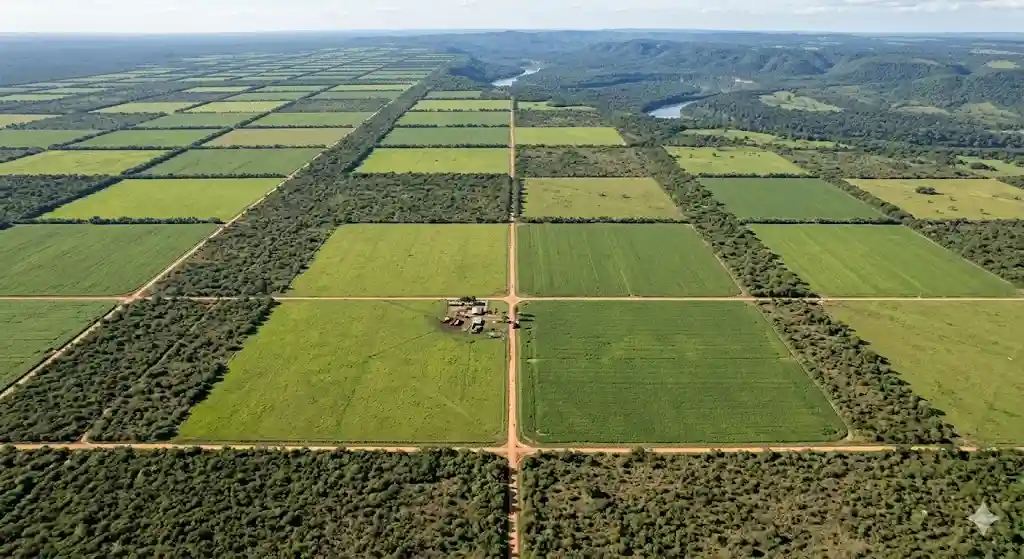
Paraguay 2026: growth, industrial exports and rising electricity demand
Paraguay’s economy expanded 5.8% year on year in the first quarter of 2026. The Banco Central del Paraguay attributed the growth to positive contributions from services, manufacturing, agriculture, construction and electricity distribution.
The industrial layer is becoming more visible. Maquila exports reached US$1.01 billion between January and August 2026, 26% above the same period of 2025. The Ministry of Industry and Commerce reported that auto parts, apparel, beverages and alcoholic liquids, and aluminium manufactures together accounted for 70% of exports under the regime.
At the same time, electricity consumption is rising quickly. ANDE reported that national electricity consumption reached 14,587.1 GWh in the first five months of 2026, up 19.4% from 12,217.6 GWh in the same period of 2025. Paraguay’s power advantage therefore needs to be read together with grid capacity, location, tariff design and future demand.
Paraguay is increasingly useful to read as an operating system rather than only as a small domestic market. The country links Brazilian industrial demand with maquila production, hydropower with energy-intensive investment, inland manufacturing with the Hidrovía and new Chaco infrastructure with Atlantic-Pacific logistics.
Core market reading: Paraguay’s advantage lies in combinations. Low-cost power matters when the grid can deliver it. Maquila matters when production can reach Brazilian and Mercosur buyers. River access matters when water depth, terminals and barges are reliable. New roads matter when border and customs systems are operational.
A small market with several regional functions
Paraguay does not compete with Brazil or Argentina across the full industrial system. It performs narrower functions where energy, labor, tax structures, geography or logistics create a cost or execution advantage.
Alto Paraná is closely connected to Brazilian demand and border-facing manufacturing. Greater Asunción and the Central Department support metropolitan production and logistics. Concepción links livestock, meat processing, forestry, planned pulp production and Paraguay River access. The Chaco is becoming more relevant through the Bioceanic Corridor and new road infrastructure.
Alto Paraná
Brazil-facing manufacturing, maquila production, border commerce and regional supply chains.
Central Paraguay
Manufacturing, labor, logistics, services and access to the metropolitan market and river terminals.
Concepción & Chaco
Resource processing, river logistics, forestry, meat, pulp infrastructure and new cross-border road corridors.
Hydropower and electricity: advantage meets demand growth
Paraguay’s electricity system remains one of its most distinctive structural assets. Itaipu, Yacyretá and Acaray provide a predominantly hydroelectric supply base that supports households, commerce and increasingly industrial and digital loads.
The commercial interpretation is changing as consumption rises. ANDE reported that national electricity consumption increased from 12,217.6 GWh in the first five months of 2025 to 14,587.1 GWh in the same period of 2026, an increase of 19.4%. May demand alone reached 2,382.8 GWh, 11.9% above May 2025.
For an energy-intensive investor, the relevant question is therefore more specific than whether Paraguay produces abundant hydropower. It is whether sufficient electricity can be delivered reliably at the required site, voltage and timeframe and how network investment, future demand and commercial power conditions affect the operating case.
September 2026: ATOME makes the industrial power question concrete
ATOME’s planned low-carbon fertilizer project in Villeta is a direct test of Paraguay’s strategy of converting hydropower into higher-value industrial production. The company describes a 145 MW project and says electricity represents roughly 60–70% of production cost, making long-term power pricing central to project economics.
On September 17, ATOME served Paraguay with a Notice of Dispute and Intent to Submit a Claim to Arbitration concerning the project and its power framework. These are ATOME’s claims and have not been adjudicated. Paraguay’s Attorney General’s Office stated that no lawsuit or arbitration had yet been initiated and that the notice opens a three-month period to seek an amicable solution.
The case shows why Paraguay’s electricity advantage must now be evaluated through tariff durability, contract structure and utility economics as well as generation abundance. See Econosur’s ATOME analysis and the broader Paraguay power-grid and regulation analysis.
Paraguay’s electricity advantage remains real, but its commercial value increasingly depends on location, grid capacity, tariff durability, contract structure and competing demand.
Maquila and industrial production: Paraguay’s manufacturing layer is getting larger
The maquila regime has become one of the clearest indicators that Paraguay’s economy is moving beyond a simple agriculture-and-energy narrative. Between January and August 2026, maquila exports reached US$1.01 billion, up 26% year on year. The August update confirmed that the regime had surpassed US$1 billion in exports within the first eight months of the year.
Auto parts, apparel, beverages and alcoholic liquids, and aluminium manufactures accounted for 70% of maquila exports through August. The regime remains strongly export-oriented and continues to deepen Paraguay’s role in regional manufacturing and cross-border supply chains.
Econosur’s Industrial Side Door analysis shows how this model works across different production geographies. The Auto-Parts Maquila Corridor provides the sector-level example: Paraguay produces selected labor-intensive components inside a regional automotive system whose main industrial centre remains Brazil.
Automotive Components
Wire harnesses and electrical components connect Paraguayan factories with Brazilian and regional vehicle production.
Export Manufacturing
Textiles, aluminium products, plastics, food and chemical-pharmaceutical goods broaden the industrial export base.
Supplier Demand
Industrial expansion creates demand for machinery, automation, electrical systems, maintenance, quality systems and technical services.
Paraguay River economy: the Hidrovía is existing infrastructure, not a future concept
Paraguay may be landlocked on a map, but its international trade system is built around river access. The Paraguay-Paraná Hidrovía connects inland production, ports, private terminals, barge fleets and downstream routes to the Río de la Plata and Atlantic markets.
An industry study cited in Econosur’s Paraguay River Economy analysis estimated that the Hidrovía carries around 70% of Paraguay’s exports and approximately half of its imports. The estimate is industry-specific rather than an official universal statistic, but it illustrates the scale of the country’s river dependency.
Water depth, dredging, terminal capacity, barge availability, customs, downstream regulation and transshipment connections therefore become commercial variables. Low water can reduce draft, lower cargo per barge and raise the cost and timing risk of exports.
Logistics implication: production cost inside Paraguay is only one part of competitiveness. River conditions and downstream execution can materially change the delivered cost and reliability of Paraguayan exports.
Bioceanic Corridor: the bridge is physical, corridor readiness is operational
The Bioceanic Corridor is moving from a long-term map concept into physical infrastructure. By August 19, MOPC reported that the lower form travellers used to construct the central cable-stayed section were being removed, marking the close of one of the main construction phases. The 1,294-metre bridge between Carmelo Peralta and Puerto Murtinho was therefore moving into its final construction stage.
The bridge alone does not create a functioning Atlantic-Pacific trade corridor. Access works in Carmelo Peralta, remaining sections of PY15, border infrastructure, customs coordination and the quality of onward road connections determine when the corridor becomes commercially reliable for international freight.
The road component has advanced further since that June update. On September 1, MOPC reported that Lot 2 of the Mariscal Estigarribia-Pozo Hondo section of PY15 had completed 100% of its earthworks and 20 kilometres of asphalt-mix base. The lot forms part of the 224-kilometre third section of the Bioceanic Corridor. This reduces one construction uncertainty, but the full commercial route still depends on completion of the remaining road sections, border facilities, customs systems and onward connections.
Corridor reading: the bridge is becoming real infrastructure. The business case depends on the entire operating chain around it. See Econosur’s Bioceanic Bridge corridor-readiness analysis.
Agriculture and processing remain central, but no longer define the whole market
Soy, cattle, beef and other agricultural value chains remain fundamental to Paraguay’s export economy. Their relevance extends beyond farm output into inputs, storage, crushing and processing, cold chain, terminals, river transport and international buyer requirements.
The environmental and compliance layer is also becoming more important. Soy and beef supply chains face growing scrutiny around traceability, land use and deforestation. For exporters and buyers, compliance requirements increasingly sit alongside commodity price, transport cost and product quality.
Concepción illustrates the processing side of the economy. Frigorífico Concepción connects livestock with industrial processing, sanitary requirements and cold-chain exports. Paracel represents a larger attempt to connect plantations, energy, roads, port infrastructure and planned pulp production into an integrated industrial platform.
Mercosur and Brazil: Paraguay’s largest market sits next door
Paraguay’s industrial model is closely tied to Mercosur, especially Brazil. For maquila manufacturers, Brazil provides a large nearby buyer base, established industrial supply chains and demand for intermediate goods. That proximity is one of the central reasons selected manufacturing stages can operate competitively from Paraguay.
The same relationship creates dependency. Brazilian production cycles, buyer requirements, regional origin rules, border efficiency and road logistics can determine the performance of Paraguayan factories. The relevant commercial analysis therefore has to include both Paraguay’s cost structure and the demand system across the border.
Ciudad del Este represents another layer of the Brazil connection: imported goods, taxation differences, retail flows and Brazilian consumer demand create a cross-border commercial system that works differently from formal industrial production.
Companies and projects show how the model works
Yazaki Paraguay
Yazaki shows how automotive wiring, workforce, quality systems and maquila production connect to regional vehicle supply chains.
Paracel
Paracel links forestry, planned pulp production, energy, roads, river access and project execution.
Frigorífico Concepción
Frigorífico Concepción provides a processing, certification and cold-chain example inside Paraguay’s agricultural economy.
ATOME Villeta
ATOME’s Villeta fertilizer project adds a different industrial case: a large energy-intensive investment whose viability depends directly on long-term electricity economics. The September 2026 dispute with Paraguay makes power pricing and contract durability part of the country’s investment-location story.
Three business questions that require deeper research
1. Which Paraguayan industrial and infrastructure projects are moving from incentives and announcements into actual procurement and supplier demand?
National investment promotion and export growth identify market direction. Supplier opportunity depends on factory construction, equipment packages, contractor appointments, procurement timing, qualification and whether projects are actually executing.
2. Where does Paraguay’s electricity advantage still create a meaningful operating-cost benefit once grid capacity, location, power conditions and future demand are included?
Hydropower provides the structural advantage, but site-level feasibility depends on network capacity, connection requirements, reliability, tariff conditions, contract durability and competing electricity demand. The ATOME case shows that the long-term power arrangement can become a project-level investment issue even when generation itself is abundant.
3. Which production and logistics routes into Brazil, Mercosur and global export markets are commercially reliable today, and which still depend on unfinished infrastructure or river conditions?
The answer differs between road-based manufacturing, border commerce, bulk river exports and future Bioceanic Corridor traffic. Route choice has to include actual roads, ports, terminals, customs, hydrology and buyer location.
Where Published Information Stops
Public sources show incentives, export growth, infrastructure projects, electricity generation and major companies. They do not provide the complete commercial map.
Published information rarely shows complete buyer lists, project procurement calendars, factory-level power availability, approved supplier requirements, distributor performance, actual border delay, port capacity by customer, local service expectations or whether a specific foreign supplier fits a Paraguayan production system.
Those questions require supplier and buyer research, project verification, logistics checks, procurement research and targeted market conversations.
Research services for Paraguay
Econosur can structure research around one defined Paraguay question: an industrial sector, project, supplier category, buyer group, electricity requirement, logistics route, competitor set or procurement assumption.
Where the objective is a concrete commercial connection, Econosur can also identify and screen potential buyers, suppliers, distributors and business partners in Paraguay and facilitate introductions where there is a relevant fit. See B2B Connections in South America.
Market & Sector Screening
Compare industrial, logistics, energy, agribusiness and processing opportunities through current market evidence.
Supplier & Competitor Mapping
Identify local and international suppliers, contractors, distributors, incumbents and competing positions.
Buyer Research
Map factories, processors, project companies, importers, operators and organizations influencing purchasing decisions.
B2B Connections in Paraguay
Identify and screen relevant buyers, suppliers, distributors and business partners and facilitate direct introductions where the commercial requirement and counterparty fit are clear. Explore B2B Connections.
Procurement Research
Track equipment demand, tender timing, package ownership, contractor structures and qualification requirements.
Project-Status Verification
Distinguish announced, approved, financed, under-construction, delayed and operating investments.
Power & Location Checks
Compare industrial locations through electricity access, network constraints, logistics, labor and proximity to buyers.
Logistics & Corridor Checks
Assess river routes, road corridors, ports, border crossings and the infrastructure behind delivered cost.
Primary Market Checks
Test assumptions through focused conversations with relevant companies, suppliers and market participants where practical.
Frequently asked questions about Paraguay
Why is Paraguay strategically important despite its small economy?
Paraguay combines hydropower, export-oriented manufacturing, river logistics, agribusiness and Mercosur access. Its commercial role is larger than its domestic market because it connects Brazilian demand, regional production and Atlantic export routes.
How is Paraguay’s maquila industry changing the market?
Maquila exports reached US$1.01 billion between January and August 2026, up 26% year on year. Auto parts, apparel, beverages and alcoholic liquids, and aluminium manufactures accounted for 70% of exports under the regime.
Does Paraguay still have an electricity advantage?
Hydropower remains a major structural advantage, but domestic electricity demand is rising rapidly and long-term industrial power pricing is becoming more consequential. Commercial assessments increasingly need to include grid capacity, location, tariff structure, contract durability and future demand rather than relying only on national generation surplus.
What does the ATOME dispute reveal about Paraguay’s power advantage?
It shows that abundant hydropower does not automatically produce a bankable long-term industrial electricity contract. ATOME served a Notice of Dispute on September 17, 2026; Paraguay says no lawsuit or arbitration has yet been initiated and that a three-month period for an amicable solution is now open.
Why is the Hidrovía important for Paraguay?
The Paraguay-Paraná river system provides the structural outlet connecting Paraguayan production with downstream ports and Atlantic markets. Water depth, terminals, barges, dredging and regional regulation directly affect trade costs and reliability.
Why does the Bioceanic Corridor matter?
The corridor can strengthen Paraguay’s connection with Brazil and Chilean Pacific ports. By August 2026 the bridge’s central construction phase was nearing completion, while road access, PY15 sections, border systems and customs infrastructure remained part of the execution challenge.
How can Econosur research a Paraguay market question?
Research can be structured around a defined industrial sector, project, supplier category, buyer group, electricity requirement, logistics route or procurement question and can combine public-source analysis with supplier mapping, project verification and targeted market checks.
Can Econosur help identify buyers, suppliers or business partners in Paraguay?
Yes. For a defined commercial requirement, Econosur can research and screen potential buyers, suppliers, distributors and business partners in Paraguay and facilitate an introduction where there is a relevant fit. See B2B Connections in South America.
Need a defined Paraguay research question answered?
Econosur can structure research around a specific industrial sector, supplier category, project, electricity requirement, buyer group or logistics route and combine public evidence with targeted commercial validation.
Discuss a Paraguay research question