Brazil · Energy · Biomethane · Waste · Regulation · Infrastructure
Green Gas in Brazil: Waste, Regulation and the Infrastructure Gap Behind Biomethane Scale
Brazil's biomethane market has moved further from regulatory design into implementation. ANP rules now define individual compliance targets, CGOB certification and a unified quality standard, while September technical guidance enables the certification process to begin. The remaining question is whether infrastructure, project economics and long-term offtake can convert that architecture into scalable supply.
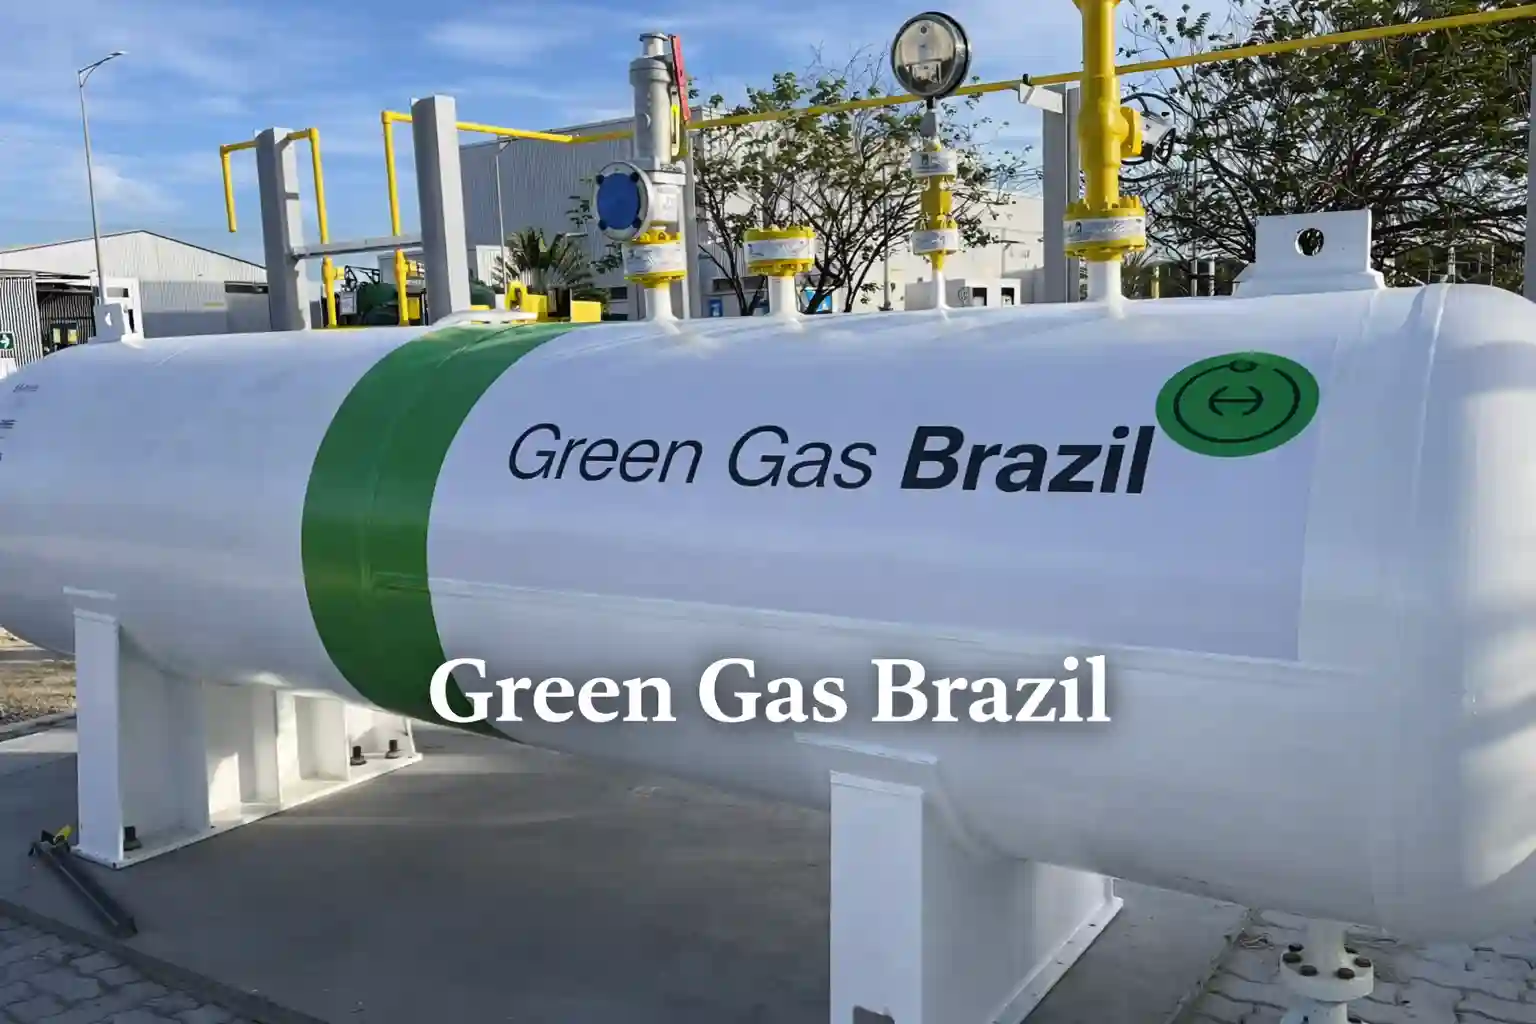
Brazil's biomethane market has moved from regulatory intent to a more operational market architecture.
The Fuel of the Future law created the obligation. In 2026, ANP Resolutions 995 and 996 defined individual compliance and the CGOB certification chain, while Resolution 1.006 unified biomethane quality rules across feedstocks. On September 1, ANP published technical guidance detailing the procedures and documentation needed to begin certification of biomethane producers and importers for CGOB issuance. That moves the market another step from regulatory design into execution. Infrastructure, project economics, state-level distribution rules and long-term offtake now carry more of the execution risk.
For wider context, see Brazil insights, the Brazil market profile and Econosur’s analysis of energy and infrastructure in South America.
Core thesis:
Brazil's biomethane market is not primarily a green-energy story. It is a market-architecture story. The regulatory layer is now much more defined than it was at the start of 2026; infrastructure, local gas-market access, project economics and offtake increasingly decide whether feedstock potential becomes bankable supply.
Brazil's energy identity in international discourse is usually built around a familiar shortlist: hydropower, ethanol and offshore oil. Biomethane rarely appears in that first sentence. That omission is becoming harder to defend. ANP's 2026 Statistical Yearbook now provides biomethane production data through 2025, while the regulator's dynamic producer panel was updated again on September 17, 2026. ANP's 2025 management report says authorised biomethane production capacity increased 43.7 percent during 2025.
The Fuel of the Future law added the missing demand-side mechanism: an annual decarbonisation obligation for natural-gas producers and importers that can be met through biomethane use or CGOBs. By 2026, that framework is no longer just statutory. ANP has issued the rules for individual targets, certification and market operation.
The more important shift is not technological. It is commercial. Organic waste — previously treated mainly as a cost, a liability or a compliance problem — is being reframed as feedstock for a regulated, certifiable and tradeable energy molecule. That changes the logic for landfill operators, sugar-ethanol mills, municipal waste systems, gas distributors, fleet operators and industrial buyers.
It also creates a harder analytical question: where does Brazil actually have a scalable market, and where does it only have theoretical feedstock potential?
September 2026: the biomethane rulebook is moving into execution
The most important change since the earlier version of this analysis is regulatory implementation. In March, ANP published Resolution 995/2026 for individual annual obligations and Resolution 996/2026 for the CGOB certification, bookkeeping and registration chain. By August, the regulator was already publishing accredited origin-certification agents.
On August 12, ANP published Resolution 1.006/2026. It replaces the separate 2022 biomethane specifications for landfill/sewage and agricultural/commercial feedstocks with a single quality framework regardless of origin. The resolution also updates testing methods and monitoring requirements and creates limited routes for ANP-approved technical exceptions where safety and final gas quality remain protected.
Implementation moved another step on September 1, when ANP published two technical notices that detail the procedures and documentation required for certification of biomethane producers and importers with a view to CGOB issuance. ANP’s technical-information page was updated again on September 17, while the dynamic biomethane producer panel was also refreshed on September 17. The certification framework is therefore no longer only a legal structure; the administrative process needed to use it is being put into operation.
Marcus A. Volz reading:
The market has crossed an important threshold. The main uncertainty is no longer whether Brazil will define biomethane quality, certificate and compliance rules. Those layers are increasingly operational, and September guidance now gives producers and importers a practical route into the certification process. The commercial bottleneck is shifting toward project-level execution: where the gas is produced, how it reaches a buyer, who pays for connection or transport, how CGOB value is captured and whether the offtake contract supports financing.
Why the Mandate Changes the Market
Before the Fuel of the Future law, Brazil's biomethane market depended largely on voluntary corporate demand: companies buying renewable gas for fleet decarbonisation, ESG commitments or industrial emissions targets. That market existed, but it was discretionary. The new law changes the demand architecture.
From 2026, the programme starts with a 1 percent national greenhouse-gas reduction target for the natural-gas market. The obligation is not a simple physical blending mandate. Under Law 14.993/2024 and Decree 12.614/2025, the target is converted into an annual volumetric obligation and can be met through biomethane acquisition or use, or through the acquisition and retirement of CGOBs. The national target may be revised annually and cannot exceed 10 percent.
ANP Resolution 995/2026 then allocates that national obligation across covered producers and importers, while Resolution 996/2026 defines the CGOB certification chain. This matters because the compliance mechanism can create demand even where the physical biomethane molecule is not delivered directly to the obligated gas company. Rystad estimated that a 10 percent emissions-reduction scenario based on 2024 demand would correspond to roughly 5.1 million cubic metres per day of biomethane equivalent — far above current production. The useful point is therefore the scale gap, not a literal 10 percent blending requirement.
"Brazil does not lack organic waste. It lacks the full commercial architecture required to turn dispersed waste streams into reliable, certifiable and bankable gas supply."
Gás Verde: What the Leading Operator Reveals
Gás Verde, headquartered in Rio de Janeiro, describes itself as the largest biomethane producer in Brazil and Latin America — a claim consistent with available capacity data. Its Seropédica plant in Rio de Janeiro state holds approximately 204,000 Nm³/day of biomethane capacity, making it the largest single facility of its kind in the region.
Gás Verde currently describes production at roughly 160,000 m³/day and plans to reach about 650,000 m³/day by 2029 through nine additional plants. In 2026, the company also expanded its product mix with green CO₂ and continued adding industrial offtake agreements, reinforcing the point that the commercial model extends beyond a single gas molecule.
The company is important not only because of its size. It shows the business model toward which the sector is moving. Revenue no longer depends only on gas sales. Gás Verde combines biomethane for industrial and fleet use, renewable electricity, traceability certificates and green CO₂ for industrial clients.
This is where the economics become more interesting: the same waste stream can support several revenue channels when infrastructure, certification and offtake are aligned.
The Feedstock Structure: Brazil Has Potential, But Not in One Place
Brazil's biomethane potential is large, but it is geographically uneven. Urban landfill gas currently dominates operational capacity, especially in São Paulo and Rio de Janeiro. These locations are close to demand hubs and existing gas infrastructure.
The largest untapped potential, however, lies in agribusiness. Sugar-ethanol residues such as vinasse and filter cake offer major production potential because they occur at scale across Brazil's mill infrastructure.
This creates a structural tension. Landfill biomethane is often closer to gas consumers and pipeline access. Agricultural biomethane is more dispersed and frequently located inland. That means the market cannot be evaluated only by feedstock volume. It has to be evaluated by the relation between feedstock density, transport distance, grid access, state-level regulation and long-term offtake.
In practical terms, Brazil may have strong national biomethane potential while still having very different regional project economics.
A parallel market-design question is appearing in Brazilian agriculture.
The Google–Terradot rice and carbon-removal project is not a biomethane or CGOB project. It combines methane reduction in rice cultivation with enhanced rock weathering and sells verified climate outcomes to a corporate buyer. The useful comparison is narrower: in both markets, measurement, certification or verification is becoming part of the commercial product rather than an administrative layer added after production.
The regulatory risk has moved.
At the start of the market build-out, a central uncertainty was whether Brazil would create a workable national compliance and certification architecture. By August 2026, much of that layer is defined. The harder question is now whether individual projects can connect feedstock, quality compliance, CGOB value, transport or injection, state-level distribution rules and a creditworthy buyer in one economic system.
That changes how I would screen the market: national biomethane potential is useful context, but the commercially relevant unit is the project corridor between feedstock and buyer.
The Infrastructure Gap Behind the Green-Gas Narrative
The regulatory framework advanced materially during 2026. ANP Resolution 995/2026 sets the rules for individual annual obligations. Resolution 996/2026 governs producer and importer certification, CGOB backing, origin-certifier accreditation, bookkeeping and registration. ANP was already publishing accredited origin-certification agents by August, and on September 1 it added the technical instructions needed to begin producer and importer certification.
On August 12, ANP published Resolution 1.006/2026, replacing Resolutions 886/2022 and 906/2022 and consolidating biomethane quality specifications in one rule regardless of feedstock origin. The new standard updates testing and quality-control procedures, harmonises monitoring requirements and permits limited technical flexibility under prior ANP approval, including exceptional cases for industrial consumers, power generation, captive fleets and network injection where final gas quality remains compliant.
These steps reduce ambiguity around product definition, certification and compliance. They do not remove the physical and commercial constraints that determine whether a project works.
But regulation does not remove the physical problem. A biomethane market needs collection, upgrading, compression, injection or transport, certification, contracting and end-use demand. In regions without pipeline access, producers need cost-competitive logistics or alternative local offtake. Several states still lack specific rules for local biomethane distribution, and isolated projects remain exposed to higher transport and contracting costs.
This is the gap between policy ambition and market formation.
Investor lens:
The relevant question is not simply whether Brazil has enough waste. It is whether each project sits inside a workable system: feedstock density, plant scale, transport route, certificate value, credit structure, buyer demand and regulatory clarity.
Cost Structure and Offtake Will Decide the Pace
Biomethane prices in Brazil have ranged between BRL 2.20 and BRL 3.95 per cubic metre — approximately USD 9.20 to USD 18.10 per MMBtu — depending on feedstock, scale and logistics, according to Rystad Energy. At the lower end, biomethane can compete with natural gas in specific applications. At the upper end, it requires either a carbon value, a compliance obligation, a premium buyer, or a long-term offtake structure that spreads risk over time.
Petrobras moved early with its January 2025 biomethane procurement call, seeking firm contracts with deliveries beginning in 2026, terms of up to eleven years and multiple delivery points including refineries, thermal plants, transmission and distribution networks. The official procurement page still shows the process in its negotiation phase and does not publish final contract awards. The demand signal therefore remains important, but public evidence should not be read as confirmation of awarded long-term supply volumes.
But this structure will not automatically reach smaller producers, municipalities or dispersed agricultural projects. The market's depth will depend on whether similar offtake mechanisms emerge beyond the largest operators.
Why This Matters for Brazil's Energy Transition
Brazil generates 81.6 million tonnes of municipal solid waste annually. In 2024, only 3.2 percent of that volume was used for biomethane production, according to Abrema. From one perspective, this shows how much runway remains. From another, it shows how much infrastructure still has to be built before the available waste base becomes reliable energy supply.
The model emerging in Brazil is structurally more interesting than a conventional energy play. It does not require new resource extraction. It does not compete for land in the same way as first-generation biofuels. It converts an existing liability into a gas, certification and decarbonisation market.
But scale will not be determined by narrative. It will be determined by the slower mechanics of infrastructure, regulation, finance and buyer commitment.
For the wider Brazil context, see Brazil insights, the Google–Terradot rice and carbon-removal value chain and the case of Faber-Castell's pine forest model in Brazil. The Google–Terradot case is a different market from biomethane, but it provides a useful comparison for how verification and long-term demand can become part of the commercial architecture of an environmental product.
For the regional energy and resource frame, see Cono Sur insights, Lithium Is Not One Market and Añelo and the Vaca Muerta infrastructure economy.
The Larger Argument: Waste Becomes Strategic Only When the System Works
Brazil's biomethane opportunity is real because it sits at the intersection of waste management, gas infrastructure, industrial decarbonisation and agricultural production. But that also makes it vulnerable to oversimplification. Waste does not become strategic energy merely because it exists. It becomes strategic when it can be collected, upgraded, certified, transported and sold through a contract structure that supports capital deployment.
That is the central distinction. Brazil is no longer only designing a green-gas market. The national compliance, CGOB and quality architecture is taking operational form. The next test is more granular: whether enough individual projects can bridge feedstock, certification, transport, injection or local delivery, financing and bankable demand at competitive cost.
Brazil’s biomethane market should be evaluated project by project, not only by national waste potential.
The useful questions are feedstock density, pipeline access, local offtake, CGOB value, financing structure, state regulation, logistics cost and whether the buyer side can support bankable contracts.
VolzMarketing’s Energy, Oil, Gas & Infrastructure service translates these market conditions into a practical commercial approach for equipment manufacturers, technology providers, engineering firms and industrial-service companies targeting Brazil and Mercosur.
From waste potential to energy-market reality
Brazil’s green-gas opportunity depends on more than organic waste. Biomethane scale requires regulation, certification, infrastructure, offtake, project finance and regional project economics that can turn dispersed waste streams into reliable supply.
Econosur prepares custom market analysis for companies, analysts and institutions evaluating Brazil energy transition, biomethane, waste-to-energy, gas infrastructure, offtake structures and commercial execution risk in South America.
Explore custom market analysisFAQ
What is the Fuel of the Future law in Brazil?
Brazil’s Fuel of the Future law, Law 14.993/2024, created an annual decarbonisation obligation for the natural-gas market. The initial 2026 national target is 1 percent. It is converted into a volumetric obligation and may be met through biomethane use or acquisition, or through CGOBs; it is therefore not simply a physical blending mandate.
How is Brazil’s biomethane production base changing?
ANP’s 2026 Statistical Yearbook now publishes biomethane production data through 2025, and the regulator’s dynamic producer panel was updated on September 17, 2026. ANP also reported that authorised biomethane production capacity increased 43.7 percent during 2025. The market is expanding, but regulated demand could still grow much faster than physical supply.
What is a CGOB certificate?
A CGOB, or Biomethane Guarantee of Origin, is a certificate that verifies the renewable origin of biomethane. It makes the environmental attribute of biomethane traceable and tradable separately from the physical gas molecule.
Which companies are leading biomethane in Brazil?
Gás Verde is one of the leading operators in Brazil’s biomethane market and describes itself as the largest biomethane producer in Brazil and Latin America. Petrobras is also important because its 2025 procurement initiative created a signal for long-term biomethane contracts beginning in 2026.
Why is landfill gas easier to scale than agricultural biomethane?
Landfill gas projects are usually closer to urban demand centres, concentrated waste streams and existing infrastructure. Agricultural biomethane has larger long-term potential, especially in Brazil’s sugar-ethanol sector, but production is more geographically dispersed and often far from the natural gas grid.
- Brazil — Law 14.993/2024 (Fuel of the Future): biomethane programme, initial 1% target and maximum 10% national emissions-reduction target.
- ANP — National Programme for Decarbonisation of Natural Gas Producers and Importers and Incentive to Biomethane.
- ANP — Resolutions 995/2026 and 996/2026: individual compliance targets and CGOB certification architecture.
- ANP — Resolution 1.006/2026: unified biomethane specification and quality-control rules, published August 12, 2026.
- ANP — accredited Biomethane Origin Certification Agents, updated August 17, 2026.
- ANP — September 1, 2026 technical notices detailing the procedures and documentation required to begin certification of biomethane producers and importers for CGOB issuance.
- ANP — Dynamic Biomethane Producers Panel, data updated September 17, 2026.
- ANP — Brazilian Statistical Yearbook 2026, including biomethane production and feedstock data through 2025.
- Petrobras — biomethane procurement call: deliveries from 2026, contract terms of up to eleven years and multiple delivery points.
- Gás Verde — current production footprint and expansion target to approximately 650,000 m³/day by 2029.