Brazil · Election 2026 · Investment · Infrastructure
Brazil After the First Round: Where Private Investment Meets Public Priorities
Brazil’s election brings the relationship between private capital and public priorities into focus. The economic question is how transport, energy and industrial ambitions become financeable projects—and where that process can break down.
The decisive overlap is between public objectives and projects that private capital can finance and operate.
Transport links, reliable energy and industrial capacity can serve both sides. But a priority in a government programme is only the beginning: demand, revenue, financing, permits and the allocation of risk determine whether investment follows.
Brazil’s election matters because it can change how the state organises that interface. The relevant distinction is between an announced ambition, an investable project and an asset that actually improves the economy.
What the Election Changes—and What Still Needs to Be Built
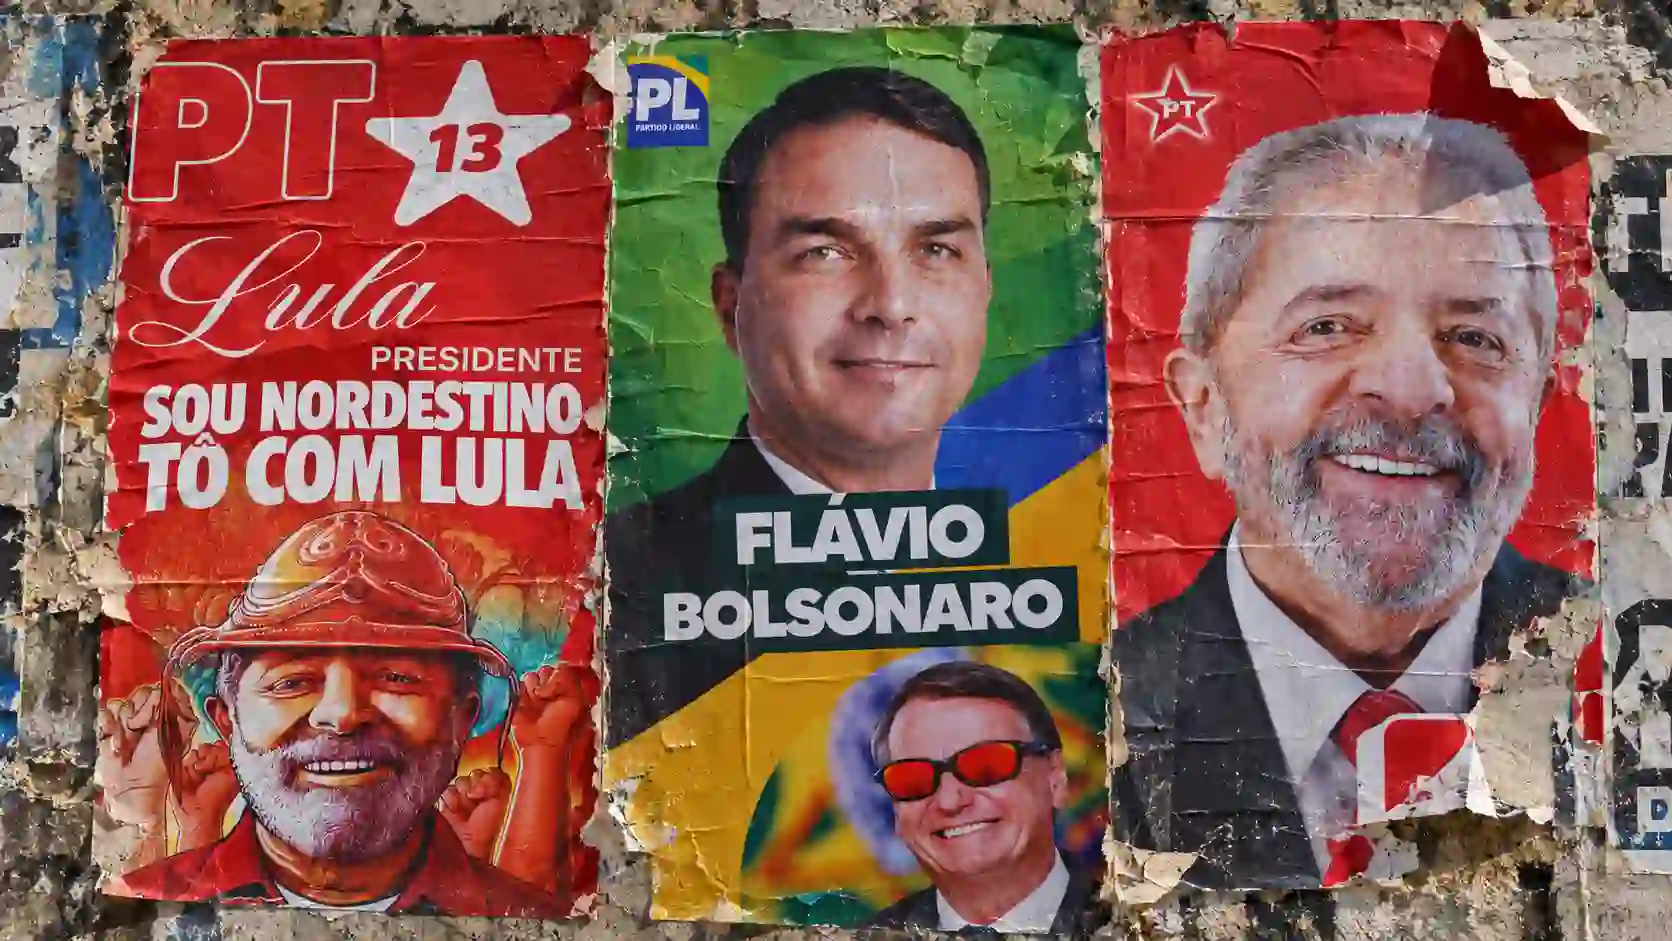
In the first round on 4 October 2026, Flávio Bolsonaro (PL) received 47.03% of valid votes and Luiz Inácio Lula da Silva (PT) 45.16%, according to the TSE with 99.99% of ballot boxes counted. Neither reached a majority; the two will meet in a runoff on 25 October. This analysis therefore examines the economic questions around the transition without assuming a final presidential result.
A new mandate can change priorities, ministerial responsibilities and the balance between concessions, public banks, budget funding and state-owned enterprises. Those choices affect the route through which capital reaches infrastructure and industry. They also influence which projects are prepared first and which public objectives are written into their design.
However, investors encounter a project rather than a national programme. A road concession needs a viable traffic and revenue model; a power project needs a connection and customers; a factory needs demand and operating competitiveness. The political direction matters most where it changes one of these practical conditions.
Where can public policy remove a constraint that private investment cannot resolve alone—and where does public support merely accompany a project that would have proceeded anyway?
Brazil Enters the Election With an Investment Gap
BNDES’s analysis of second-quarter 2026 national accounts reports an investment rate of 16.1% of GDP, compared with 16.6% in the same quarter of 2025. Gross fixed capital formation nevertheless rose 1.2% from the previous quarter. These measures describe different things: a quarterly improvement in investment does not necessarily raise its share of the economy.
The industrial perspective adds another layer. A CNI/Nexus survey published in June 2026, covering 1,003 executives between 7 May and 5 June, found that 41% intended to maintain investment over the following four years and 28% intended to increase it. A further 9% intended to reduce investment, while 20% planned no investment during that period. Tax reduction and fiscal balance featured prominently among their priorities for the next government.
That evidence suggests a useful distinction between willingness to invest and willingness to expand. A company may continue replacing machinery or improving efficiency while postponing a new plant. The resulting demand for equipment, engineering and services can be substantial without indicating a broad capacity boom.
Transport Reveals an Area of Overlap
Agência iNFRA’s comparison of the presidential programmes, published on 19 August 2026, identifies continuity in the use of private partnerships for transport infrastructure. That is a sector-specific observation, rather than evidence that the candidates’ wider economic policies are equivalent.
Flávio Bolsonaro’s programme proposes R$900 billion in transport investment over four years and emphasises concessions, PPPs and financing backed by federal assets. This is a campaign target, not committed or disbursed investment.
According to iNFRA’s reading of Lula’s programme, the agenda includes continued road concessions, railway auctions and contract restructuring, alongside port leases and access-channel concessions. It places these within a wider framework of public coordination and industrial development. iNFRA identifies the same implementation gap in both programmes: neither sets out in depth how the proposals would be executed or where the required resources would come from.
The investment question is therefore more precise than choosing between public and private participation. It concerns how much responsibility the state retains, which obligations operators assume and whether the financing model survives the actual cost of delivering the asset.
The Pipeline Is Larger Than the Set of Investable Projects
Private capital already occupies a central place in Brazil’s infrastructure model. ABDIB’s Livro Azul da Infraestrutura 2025 projected R$234.9 billion in private infrastructure investment for 2025, out of R$280 billion overall—approximately 84% of the total. The publication labels the 2025 figures as projections. They illustrate the expected weight of private participation, rather than establishing a verified final annual outturn.
Casa Civil’s Novo PAC transparency page lists a planned programme of roughly R$1.9 trillion, including R$765 billion in private financing. Its funding categories also include federal budget resources, state-owned enterprises and financing. The programme spans several years, including a period beyond 2026; these figures cannot be treated as expenditure already executed or as a single annual investment flow.
This mixed structure illustrates why a public investment programme is also a map of relationships. Some projects depend on budget allocations, others on regulated revenues or private demand. A large pipeline can contain mature concessions alongside projects still missing permits, procurement decisions or a viable funding model.
| Stage | What it establishes | What still needs verification |
|---|---|---|
| Political priority | A problem or sector receives attention. | Responsible institution, legal instruments and budget capacity. |
| Prepared project | A location, scope and delivery model take shape. | Permits, demand assumptions and procurement readiness. |
| Financed project | Capital and contractual commitments support execution. | Conditions precedent, cost exposure and implementation schedule. |
| Operating asset | The investment begins delivering a service. | Reliability, actual usage and its effect on the surrounding economy. |
These stages should remain separate when assessing Brazil after the vote. An announced auction is a different signal from an awarded contract, and an awarded contract is a different signal from financial close. Changes in the pipeline matter when they move projects through these stages.
Three Places Where Public Priorities Meet Private Economics
Public objectives include connectivity and lower transport costs. Private operators need revenues and manageable construction and operating obligations. The overlap is strongest where a corridor connects identifiable economic activity.
Generation, transmission and industrial demand must fit together. An incentive can improve project economics, but it does not establish that power, connections and customers are available at the required location.
Policy can support technology and competitiveness. Companies still decide whether to modernise existing capacity or expand production. Those choices create different markets for machinery and specialised services.
The spatial dimension is essential. A transport improvement can strengthen one export corridor while doing little for a factory elsewhere. Energy capacity becomes commercially relevant through the network and the user it serves. Brazil’s national scale makes a sector-and-location reading more useful than a single narrative of investment confidence.
Econosur’s analysis of REDATA and data-centre constraints and Eco Invest’s climate-finance model explores related interfaces. The wider logistics and waterways framework helps place transport projects within regional production and trade systems.
What to Watch Before and After the Runoff
The first useful signals will be those that connect political intentions to decisions institutions and companies can act on. The first-round result establishes the runoff, while the final vote will determine the presidential mandate. Subsequent appointments, budgets and project milestones will show how that mandate is translated into the economy.
- Congress: the composition of the new Chamber and Senate, which shapes the legislative room for any agenda.
- Institutional responsibility: who controls the relevant programme, regulator, financing instrument and project preparation?
- Funding: is support a proposal, an authorised allocation, a financing agreement or a disbursement?
- Project movement: which schemes advance into procurement, contracts, financial close or construction?
- Company behaviour: do announced plans become purchases, capacity additions or operating changes?
- Local bottlenecks: can the site access energy, transport, permits and the capabilities required to operate?
A market reaction can reveal expectations, but it cannot answer these project-level questions. Nor should a pre-election investment forecast be presented as evidence of a post-election acceleration. The strongest assessment combines the political transition with changes observable in the real investment process.
My reading is that Brazil’s investment story will be shaped by the quality of the connection between national objectives and project economics. The election can change that connection, but its importance will differ by sector and location.
A port, a transmission line and a modernised factory may all appear in an investment narrative, yet they depend on different institutions, revenues and operating conditions. Treating them as one wave of capital obscures where the actual constraints lie.
The more revealing question is what each investment enables around it. Does a corridor change the economics of an export region? Does additional grid capacity allow industrial demand to develop? Does public finance bring a viable project forward, or leave a structural weakness unresolved?
For Econosur, the election is an entry point into that analysis. The objective is to understand how decisions in Brasília reach companies, infrastructure and production systems—and where the connection remains incomplete.
Research Services for Brazil’s Investment Economy
Econosur can examine a defined investment question through its sector, company, institutional and regional context.
Distinguish announced projects from prepared, contracted, financed and operating assets; identify missing evidence and the next decision points.
Examine how transport, energy or industrial investment relates to production, demand and geographic constraints.
Investigate relevant operators, industrial companies and competitive structures within a defined market.
Map the institutions, financing instruments and commercial conditions that determine how a priority becomes a project.
For a specific question, see Custom Market Analysis South America. Broader frameworks are available through Brazil Country Reports, Sector Briefs and Company Reports.
Election: The presidential contest proceeds to a runoff on 25 October 2026. This analysis does not assert a winner or a final governing arrangement.
Investment: campaign targets and programme envelopes are plans. ABDIB’s 2025 figures cited here are projections from its 2025 publication, not final realised investment. They are distinct from financing commitments, executed spending and operating assets.
Scope: the CNI survey covers industrial executives; it does not measure all private investment. BNDES’s national-accounts commentary and Novo PAC’s programme figures use different definitions and periods and should not be combined into a single total.
Interpretation: the project-stage framework and economic implications are Econosur’s analytical reading, rather than reported election outcomes or forecasts of guaranteed investment.
Primary, Institutional and Secondary Sources
- TSE — Flávio Bolsonaro and Lula advance to the presidential runoff, 5 October 2026: official first-round percentages at 99.99% of ballot boxes counted and confirmation of the second round.
- TSE — 2026 electoral calendar: official first-round and possible runoff dates.
- CNI / Nexus — Industrial priorities for the next government, 22 June 2026: original survey of industrial executives, fieldwork in May–June.
- Casa Civil — Novo PAC transparency: programme investment envelope and financing categories.
- Casa Civil — Sources of Novo PAC financing: definitions of the programme’s funding channels.
- Flávio Bolsonaro — Government programme 2027–2030, PDF pp. 50–51: campaign proposals; document hosted by Agência iNFRA.
- Lula — Government programme: campaign document hosted by Agência iNFRA; its transport proposals are discussed in the programme-comparison section of this article.
- ABDIB — Livro Azul da Infraestrutura 2025, infrastructure investment chart: the 2025 column is marked as a projection; private and total investment are expressed in constant 2025 reais.
- BNDES — Comments on GDP in Q2 2026: institutional analysis of national-accounts data; used for the investment rate and quarterly fixed-capital formation.
- Agência iNFRA — Transport proposals in Lula’s and Flávio’s programmes, 19 August 2026: specialist reporting comparing transport agendas and implementation gaps.
Investigate a Specific Brazilian Investment Question
Define the sector, project or company decision. Econosur can structure the research around the evidence needed to assess it.
Discuss your research questionFrequently Asked Questions
Does Brazil’s election decide which projects receive investment?
It influences policy priorities, appointments and the use of public instruments. Individual projects still depend on financing, contracts, demand, permits and implementation. An electoral commitment alone does not establish that a project will proceed.
Do public priorities and private investment point in the same direction?
They can overlap in transport, energy and industrial development, but the overlap depends on project economics. A socially important project may require support that a commercially viable concession does not. The allocation of costs and risks determines whether the partnership works.
Why does the runoff matter for investment analysis?
The first round on 4 October 2026 produced no majority. Flávio Bolsonaro (47.03%) and Lula (45.16%) will contest a runoff on 25 October. Until then, both policy directions remain possible; project conditions and pipeline progress are the more reliable indicators.
How can Econosur research a specific Brazilian investment question?
The scope can combine a project pipeline, sector structure, relevant companies, financing mechanisms and the evidence behind stated opportunities. The deliverable should answer a defined business question and distinguish confirmed information from assumptions and unresolved points.
About the platform
Econosur
Analysis of South American markets, companies, projects and the economic systems connecting them.