Chile Seaweed Industry:
Raw Material,
Processing
and Value
Chile’s seaweed industry links coastal resources, Atacama drying conditions, China-led export demand, domestic hydrocolloid processing and a new cultivation push. The market question is how much value Chile can capture beyond dried raw material while reducing pressure on wild stocks.
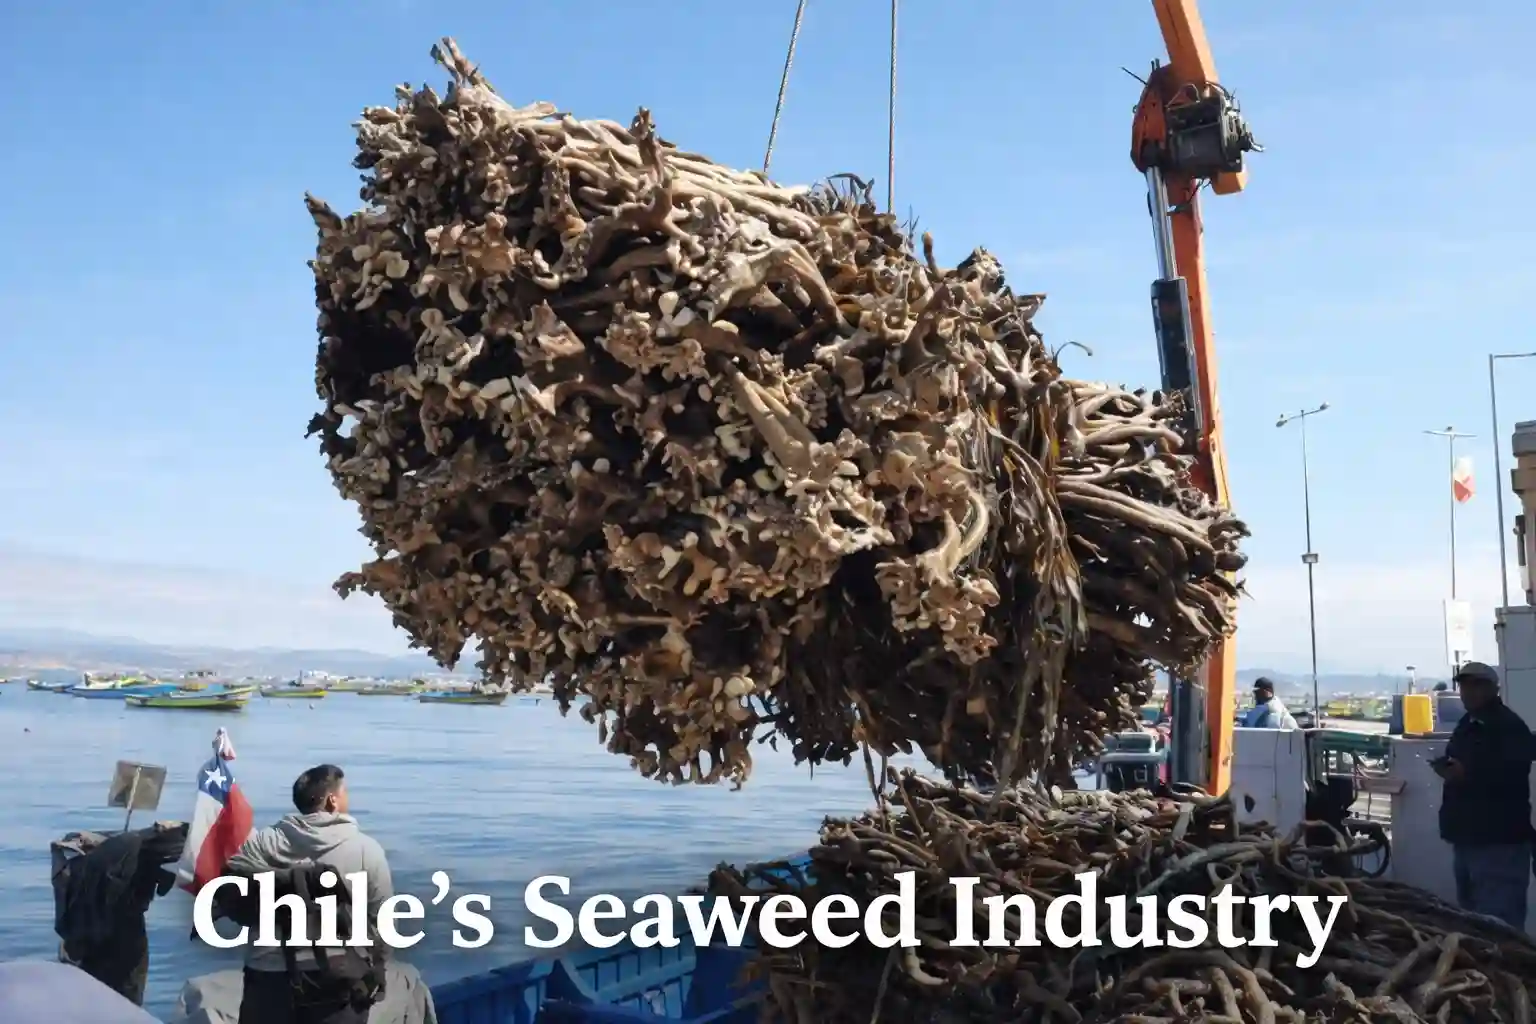
Chile has a structural role in the global seaweed market because coastal geography, wild brown algae resources and low-energy drying conditions combine into a real cost advantage. This makes the sector useful for reading how natural resources become export markets in the wider Chile market context.
The Chilean seaweed industry forces two market questions at the same time. First, how can geography create a cost advantage? Second, how much value can a raw-material leader capture when higher-value extraction and processing are still concentrated elsewhere?
Market reading: Chile’s seaweed industry is a resource, logistics, processing and cultivation case. The core issue is value capture: Chile has coastal supply, Atacama drying and export demand, but the next stage depends on combining sustainable feedstock, traceability and more downstream processing.
September 2026 update: raw-material leadership, processing and a second supply model
The latest official processing data sharpen the picture. SERNAPESCA reports that 663 processing plants operated in Chile in 2025, including 195 plants dedicated exclusively to dried seaweed. The Nature Conservancy’s sector overview still provides the broader 2024 scale estimate: more than 428,000 tonnes of seaweed production, an industry value of roughly USD 100 million and around 75,000 people linked to the sector.
The strategic question is no longer only downstream processing. Chile is also trying to expand macroalgae cultivation alongside wild harvesting. In 2026, public programs, aquaculture rules and new work on integrated multitrophic aquaculture all point toward a second supply model that could support resource recovery, more stable feedstock and higher-value processing.
The drying step that costs other seaweed producers energy is handled in northern Chile by geography. That is a cost structure, not a slogan.
Market Leadership Through Structural Advantage
Chile has been the world’s largest wild harvester of seaweed since 2015. The country’s coastline, especially the northern and central zones with commercially relevant brown algae, gives it a natural position in the global seaweed and alginate chain.
The leadership is structural. Chile’s coastline provides the biological resource. The Atacama climate provides a low-energy drying environment. Long-standing coastal collection practices provide labor and local knowledge. International demand provides the pull.
That combination gives Chile a real competitive position. It also creates a policy and investment problem: the same system that makes dried seaweed exports efficient can keep the country locked into the lower-value part of the chain.
When Sustainability Becomes Cost Structure
Chile’s dominance in wild seaweed rests on a mechanism that rarely appears in investor materials: geography as a cost factor. The kelp beds along the Chilean coast sit close to one of the world’s driest desert environments. In northern Chile, where much of the commercially relevant brown algae is harvested, seaweed can be dried in the open air using desert conditions.
Industry operators, including Japanese alginate manufacturer KIMICA, have described this drying logic directly. The Atacama climate reduces the energy cost of a step that other producers must solve with powered dryers, heated facilities or longer processing cycles.
This matters because alginate — the primary industrial product extracted from brown kelp species such as Lessonia nigrescens and Lessonia trabeculata — is a globally traded input used in food, pharmaceuticals, cosmetics and textiles. A lower-cost dried raw material base matters in every downstream market where price, quality and reliability decide sourcing. This places the sector close to the broader agriculture and food systems discussion, even though seaweed sits outside classic land-based agriculture.
Market analysis point: Chile’s sustainability advantage is an input-cost advantage created by coastal ecology and desert climate. That is why the case belongs in market analysis, resource strategy and value-chain assessment.
One Dominant Buyer, One Structural Signal
Global demand for seaweed — across food, pharmaceuticals, cosmetics, alginate manufacturing, agriculture and bio-based materials — continues to rise across major import regions. Chile is positioned to supply that demand at scale.
The current trade flow, however, is highly concentrated. SUBPESCA identifies China as the principal export market for brown-seaweed resources such as huiro negro and huiro palo, followed by Japan, Norway and France. The same official resource pages state that more than 90% of reported landings are marketed as dried chopped seaweed, while the remainder feeds domestic extraction into products such as alginic acid and alginate.
That is the clearest primary-source evidence for the value-chain issue. A dominant buyer creates predictable volume, but it can also weaken supplier pricing power when most of the product leaves Chile before higher-value extraction. The same buyer-concentration logic appears in other Chilean resource markets, including the Chile-China connection around copper and lithium.
The Investment Gap: Where the Value Chain Ends
This is the relevant tension in the Chilean seaweed market. The country is an undisputed leader in raw material production, but downstream value capture remains smaller than that resource position would suggest.
Chile does have domestic hydrocolloid processing capacity. Gelymar, for example, converts seaweed inputs into carrageenan, alginate and formulated hydrocolloid systems for international B2B markets. The point is therefore not that Chile lacks processing altogether. It is that the scale of extraction, formulation and higher-value intermediate production remains limited relative to the amount of raw material harvested and exported.
The gap between what Chile produces and what it captures in value per tonne is therefore a function of processing capacity, extraction infrastructure, technical know-how, buyer relationships, traceability and investment risk.
| Layer | Chile’s current position | Strategic question |
|---|---|---|
| Wild harvest | Global leader with large coastal resource base and established collection practices. | Can harvest remain sustainable under stock and quota pressure? |
| Drying | Strong natural cost advantage through Atacama climate and coastal drying infrastructure. | Can drying quality, traceability and grading be upgraded? |
| Processing | Still thinner than raw-material position suggests. | Can Chile capture more value through extraction and intermediate products? |
| Export markets | Heavy dependence on dominant buyers, especially China. | Can buyer concentration be reduced without losing volume? |
For investors who look at structural gaps rather than sector labels, this is the relevant question: where in the seaweed value chain does infrastructure investment create the strongest return — drying quality, grading, extraction, traceability, logistics or buyer diversification?
Cultivation: a second supply model is moving closer to policy
Wild harvesting still dominates Chile’s seaweed economy, but cultivation is becoming more important in public policy. In 2026, INDESPA approved another national algae-cultivation support program, with up to CLP 254 million allocated in the program rules. By June, the institute had already published the selected applications for that year’s round.
Regulation is also adapting. SUBPESCA Resolution 1102/2026 created a procedure for aquaculture concession holders that incorporate macroalgae cultivation, requiring them to declare authorized production for the main culture and projected macroalgae output. In August 2026, SUBPESCA and Chilean universities were also developing tools for integrated multitrophic aquaculture in benthic-resource management areas.
This matters economically because cultivation addresses a different problem from downstream processing. Processing determines how much value Chile captures from each tonne. Cultivation determines whether the country can build a more stable and scalable raw-material base while reducing pressure on wild stocks.
Marcus A. Volz perspective: Chile’s seaweed bottleneck is no longer simply a lack of downstream processing. The more important question is whether the country can build a second supply model alongside wild harvesting: cultivated macroalgae linked to processing, traceability and industrial buyers. If that succeeds, Chile could reduce resource risk while capturing more value domestically. If it does not, its structural advantage may remain concentrated in low-cost collection and drying.
What This Means for Capital Allocation
The lesson from the Chilean seaweed market is specific: commodities based on natural regeneration and low-input processing can have different risk profiles from commodities dependent on intensive production.
Chile’s advantage lies in lower drying energy exposure, fewer agricultural inputs and strong coastal production knowledge. Those advantages create the base. Processing leadership requires a second layer of capital: extraction plants, quality systems, traceability, certification, buyer development and access to higher-value end markets.
Moving further downstream also changes the economics. Natural drying exploits an existing geographic advantage with relatively low energy input. Cultivation, extraction and hydrocolloid processing require more technical capability, infrastructure, working capital and market development. The value-capture opportunity is therefore real, but it is more capital- and execution-intensive than the raw-material model.
That is why the Chilean seaweed industry is a blue-economy case with a hard commercial center. The investment question is which part of the Chilean seaweed chain can capture more value while preserving the natural base that creates the advantage.
Resource Risk: The Advantage Is Real, But Not Unconditional
The Chilean seaweed advantage depends on the natural stock. That makes management, quotas, enforcement and restoration central to the market’s durability. Wild harvest can be cost-efficient, but it is finite.
Stock pressure, illegal extraction and overharvesting in some areas are market risks. If the natural base weakens, Chile’s low-cost position also weakens. The 2026 cultivation push does not remove that risk, but it can diversify supply if cultivation scales alongside better enforcement, resource management and traceability.
This is the central tension: Chile’s seaweed industry has a structural advantage because nature does part of the work. That advantage remains durable when the industry invests in regeneration, enforcement, cultivation, traceability and value-chain development.
For companies, analysts or institutions evaluating blue-economy opportunities in South America, this type of question belongs in a structured sector brief or custom market analysis.
Need a sector brief on Chile’s blue economy or seaweed value chain?
Econosur prepares short sector briefs and custom analysis for companies, analysts and institutions evaluating South American resources, blue-economy sectors, coastal value chains and market questions.
Possible scopes include Chilean seaweed, alginate, dried algae exports, China buyer concentration, processing infrastructure, aquaculture, traceability, coastal resource management or value-chain upgrading.
Request a Sector BriefFrequently asked questions
Why is Chile important in the global seaweed industry?
Chile is important because it is one of the world’s leading wild seaweed harvesters. Its coastal geography, brown algae resources and low-energy drying conditions give it a structural role in the global seaweed and alginate value chain.
What is the main competitive advantage of Chile’s seaweed industry?
The main advantage is cost structure: northern Chile’s coastal geography and Atacama climate allow large volumes of seaweed to be dried with very low energy input.
What is the value chain gap in Chilean seaweed?
Chile exports large volumes of dried seaweed, while much of the higher-value extraction and processing into alginate, agar or carrageenan takes place elsewhere. The gap is between raw material leadership and downstream processing capacity.
Why does China matter for Chilean seaweed exports?
China is a dominant buyer of Chilean dried seaweed and a major processing hub. This creates stable demand, buyer concentration and limits Chile’s ability to capture more value per tonne.
Can seaweed cultivation reduce pressure on wild harvest in Chile?
Cultivation can diversify Chile’s seaweed supply and reduce pressure on wild stocks, although it is still a small part of national production. Public programs and regulatory changes in 2026 are intended to expand macroalgae cultivation alongside continued wild-harvest management.
Is Chile’s seaweed industry mainly a sustainability story?
Chile’s seaweed industry is a sustainability, cost-structure and value-chain story at the same time. Geography lowers drying costs, wild harvest creates scale and the missing processing layer defines the investment gap.