Paraguay · Mercosur · Itaipú · Tax System · Soy · Waterways
Paraguay's Role in Mercosur: The Logic of the Periphery
Paraguay is a smaller, landlocked member of Mercosur. Its agricultural exports, hydropower and manufacturing platforms connect it closely to larger neighbours. Understanding those functions reveals more about the bloc’s architecture than GDP size alone.
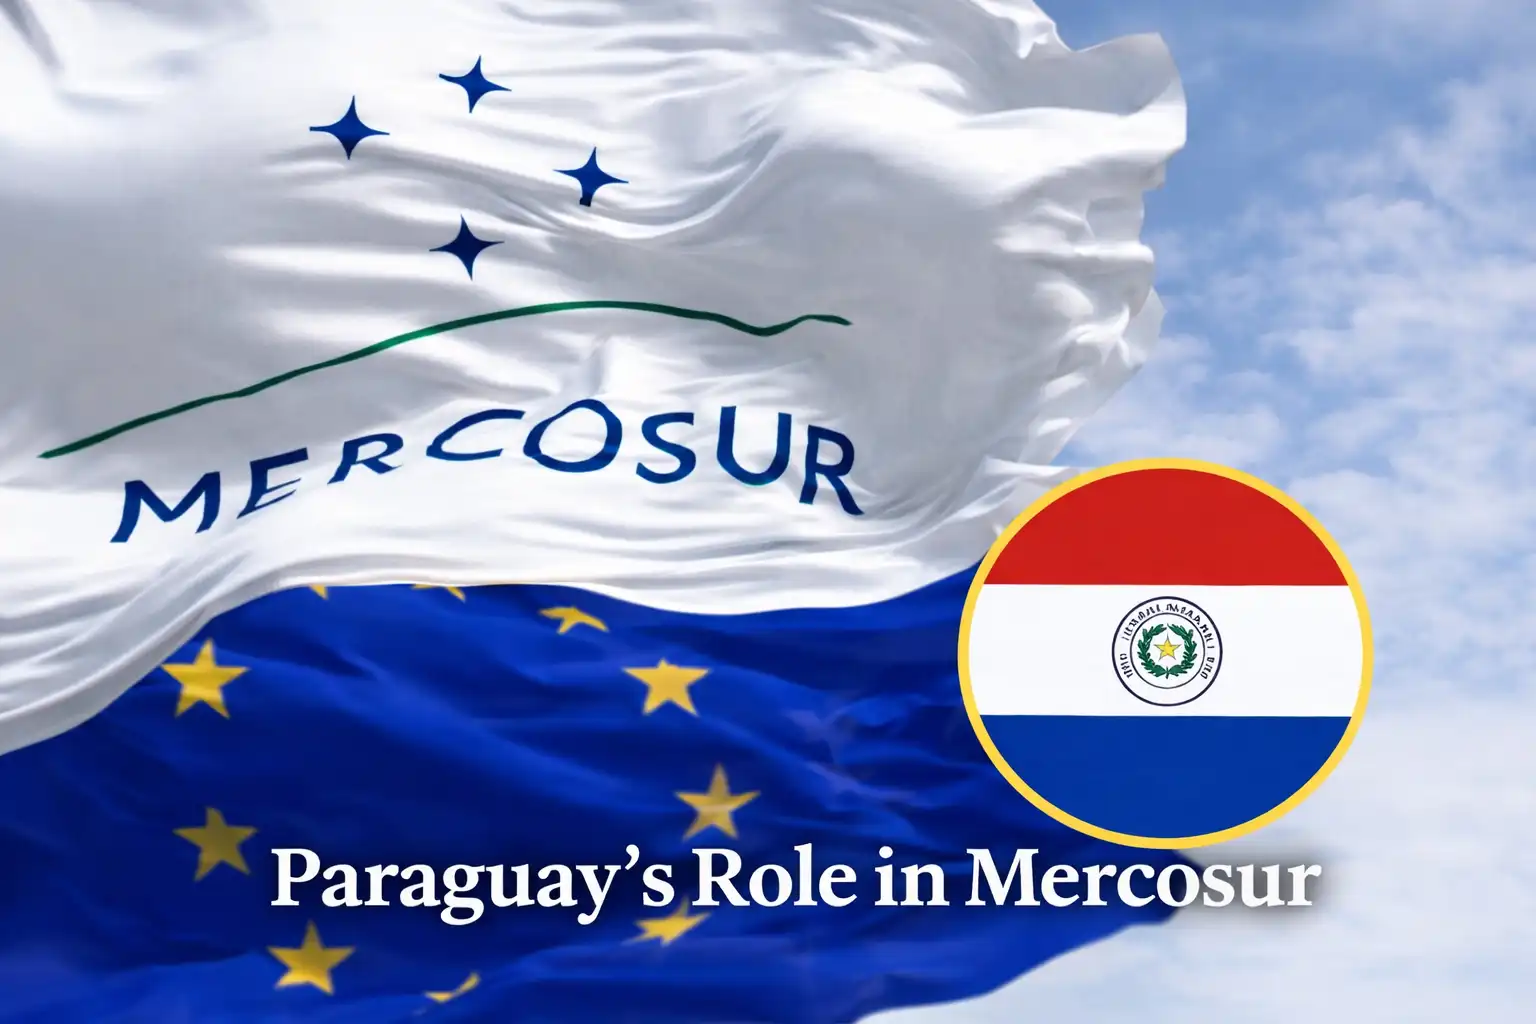
Paraguay matters in Mercosur through its complementary roles in agriculture, energy, manufacturing and logistics.
It is an agricultural export platform, a net energy exporter tied to Itaipú, a low-tax operating base and a waterway-linked logistics node. Its value is not market size. Its value is structural position inside the regional system.
For broader context, see the Paraguay market profile, Paraguay market insights and Econosur’s Southern Cone market structures.
Core market reading:
Paraguay is not a small version of Brazil or Argentina. It is a differently structured economy that uses scale, tax position, energy surplus and river access to perform a distinct role inside Mercosur.
Anyone trying to understand Mercosur usually looks at Brazil or Argentina. That is understandable — both countries dominate the bloc economically, politically, and in the financial press. But anyone trying to read markets seriously looks at the edges. And the most analytically interesting edge of Mercosur is Paraguay.
Paraguay’s relevance is not explained by economic scale alone. Agricultural exports, hydropower, maquila production and river logistics give it distinct roles within Mercosur. These are complementary regional functions, not capabilities that other members are categorically unable to replicate.
This is the same regional logic behind Econosur’s coverage of the Paraguay river economy, the Paraná-Paraguay Waterway and South American logistics and waterways.
Three Structural Functions Inside Mercosur
Paraguay performs three structural roles in the Mercosur system that are rarely analysed together.
The first is as an agricultural export platform. Soybeans, soy oil and soy meal remain central to its registered exports. The BCP’s January–September 2026 report identifies these products as the main drivers of registered-export growth, showing how agricultural production connects Paraguay to processing, river logistics and international buyers.
The export channel runs through the Paraguay-Paraná waterway directly to Atlantic terminals — not through São Paulo or Buenos Aires, but past them. This is not a workaround. It is a distinct export corridor that positions Paraguay inside global commodity flows while remaining structurally separate from its neighbours' agricultural bureaucracies and tax regimes.
The second is as a net energy exporter with structurally guaranteed offtake. Itaipú Binacional, the hydroelectric dam co-managed with Brazil, is one of the largest power plants on earth. It supplies 78 percent of Paraguay's domestic electricity consumption — and Paraguay still uses less than half of its 50 percent treaty entitlement. The surplus is sold to Brazil.
Itaipú transfers include royalties, compensation for ceded energy and payments to ANDE. The institution reported USD 36 million transferred to Paraguay in January 2026. These flows should be distinguished from industrial power tariffs and from the electricity reliably available to a particular factory.
The third function is as an operating platform within the bloc. The 10% general IRE business-income rate is one part of that location proposition. Manufacturing incentives, administrative capability, cross-border logistics and actual customer access must be evaluated together.
DNIT lists a 10% rate for the general and SIMPLE business-income regimes (IRE). That headline rate does not establish the total tax cost of a holding, trading or investment structure. Source rules, distributions, non-resident payments and the relevant operating regime require separate assessment; this article does not claim blanket exemptions for foreign income or capital gains.
The operating case must therefore be assessed at the level of the proposed activity and legal entity. Tax rates alone do not establish access to Mercosur customers, and different tax bases cannot be compared as though they represented an identical effective burden.
The Itaipú Question — More Complex Than It Looks
The energy export model is currently in transition. Itaipú's construction debt was fully paid off in 2023, after which Paraguay and Brazil entered renegotiations of Annex C of the 1973 treaty — the instrument governing energy tariffs, royalties, and profit distribution.
The May 2024 agreement set the Itaipú tariff at USD 19.28 per kilowatt-month for 2024–2026. The tariff agreement and the revision of Annex C are distinct processes. The diplomatic interruption associated with the espionage dispute occurred in April 2025, not April 2024. A final revised Annex C should only be treated as effective when supported by the published bilateral instrument.
The core Paraguayan demand — the right to sell its surplus energy freely on Brazil's competitive market rather than at fixed cost-of-service rates — has not been fully conceded.
"Itaipú transfers more than USD 500 million per year to the Paraguayan state regardless of what happens in Buenos Aires or São Paulo. That structural independence from regional business cycles is not an accident. It is an asset."
The significance of this dispute is not purely financial. It is structural: if Paraguay secures the right to sell surplus energy at market prices, it gains a new degree of leverage over Brazil that goes beyond the dam itself.
Debt repayment and the revision of Annex C affect the distribution of costs, revenues and future bargaining options. Expected additional receipts should not be treated as realized income or as a factory-level electricity-price guarantee.
For the manufacturing application, see the Paraguay auto-parts maquila corridor and its connection to the South American automotive industry.
How to Read the Market
Paraguay cannot be read with the same instruments used for Brazil or Argentina. Purchasing power indexes, consumer demand growth, and industrial production metrics capture a small, incomplete picture of what Paraguay actually does economically. The more useful questions are structural.
The first: how does Paraguay behave during regional crises? The historical record since 2003 is consistent — Paraguay maintained positive growth rates through the periods of sharpest regional stress, including Brazil's deep recession of 2015-2016 and multiple Argentine currency crises, partly because its revenue base — agricultural export volumes and Itaipú transfers — is less correlated with Argentinian or Brazilian demand cycles than most regional economies.
The correlation is not zero: a severe Argentine collapse affects cross-border commerce. But the decoupling is real enough to be analytically significant.
The second: who makes economic decisions, and by what logic? Paraguay scored 24 out of 100 on Transparency International's 2024 Corruption Perceptions Index — ranking 149th out of 180 countries, well below the global average of 43 and the Latin American average of 42. The IMF's 2024 Article IV consultation explicitly calls for Paraguay to "strengthen the anti-corruption framework, governance, and transparency."
The US government imposed Magnitsky Act sanctions on former President Cartes in 2022-2023 for involvement in transnational crime — sanctions lifted only in late 2025. These are not abstractions. They reflect a governance environment in which the gap between formal legal frameworks and actual enforcement is a real operating risk for investors, requiring on-the-ground knowledge and direct relationships that nominally more transparent markets do not demand.
The third question is sectoral: which industries are growing structurally, independent of political cycles?
The answer points consistently toward logistics infrastructure along the waterways, precision agriculture technology and inputs, energy-intensive industry attracted by cheap hydroelectric power, and financial services for the regional Mercosur market. None of these is glamorous. All are structurally anchored.
Paraguay’s logistics role is inseparable from the Paraná-Paraguay Waterway and the Paraguay river economy.
For the country-level view, see the Paraguay market profile and Paraguay market insights.
The Tension the Bloc Does Not Discuss
There is a structural tension in Mercosur that is rarely discussed openly. The bloc was designed to reduce trade barriers between large economies and to harmonise regulatory frameworks toward common standards. Paraguay has accepted that architecture — and in parallel built a competitive position that partly contradicts its goals.
A 10% IRE rate and Paraguay’s distinct operating framework can influence location decisions. The commercial question is whether a proposed structure has the customers, substance, logistics, skills and compliance required to work across borders.
This asymmetry creates a continuing regional policy tension. A smaller economy can compete through location advantages, while larger markets anchor demand, engineering and purchasing authority. That relationship is a market-structure interpretation, not a prediction that tax policy will remain unchanged.
That is the reading that the periphery enables. Paraguay is not a small version of its neighbours. It is a differently structured economy that performs functions within the regional system that scale makes unavailable to larger actors.
Understanding those functions — and their limits — is what the Econosur perspective on the Southern Cone actually requires.
Paraguay should be evaluated by function, not by size alone.
The useful questions are whether a company needs logistics access, energy exposure, agricultural scale, tax-efficient regional structuring, Asunción-based administration or a lower-cost Mercosur platform.
Business Opportunities, Location Advantage and Market Verification
Which sectors offer the strongest structural business opportunities in Paraguay within Mercosur?
The strongest opportunity fields identified in this analysis are waterway and logistics infrastructure, precision-agriculture technology and inputs, selected energy-intensive industry supported by hydropower, and regional business and financial services. These are structural opportunity areas rather than proof of open tenders, active purchasing programs or immediately addressable demand.
When does Paraguay offer a strategic advantage as a Mercosur operating base?
Paraguay becomes strategically relevant when a company benefits from waterway access, agricultural export systems, hydropower, lower-cost regional operations, selected tax and administrative structures, or production and service links to larger Mercosur markets. The advantage is business-model specific: a low statutory tax rate or cheap electricity does not by itself establish a viable operating case.
What should international companies verify before using Paraguay as a Mercosur market-entry or operating platform?
Companies should verify the real target-sector demand, relevant buyers and competitors, procurement locations, applicable tax and customs treatment, Mercosur rules of origin, logistics and energy conditions, local partner and service requirements, regulatory practice and whether formal advantages translate into workable commercial access for the specific product or service.
What public market data does not show
Public sources can describe tax rates, trade rules, export flows, Itaipú arrangements, infrastructure and company announcements. They do not reliably show current buyer priorities, live procurement demand, incumbent supplier relationships, supplier-qualification routes, commercial terms, local service expectations, distributor quality or whether a formally attractive market structure is genuinely accessible to a specific foreign company.
That gap is where primary research and commercial verification become necessary.
Itaipú is not only an energy asset. It is a bargaining structure.
Paraguay’s surplus electricity gives the country a form of regional leverage that is not visible when the country is read only through GDP size, consumer demand or industrial output.
Research Services for Paraguay and Mercosur
Econosur can investigate a defined company, sector, project or market question within its South American operating context.
Test industrial demand, energy requirements and river-logistics assumptions with relevant market participants.
Map maquila operators, exporters, service providers and competing location models.
Verify local partners, technical capabilities, market presence and customer fit.
Check operating constraints, decision locations, customs interfaces and the evidence behind a Paraguay investment case.
For a defined research question, see Custom Market Analysis South America.
Published company and project information establishes the public evidence base. Announced investment, approved capacity, construction, operating output and active procurement are separate stages. Purchasing contacts, current requirements and commercial terms require direct verification.
Primary, Institutional and Secondary Sources
- BCP — September 2026 trade report
- DNIT — IRE rates and obligations
- MIC — current maquila law and implementing rules
- MIC — 2024–2026 Itaipú tariff agreement
- Itaipú — January 2026 Annex C transfers
Official statistics, regulatory documents, company disclosures and independent reporting serve different purposes. Company targets and sponsor proposals are attributed as such. Data periods are stated beside the relevant claims; historical figures are not presented as October 2026 measurements.
From structural positioning to commercial verification
Paraguay’s role in Mercosur is not explained by GDP size alone. Its commercial relevance depends on how energy, agribusiness, waterways, taxation, manufacturing and regional decision structures interact for a specific company.
Econosur combines public-source analysis with primary interviews, company and competitor research, supplier and distributor checks, buyer and procurement research, project verification, industry-event research and targeted field work where required.
Explore custom market analysisFAQ
Why does Paraguay matter inside Mercosur?
Paraguay matters because it performs complementary functions inside Mercosur: agricultural export platform, net energy exporter, low-tax operating base and waterway-linked logistics node.
Why is Paraguay described as a peripheral economy?
Paraguay is peripheral in scale, but not irrelevant. Its smaller economy allows it to operate with a different tax, energy and logistics logic than Brazil or Argentina.
Why is Itaipú important for Paraguay’s market structure?
Itaipú gives Paraguay a structural energy-export position and a recurring revenue base that is less dependent on regional business cycles than many other sources of income.
What does Paraguay reveal about Mercosur?
Paraguay reveals that Mercosur is not only a bloc of large economies. It is also a system of asymmetries in which smaller members can create competitive roles around tax, energy, agriculture and logistics.
Which sectors offer the strongest structural business opportunities in Paraguay within Mercosur?
The strongest structural opportunity fields identified in this analysis are waterway and logistics infrastructure, precision-agriculture technology and inputs, selected energy-intensive industry supported by hydropower, and regional business and financial services. These are opportunity fields, not evidence of open tenders or immediate purchasing demand.
When does Paraguay offer a strategic advantage as a Mercosur operating base?
Paraguay can offer a strategic advantage when a company benefits from waterway logistics, agricultural export systems, hydropower, lower-cost regional operations, selected tax and administrative structures, or production and service links to larger Mercosur markets. The advantage should be tested against the company’s specific operating model.
What should international companies verify before using Paraguay as a Mercosur market-entry or operating platform?
Companies should verify target-sector demand, relevant buyers and competitors, procurement locations, applicable tax and customs treatment, Mercosur rules of origin, logistics and energy conditions, local partner and service requirements, regulatory practice and real commercial access.