Company Insight · Chile · Copper
Minera Tres Valles: Can a Copper Restart Deliver a Viable Business?
A planned restart at Papomono, an existing processing plant and purchases from independent miners underpin the investment case. Tres Valles’ history shows why ore performance, working capital and environmental compliance must be assessed together.
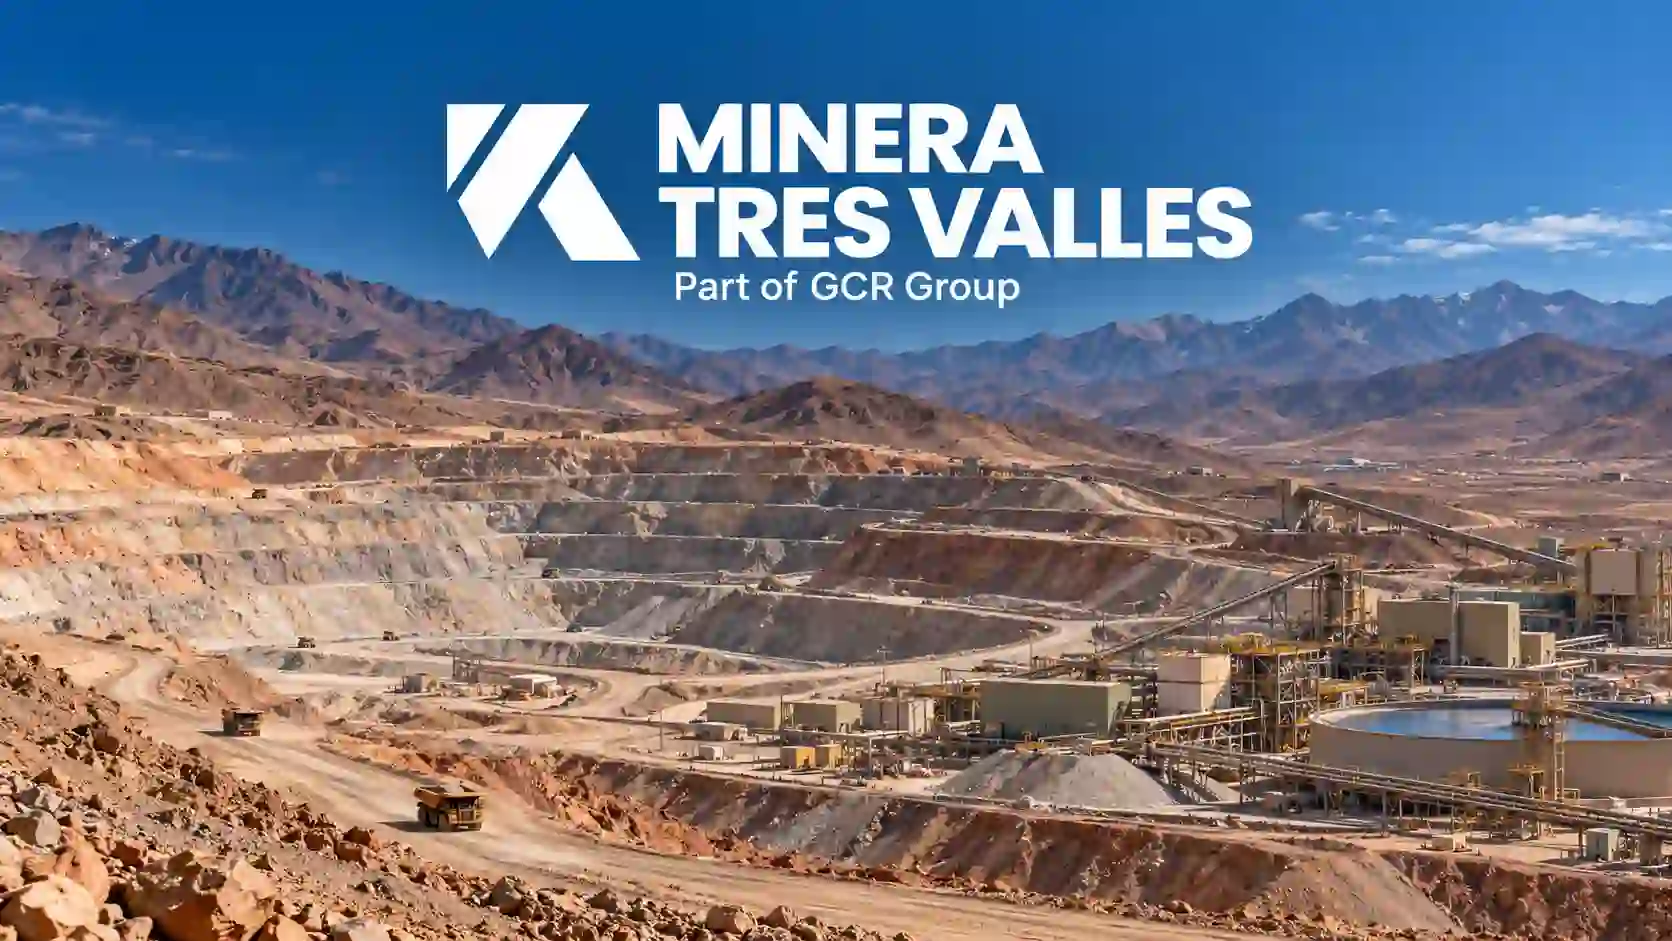
Tres Valles has a plausible route to a viable copper business, but its economics depend on more than restarting a mine. Its own ore, purchased feed and processing assets must work together at a cost and cash requirement the company can sustain.
Earlier difficulties connected weaker ore performance with a funding shortfall. The current operation therefore needs evidence of dependable feed, sufficient working capital, reliable payments and effective environmental management.
The available records support an assessment of these conditions. They do not yet establish sustainable profitability or a verified investment return.
Sources: [P1], [P2] and [P5]. Project parameters do not demonstrate achieved production or committed financing.
Company, Ownership and the Regional Ore Network
Compañía Minera Tres Valles SpA operates in Chile’s Coquimbo region. The environmental continuity project combines ore from the Papomono underground mine with purchased material, using existing facilities for heap leaching, solvent extraction and electrowinning. [P1]
Austrian investor Cevdet Caner acquired the business through NIU Invest in April 2025, according to La Tercera’s January 2026 interview. In that interview, Caner described the operation as a wholly owned subsidiary of US-registered Global Critical Resources, or GCR, formed to consolidate mining assets in Chile and Botswana. GCR’s own disclosures identify it as the parent company. [S2] [P2]
These accounts explain the progression from the acquisition vehicle to the stated group structure. They do not provide the complete transaction documents or a current shareholder register.
Commercially, Tres Valles combines mining with ore purchasing and processing. Its contribution to the regional economy depends partly on whether independent producers find it a reliable and competitive outlet for their material.
The case complements Econosur’s coverage of South American copper mining and Chile’s copper and lithium investment pipeline. It examines how an individual company converts assets and mineral supply into an operating business.
What Is Actually Restarting?
Reuters reported on October 16 that Papomono was targeting production by year-end 2026, while Tres Valles processed purchased ore. Don Gabriel was described as under maintenance, with a restart envisaged around 2030. [S1]
The restart discussion therefore concerns the integration of renewed underground supply with a processing and purchasing operation. Each component needs its own assessment of readiness, cost and output.
Progress needs to be measured through stable ore delivery, grade, dilution, recovery and delivered cost.
The purchasing model depends on suitable material, workable settlement terms and suppliers’ willingness to keep delivering.
The processing facilities provide a common destination for both. Their ability to combine different feed sources depends on mineral characteristics, treatment performance and operating constraints.
The Earlier Failure Connected Ore Performance and Liquidity
Three Valley Copper’s January 24, 2022 disclosure identified persistent underperformance at Don Gabriel: fewer ore tonnes and lower grades than forecast. The company linked that shortfall to weaker revenue, reduced cash generation and deteriorating liquidity. [P7]
It also reported that insufficient expected cash flow had led it to halt the start of Papomono’s caving operation temporarily. Rising input costs and Don Gabriel’s performance had weakened the funding available for the underground ramp-up. [P7]
In February 2023, the former parent announced court-approved bankruptcy liquidation of its Chilean subsidiary, Minera Tres Valles SpA. [P6]
The commercial lesson is the connection between these events. Weaker ore delivery can reduce recovered copper and cash generation at the same time that investment and fixed operating commitments continue. A funding gap can then interfere with the next production source intended to improve the situation.
The former parent’s disclosures concern its historical subsidiary. The current project identifies Compañía Minera Tres Valles SpA. The SMA names both Sociedad Minera Tres Valles en Liquidación Concursal SpA and Compañía Minera Tres Valles SpA in its proceedings. Liability allocation requires the relevant corporate and legal documents. [P1] [P4] [P6]
US$102 Million and US$30 Million: What Is Being Compared?
Portal Minero reported a US$102 million continuity proposal in June 2024. BNamericas subsequently reported withdrawal of the earlier submission. The First Environmental Court’s July 2026 description of the approved continuity project states an investment of US$30 million. [S3] [S4] [P5]
These figures should be retained with their respective dates and project contexts. Their difference does not, on its own, establish a reduction in the cost of identical works.
| Figure | Source context | Interpretation |
|---|---|---|
| US$102 million | Earlier continuity proposal reported in June 2024. | A historical estimate associated with that submission. |
| US$30 million | Continuity project described by the environmental court in July 2026. | A project investment figure, without proof here of complete financing. |
| Difference | Different descriptions in different project records. | Requires a comparison of scope, assumptions and cost boundaries before calculating savings. |
A commercial assessment should reconcile the works included, their timing and the treatment of mine development, rehabilitation, maintenance, compliance and working capital. It should then identify which amounts are funded and under what conditions.
The Operating Equation: Feed, Recovery, Cost and Cash
The environmental document describes annual copper cathode output of 18,500 tonnes in section 4.3.2, on PDF page 23. This is a project parameter rather than demonstrated annual production. [P1]
GCR’s January 2026 update targeted US$120 million in revenue and processing of more than 1.3 million tonnes of ore that year. These forward-looking figures do not establish the margin earned after mining, purchasing and processing costs. [P3]
More feed can improve utilization, but its value depends on recoverable copper and the resources required to extract it. Purchasing additional ore may also increase the amount of cash tied up before sales proceeds arrive.
| Condition | Commercial relevance | Evidence needed |
|---|---|---|
| Dependable own ore | Provides feed only if mining delivers suitable tonnes at a sustainable cost. | Ore delivery, grade, dilution and mining cost over time. |
| Suitable purchased material | Its contribution depends on settlement terms and recoverable copper. | Assays, contracts, treatment results and delivered purchase cost. |
| Processing performance | Equipment availability and metallurgical recovery determine saleable output. | Operating hours, recovery, consumables and cathode production. |
| Working capital | Bridges expenditure and the receipt of sales proceeds. | Available facilities, payment history and cash conversion cycle. |
| Environmental performance | Compliance and corrective work influence cost and operating continuity. | Monitoring, required works and current regulatory decisions. |
| Funded investment | Capital must be available when development and rehabilitation require it. | Committed financing, conditions, drawdowns and expenditure. |
This connects to Econosur’s analysis of Sierra Gorda’s expansion economics: using an existing operation changes the investment equation, while leaving execution and cash generation central to the outcome.
Supplier Confidence Is an Operating Requirement
Reuters reported August supplier protests over overdue payments and an acquisition-related dispute affecting liquidity. These reported matters require current documentation before assigning specific liabilities or unpaid amounts. [S1]
For a purchasing operation, settlement reliability affects the flow of material. Producers assess the buyer’s payment record, assay procedures, transport economics and purchasing conditions.
Delayed settlement can weaken suppliers’ willingness to deliver. Reduced deliveries can lower utilization and cash generation, making future settlement harder. Liquidity and supplier confidence therefore belong in the production analysis.
Potential contractors and equipment suppliers also need to distinguish the technical need for work from an accessible contract. Relevant questions include the purchasing entity, approved budget, contracting schedule, specifications and payment security.
Water and energy require project-specific checks. Econosur’s Chile mining water infrastructure analysis provides wider sector context; it does not establish Tres Valles’ own supply arrangements.
The 2024 Spill and the Current Environmental Record
The SMA describes a June 2024 release of leach solutions from the Quilmenco heap that reached the Río Choapa. It ordered provisional measures and later urgent, temporary measures addressing containment, repair, cleaning and monitoring. [P4]
Its December 2025 announcement identifies eight charges: one very serious, three serious and four minor. The very serious charge concerns failure to submit air-quality monitoring records for 2023, 2024 and the first half of 2025. [P4]
Other charges concern departures from approved leaching arrangements and use of emergency ponds. The SMA links these conditions to increased overflow risk and solution spills. Its public case file is marked as ongoing. [P4] [P4a]
The approval challenge is a separate proceeding
In July 2026, the First Environmental Court admitted a challenge brought by agricultural claimants against the continuity approval. Its announcement describes objections concerning water impacts and whether a more extensive assessment was required. [P5]
Admission of the claim does not establish annulment of the approval. An operating restriction should only be asserted against a current decision. The compliance case, the approval challenge and the approved project each need to be tracked separately.
GCR describes production operations through 2037 followed by a three-year final closure period. The overall 2040 timeline should therefore not be presented as copper production through 2040. [P2]
What Would Demonstrate a Durable Business?
- Ore performance: sustained delivery of suitable material, with reconciled grades, recovery and cost.
- Underground execution: a funded ramp-up that can continue through periods of lower output.
- Purchasing discipline: transparent settlement and a positive margin after treatment and financing costs.
- Investment clarity: a reconciliation of project estimates, committed funds and actual expenditure.
- Environmental control: documented performance, corrective work and current procedural status.
- Recurring cash generation: sufficient cash after operating needs, maintenance and obligations, rather than reliance on headline revenue.
Tres Valles illustrates how closely geological performance and commercial execution are connected. The historical record links weaker ore delivery with a loss of cash generation and difficulty financing the next production source.
The present business needs to demonstrate that it can manage that relationship more reliably. Existing assets and access to external ore create options, but each option carries a cost, a working capital requirement and operating conditions.
The regional purchasing network deserves particular attention. It makes Tres Valles a potential industrial outlet for independent producers, while making payment reliability part of its own feed security.
The decisive evidence will emerge from recurring performance: suitable feed, stable recovery, reliable settlement, funded development and effective environmental control. Together, these will show whether additional production becomes a durable business.
Research Services for Companies and Mining Projects
Econosur investigates defined commercial questions about South American companies and projects, connecting company claims with local records, sector context and direct verification where required.
Operating entities, ownership changes, business models, counterparties and the evidence behind investment claims.
Announcements, approvals, financing, construction progress and demonstrated operating results.
Purchasing structures, contractors, supplier requirements, potential buyers and procurement timing.
Market structure, infrastructure dependencies, partner questions and unresolved issues affecting a business decision.
Explore Company Reports or Custom Market Analysis South America.
Evidence date: October 17, 2026. Targets, historical figures and current procedural records retain their respective dates.
Financial evidence: the reviewed sources do not provide a complete current cost, financing and cash-flow dataset sufficient to establish profitability or a break-even copper price.
Investment comparison: the earlier and later estimates are not treated as identical scopes. No saving is calculated without reconciling the underlying submissions.
Ownership: the NIU acquisition and GCR structure follow published reporting and attributed statements. They do not substitute for a current corporate registry extract.
Legal status: charges and claims are distinguished from final findings. A historical statement about corrective action does not establish closure of an administrative case.
Measurement: ore tonnes, copper content, cathode output, capacity and sales are separate measures.
Supplier relevance: possible technical needs do not establish an open tender, available budget or awarded contract.
Primary and Secondary Sources
- [P1] Servicio de Evaluación Ambiental: Environmental qualification document — Continuidad Operacional Minera Tres Valles . January 2026 publication. Section 4.3.2, PDF page 23, states the annual cathode figure and processing route.
- [P4] SMA, December 2, 2025: SMA formula ocho cargos contra titulares de Minera Tres Valles . Official account of the charges, monitoring failures, leaching arrangements and 2024 incidents.
- [P4a] SMA / SNIFA: Case D-320-2025 . Procedural status and supporting documents.
- [P5] Primer Tribunal Ambiental, July 31, 2026: Challenge to the continuity approval — R-176-2026 . Admission of the claim, requested remedies and project description.
- [P2] GCR, January 8, 2026: Tres Valles environmental approval announcement . Parent-company identification, operating horizon and closure period.
- [P3] GCR, January 26, 2026: Minera Tres Valles as a strategic pillar . Company description of the business and forward-looking targets.
- [P7] Three Valley Copper, January 24, 2022: Suspends Mining Operations and Provides Strategic Review Update . Historical operating disclosure connecting Don Gabriel’s performance, liquidity and Papomono’s funding requirements.
- [P6] Three Valley Copper, February 17, 2023: Court Approval to Begin Liquidation Proceedings . Historical parent-company announcement.
GlobeNewswire distributes the historical releases; the originating source is Three Valley Copper. GCR disclosures establish company statements and targets, rather than independent confirmation of results.
- [S1] Reuters, October 16, 2026: Austrian investor rushes to boost copper production at old Chile mine . Also available as a Reuters republication in Mining Weekly . The two publications represent the same reporting.
- [S2] La Tercera / Pulso, January 22, 2026: Interview with Cevdet Caner and Sebastián Cortés . Acquisition history and attributed statements on the GCR structure. Interviewee claims remain attributed.
- [S3] Portal Minero, June 14, 2024: Earlier continuity proposal . Historical reporting of the US$102 million estimate.
- [S4] BNamericas, June 15, 2024: Minera Tres Valles withdraws EIA for operational continuity of Papomono mine . Historical withdrawal report. Its indexed title and date were accessible; the full article was not available for this review.
- Additional historical cross-check: Reporte Minero, January 26, 2022 — operating suspension . Secondary coverage of the earlier operational and liquidity difficulties.
- Source treatment: institutional decisions, company statements, interviews and independent reporting serve different evidential purposes. Repetition of a statement across publications does not make the underlying claim independently verified.
Investigate a Company or Project Question
Who controls the business? Which activities are operating? What is approved and funded? Which suppliers, obligations and commercial conditions need closer examination?
Econosur prepares focused research on South American companies, projects and industrial relationships.
Explore company reportsFrequently Asked Questions
What is Minera Tres Valles?
A copper operation in Chile’s Coquimbo region combining a mine development strategy with purchases of external ore and existing cathode processing facilities.
Who controls the company?
Published reporting links the April 2025 acquisition to Cevdet Caner through NIU Invest. Subsequent company disclosures identify GCR as the parent; Caner described Tres Valles as wholly owned by GCR.
What caused the earlier difficulties?
The January 2022 operating disclosure linked fewer ore tonnes, lower grades and rising costs to deteriorating liquidity and difficulty financing Papomono’s ramp-up.
Where does the 18,500-tonne figure come from?
It appears in section 4.3.2 on PDF page 23 of the January 2026 environmental qualification document. It describes annual cathode output in the project, rather than verified achieved production.
Can the investment figures be treated as cost savings?
A direct savings calculation would require reconciliation of the earlier proposal and the later project scope, assumptions and cost boundaries.
Does the timeline mean copper production until 2040?
GCR describes operations through 2037 and a subsequent three-year final closure period extending the overall timeline to 2040.
Is sustainable profitability established?
The reviewed evidence supports an analysis of the required conditions. It does not provide a complete current basis for confirming sustainable profitability.