South America · Lithium Triangle · Water Infrastructure · DLE · Pumps · Treatment
Water Infrastructure in Lithium Regions: Pumps, Treatment and Industrial Bottlenecks in South America
Lithium expansion in Argentina and Chile is no longer only a reserve story. It is becoming a test of brine handling, direct lithium extraction, desalination, high-pressure pumping systems, treatment technology, monitoring and social licence.
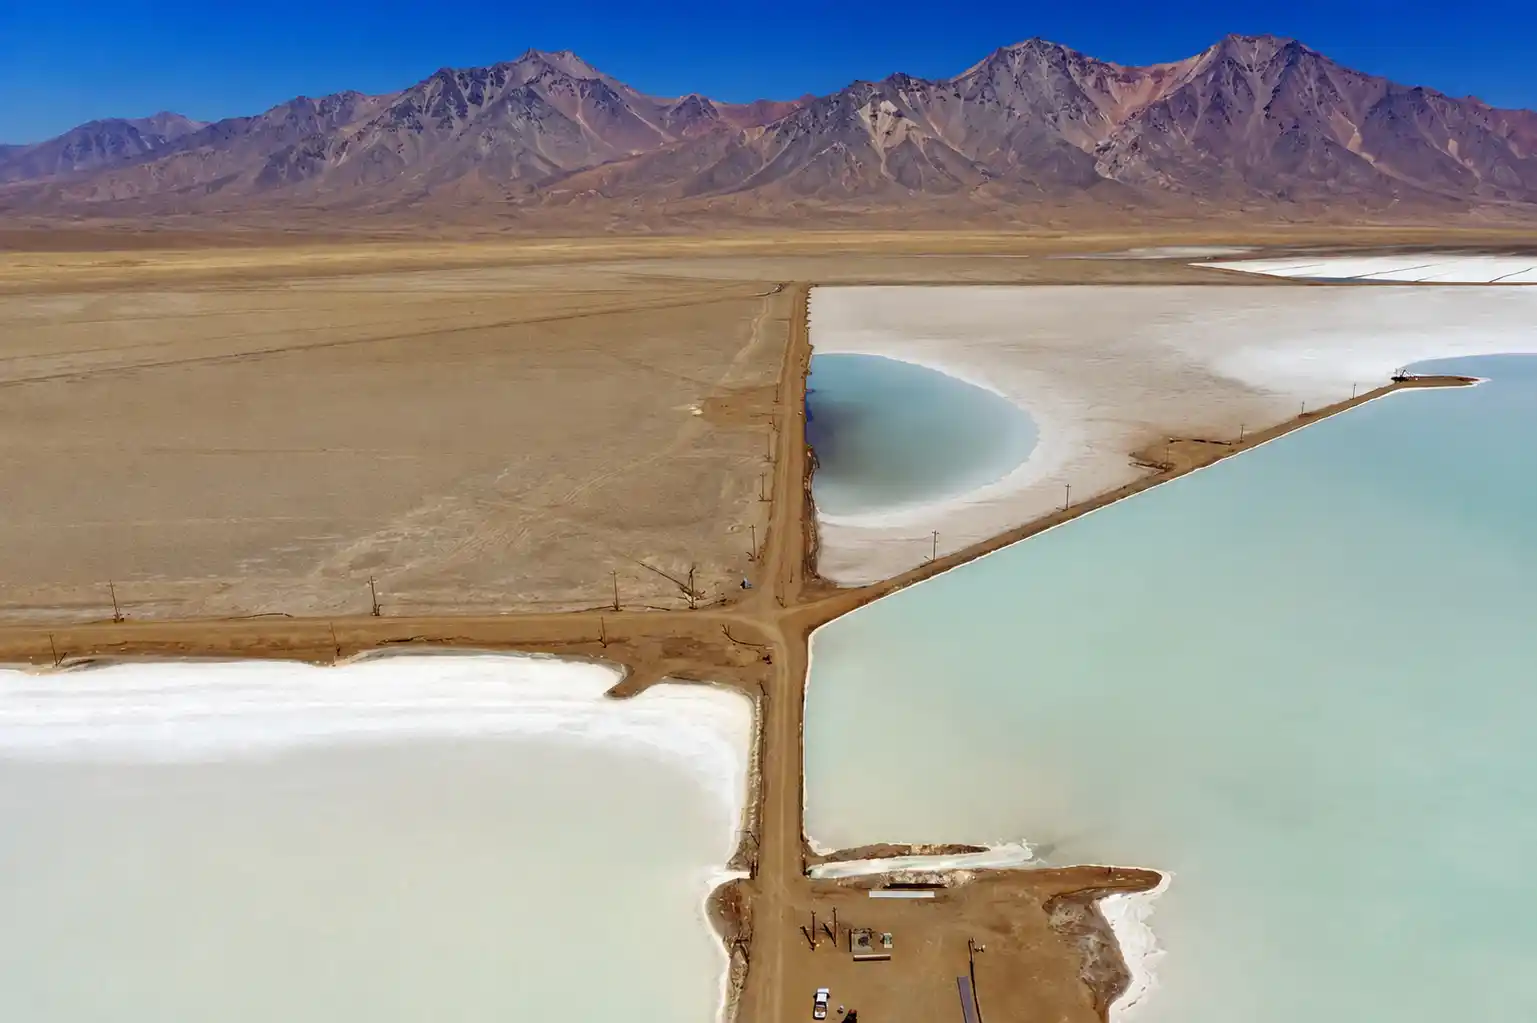
South America’s lithium regions are becoming water-infrastructure regions.
The next bottleneck is not only how much lithium Argentina and Chile can produce. It is whether lithium projects can manage brine extraction, process water, reinjection, desalination, high-altitude pipelines, pumping systems, treatment technology, monitoring and social licence at industrial scale.
The 2026 evidence is now more concrete. Eramet’s Centenario-Ratones plant in Salta reached 8,440 tonnes LCE of production in the first half, averaged 85% of nameplate capacity in the second quarter and reached a 90% pace in June. The ramp-up also exposed forced-evaporation, gas-supply and downstream reliability constraints, showing that industrial DLE depends on utilities and plant execution as much as on extraction chemistry.
In Chile, the water layer is splitting into different infrastructure models. Codelco’s Distrito Norte system is a dedicated coast-to-mine desalination and pumping platform, while CRAMSA’s Aguas Marítimas is an environmentally approved multi-user corridor that remains at development stage rather than operation.
This matters because Latin America already supplies a large share of global lithium and holds more than half of global lithium reserves, led mainly by Argentina and Chile. The IEA figures used here are a published reference point rather than a real-time production ranking; Chile remains the production anchor, while Argentina is becoming more important as new capacity comes online. The same region also faces ESG, permitting and community-pressure conditions that make water transparency, groundwater monitoring and local trust central to project execution.
For broader context, see Econosur’s lithium and mining sector page, Centenario DLE case, NovaAndino Litio, Chile seawater-mining infrastructure and South America Sector Briefs.
Core market reading:
The hidden water-infrastructure layer is difficult to size as one clean market category. It appears through DLE capex, desalination capacity, long-distance pipelines, high-pressure pumping systems, reverse osmosis, dosing, brine handling, monitoring and permitting delays.
That makes lithium water infrastructure more than a sustainability topic. It is becoming a supplier market, a project-risk factor and a visibility question for industrial firms that want to be considered in South America’s next lithium build-out.
Lithium Regions Are Water Regions
Lithium is usually discussed as a battery mineral, a geopolitical asset or an export opportunity. In the high-altitude salars of Argentina and Chile, it is also a water-system question.
Brine-based lithium production depends on the movement, concentration and treatment of underground saline water. Traditional evaporation systems pump lithium-bearing brine to the surface and move it through pond systems over long periods. Newer direct lithium extraction systems promise shorter processing times and higher recovery, but they do not remove the need for hydraulic control, brine chemistry, pre-treatment, reinjection and monitoring.
That distinction is the whole point. The lithium story is not only about reserves beneath a salt flat. It is about the operating system above and around the salar: pipes, pumps, lagoons, membranes, reagents, power supply, water rights, environmental baselines and community trust.
The International Energy Agency frames Latin America as one of the essential regions for the clean-energy mineral transition. It notes that the region supplies about 35 percent of the world’s lithium and holds more than half of global lithium reserves, mainly in Argentina and Chile. The same analysis stresses that mining projects must meet high ESG standards, establish environmental baselines and maintain transparency on water use, wastewater characteristics and emissions.
"The lithium bottleneck is not only below the salt flat. It is in the water system that makes extraction credible."
The Atacama Signal: Brine Extraction Becomes an Infrastructure Metric
Chile’s Salar de Atacama is the clearest place to see the transition from lithium as a resource story to lithium as a water-infrastructure story.
Albemarle’s DLE project in the Salar de Atacama is important because it expresses the water question in operational numbers. Reuters reported that the project could involve a US$3.1 billion investment, a DLE plant with up to six processing trains and a potential reduction in brine extraction from 442 litres per second to 342 litres per second with one train, and as low as 142 litres per second with all six trains.
That is more than a sustainability claim. It turns water and brine movement into a production parameter. The mine plan, the extraction method, the plant design and the social licence become connected through litres per second.
Atacama also shows why the water question will not disappear. Reuters separately reported on a University of Chile study that found areas of the Salar de Atacama sinking by 1 to 2 centimetres per year where lithium brine extraction is most intense, linked to extraction outpacing natural aquifer recharge.
The institutional structure around the Salar de Atacama has also changed. NovaAndino Litio now provides the Codelco–SQM operating vehicle for the existing lithium system. SQM manages the operation through 2030, while Codelco is scheduled to assume general management from 2031. This matters because future water, technology and supplier decisions sit inside a governance transition rather than a simple new-mine build.
Albemarle’s Atacama plan shows that DLE is not only a process-technology upgrade. It is a water-system redesign with capital expenditure, trains, brine volumes, power and environmental review.
Lower brine extraction may improve the project profile, but subsidence, aquifer recharge, brine chemistry and long-term monitoring remain part of the investment case.
Local communities do not evaluate lithium projects only by output. They evaluate whether water, brine, wetlands, livelihoods and data are managed credibly.
Argentina’s Warning: Water as Permitting Risk
Argentina shows the same issue from a different angle: water can become a permitting risk before it becomes a production bottleneck.
In Catamarca, Reuters reported that a court halted new mining permits in the Los Patos River and Salar del Hombre Muerto area until new environmental impact studies are completed. The case followed complaints by an Atacameños community about water use and alleged depletion of local water resources. Current production was not halted, but new permissions were suspended pending additional studies.
For investors, suppliers and lithium buyers, the message is clear. Water questions are not externalities. They can shape project timelines, cumulative-impact assessments, consultation processes and expansion risk.
That matters for the entire equipment and services layer. If future lithium projects must demonstrate better control over brine extraction, freshwater interaction, industrial wastewater, process stability and monitoring, then suppliers of pumps, filtration, dosing, RO systems, sensors, control systems and environmental services become part of the supplier-access equation.
Argentina’s lesson:
In lithium regions, permitting risk increasingly sits where geology meets water governance. A project can have resources, capital and buyers, yet still face delays if cumulative water impacts and community participation are not credible.
DLE Does Not Remove the Water Question
Direct lithium extraction is often presented as the answer to the water problem. That is too simple.
DLE can reduce brine extraction, increase recovery and shorten production cycles. It can also change the nature of the bottleneck. Instead of waiting for evaporation ponds, the project must manage plant design, chemical selectivity, brine pre-treatment, adsorption or ion-exchange media, filtration, scaling, reagent use, reinjection and long-term system monitoring.
Reuters described Arcadium’s direct lithium extraction capability as a major strategic prize in Rio Tinto’s acquisition logic. That is telling. The technology is valuable because it moves lithium from a slow pond-based model toward a more industrial process platform.
But industrial process platforms need infrastructure. They require stable energy, skilled maintenance, pumps that tolerate corrosive brines and slurries, dosing systems that remain accurate, filtration that handles variable chemistry and monitoring that can satisfy regulators and communities.
Centenario: What Operating DLE Reveals About Infrastructure
Eramet’s Centenario-Ratones plant provides a stronger operating reference than a future DLE concept. Eramet reported 8,440 tonnes LCE of production in the first half of 2026, an average 85% of nameplate capacity during the second quarter and a 90% pace in June.
The ramp-up also shows why DLE should not be treated as one stand-alone extraction unit. During 2025, commissioning was affected by a technical issue in the Forced Evaporation equipment. In early 2026, gas-supply limitations and equipment-related maintenance also affected operations. These are not brine-chemistry questions alone. They are utilities, downstream-process, reliability and maintenance questions.
Eramet’s current 2026 guidance of 17,000–20,000 tonnes LCE and its studies for an initial 11,000-tonne brownfield expansion move the supplier question into two layers: operating optimisation at the existing plant and future engineering, equipment and service demand around expansion.
Operating DLE lesson:
DLE changes the water and process architecture, but it does not remove conventional plant-execution risk. Gas, power, forced evaporation, pumps, downstream equipment, maintenance, brine management and reinjection still have to work as one system.
Desalination, Pipelines and High-Altitude Pumping
Chile’s mining sector offers a preview of what water infrastructure can become at full scale.
Bechtel’s Escondida Water Supply project is not a lithium case, but it is one of the clearest infrastructure references for mining water systems in the Atacama. The project connected a seawater desalination plant to the Escondida mine through two 170-kilometre pipelines, each 107 centimetres in diameter, and transported water to more than 3,100 metres above sea level through four high-pressure pump stations.
This is the physical meaning of water infrastructure: coast, intake, reverse osmosis, brine discharge, transmission lines, pump stations, long-distance pipelines, land rights and high-altitude delivery.
The International Bar Association reports that Chile has 24 operational desalination projects with a combined installed capacity of 10,583 litres per second, nearly all located in the northern mining regions of Tarapacá, Antofagasta, Atacama and Copiapó. The same source points to regulatory challenges around environmental authorization, maritime concessions and surface land rights.
For lithium regions, the lesson is not that every salar will use the same seawater model. The lesson is that water supply increasingly becomes a dedicated infrastructure market, with its own permitting, engineering, energy and social-licence risks.
Two Chilean Water Models: Dedicated Mine Supply and Regional Corridor
Chile now offers two useful infrastructure models that go beyond the historical Escondida benchmark.
Codelco / Aguas Horizonte: Distrito Norte. The dedicated desalination system is designed around Codelco’s northern copper operations. The initial system is designed for 840 litres per second, with 630 litres per second of nominal flow, and extends more than 160 kilometres from the coast toward the Calama mining district. The ownership model is BOOT: the private project company finances, builds, owns and operates the infrastructure before transfer after the agreed operating period. By September 2026, Aguas Horizonte was still publishing construction progress, current mining-sector reporting described the system as being in commissioning, and Techint continued to indicate 2026 completion rather than established full commercial operation.
CRAMSA / Aguas Marítimas: regional multi-user corridor. The environmentally approved project is designed around a final capacity of 700,000 cubic metres per day and roughly 480 kilometres of regional distribution infrastructure toward Antofagasta, Sierra Gorda and Calama. It is intended to serve mining, industrial and potentially agricultural users rather than one mine operator.
The distinction matters commercially. Distrito Norte is a defined mine-linked procurement system. Aguas Marítimas is a corridor project whose future execution still depends on financing, customers, detailed contracting and construction. Environmental approval does not prove that the complete system is financed or operating.
The Hidden Equipment Layer: Pumps, Dosing and Treatment
Once lithium is read as water infrastructure, a hidden equipment market becomes visible.
Watson-Marlow describes a Chilean lithium processing site using more than 50 Bredel and Qdos pumps, including applications in lime dosing, lithium carbonate reactors, lithium hydroxide production and lithium sulphate transfer. Those details matter because they show that the lithium process is not only a mining story; it is an industrial fluid-handling story.
Fluence describes the water-treatment side of lithium brine extraction: reverse osmosis, nanofiltration, ultrafiltration, ion exchange, wastewater reuse and brine concentration. Its South American references include a high-pressure reverse osmosis brine concentration plant for FMC-Minera del Altiplano’s Salar del Hombre Muerto operation in Argentina and water-treatment systems for other lithium operations.
This is where the supply-chain opportunity sits for industrial firms. Lithium projects require equipment that can handle corrosion, scaling, solids, variable brine chemistry, remote sites, high altitude, difficult maintenance, limited water access and regulatory scrutiny.
Sizing the Hidden Layer
The water-infrastructure layer behind lithium is not reported as one neat market segment. It is fragmented across DLE plants, desalination systems, long-distance pipelines, pump stations, reverse osmosis, filtration, dosing, reagent handling, wastewater reuse, monitoring, environmental studies and operations services.
That does not mean the layer is small. It means it has to be read through project and infrastructure proxies.
Albemarle’s Atacama DLE plan alone has been described as a potential US$3.1 billion investment. The project is designed around modular processing trains and a major reduction in brine extraction, from a current 442 litres per second to 342 litres per second with one train and potentially 142 litres per second with all six trains. That is not a marginal equipment upgrade. It is a redesign of how a lithium salar is operated.
Chile’s broader mining water transition shows the same logic at a larger scale. Reuters, citing Cochilco, reported that seawater is expected to account for 70 percent of Chilean mining water supply by 2034, with seawater consumption reaching 16.53 cubic metres per second. Pumping and desalination for seawater use are expected to consume 6.5 terawatt-hours by 2034, roughly one-fifth of Chilean mining-industry electricity consumption.
Desalination capacity gives another proxy. The International Bar Association cites 24 operating desalination projects in Chile above 20 litres per second, with a combined installed capacity of 10,583 litres per second, concentrated in mining regions such as Tarapacá, Antofagasta, Atacama and Copiapó. The Bechtel-built Escondida water-supply system shows what that means physically: two 170-kilometre pipelines, desalinated water moved across the Atacama Desert to more than 3,100 metres above sea level, and four high-pressure pump stations.
| Proxy | What it shows | Why it matters for suppliers |
|---|---|---|
| US$3.1bn DLE plan | Albemarle’s Atacama project shows that DLE is a capital-intensive industrial redesign, not only a new extraction method. | Creates demand for process engineering, pumps, filtration, power, automation, maintenance and monitoring. |
| 442 → 142 l/s brine extraction | Brine flow becomes a core operating metric for environmental approval and project credibility. | Requires better hydraulic control, metering, reinjection logic, sensors and site-specific system design. |
| 70% seawater by 2034 | Mining water supply in Chile is shifting from inland freshwater logic toward coastal desalination and seawater transport. | Expands the market for desalination, pipelines, pumping stations, energy systems and corrosion-resistant components. |
| 6.5 TWh for pumping and desalination | Water infrastructure becomes an energy-infrastructure issue as seawater is moved inland and uphill. | Links water suppliers with power, efficiency, automation and reliability requirements. |
| 10,583 l/s desalination capacity | Chile’s operating desalination base is already a visible industrial platform in mining regions. | Supports recurring demand for membranes, RO, intake systems, brine discharge management and O&M services. |
| 170-km pipelines to Escondida | Water access can require large physical systems across desert, coast and high-altitude mining areas. | Creates opportunities in high-pressure pumping, pipeline engineering, valves, controls and maintenance. |
Interpretation:
The hidden market is not one product category. It is an operating system. It includes the technologies and services that allow lithium extraction to pass the tests of water availability, brine chemistry, energy use, environmental approval and local trust.
Industrial Bottlenecks to Watch
The water-infrastructure bottleneck in lithium regions is not one single constraint. It is a stack of constraints.
First, there is the hydrogeological constraint: salars are complex systems, and brine extraction can interact with freshwater, wetlands and local ecosystems in ways that are difficult to explain to communities and regulators.
Second, there is the process constraint: each brine chemistry is different. That makes DLE, filtration, scaling control, reagent use and reinjection site-specific rather than standardized.
Third, there is the infrastructure constraint: desalination, pipelines, pump stations, power lines, roads, camps and chemical logistics all have to work in remote, high-altitude and arid conditions.
Fourth, there is the governance constraint: communities and courts increasingly ask for cumulative-impact assessments, public data, consultation and clearer evidence that water systems will not be sacrificed for export revenue.
| Bottleneck | What it means | Supplier opportunity |
|---|---|---|
| Brine handling | Moving, concentrating, treating and potentially reinjecting brine under site-specific chemical conditions. | Pumps, valves, corrosion-resistant materials, sensors, process control and engineering services. |
| DLE scale-up | Turning pilot systems into reliable industrial trains with stable recovery and quality. | Filtration, pre-treatment, ion exchange, membranes, reagents, automation and maintenance systems. |
| Water supply | Reducing pressure on local freshwater through reuse, treatment, desalination or alternative sourcing. | RO systems, desalination, pipelines, pump stations, wastewater reuse and energy integration. |
| Monitoring and trust | Providing credible data on groundwater, surface water, brine systems and cumulative impacts. | Environmental monitoring, analytics, reporting, field services and ESG verification. |
Three Scenarios for Lithium Water Infrastructure
The future of water infrastructure in South American lithium regions can be read through three scenarios.
| Scenario | What happens | Strategic meaning |
|---|---|---|
| Compliance retrofit | Projects add monitoring, treatment and efficiency measures mainly to satisfy regulators and communities. | Useful, but reactive. Water remains a risk-control layer rather than a strategic capability. |
| DLE infrastructure platform | Projects redesign extraction around DLE trains, brine reduction, reinjection, process control and supplier integration. | Water infrastructure becomes part of productivity, permitting and buyer credibility. |
| Regional water-industrial corridor | Desalination, pipelines, treatment hubs, monitoring networks and shared services support multiple mining and industrial users. | Lithium regions become broader industrial infrastructure markets, not isolated extraction sites. |
The second scenario is already visible in the Atacama DLE discussion. The third scenario is harder, but it is the one that could create the deepest equipment, engineering and services market.
What Companies Should Watch
For pump manufacturers, water-treatment firms, automation providers, environmental-monitoring companies, engineering firms and industrial suppliers, lithium regions should be read as project-specific operating systems rather than one generic equipment market.
The key questions are commercial and operational: which entity owns the water or process package, who controls the technical specification, where vendor qualification sits, which contractor or integrator manages the package and whether the project is operating, under construction, environmentally approved or still dependent on financing.
Centenario, Distrito Norte and Aguas Marítimas illustrate three different buying environments. An operating DLE plant creates reliability and brownfield demand. A dedicated mine-water system creates infrastructure packages around one operator. A multi-user corridor creates a separate project-finance, customer and contracting structure.
- Which entity controls the relevant water, DLE or process package?
- Which suppliers are already qualified or incumbent at project level?
- Which packages are operating replacements, active construction, environmental-stage projects or future concepts?
- Where do brine extraction limits, freshwater concerns and social licence create execution risk?
- Who controls technical specifications, vendor approval and final purchasing authority?
- Which systems require local installation, maintenance, spare parts and high-altitude field service?
- Which procurement, service or execution layer remains unresolved and requires direct verification?
What Econosur Can Research Around Lithium Water Infrastructure
Econosur can structure focused research around a specific lithium project, water system, supplier category or procurement question. The purpose is to move from visible infrastructure demand to the commercial layer: who controls the package, which suppliers are already positioned, what qualification evidence matters and where public information stops.
Environmental approval, construction progress or a supplier reference does not by itself prove an open commercial opportunity. Where package ownership, tender status, qualification or buyer responsibility remains unclear, the next step is targeted verification.
Lithium water risk is moving from an ESG issue into the execution architecture of the project.
Centenario shows that even operating DLE depends on utilities, downstream equipment, maintenance and process stability. Albemarle’s Atacama project shows how future lithium systems are redesigning brine extraction itself. Distrito Norte adds a different signal: by September 2026 the large desalination and pumping system was in commissioning, moving from construction toward the operating phase, while Aguas Marítimas remained an approved but still development-stage regional corridor.
For suppliers, the relevant market is therefore not “lithium water equipment” as one category. It is a set of project-specific packages controlled by mine owners, project companies, water developers, EPC structures and operating teams, each at a different point between concept, approval, construction, commissioning and operation.
The strongest commercial signal is the transition from technical concept to repeatable execution: an operating plant, a commissioned water system, a defined package owner, qualified suppliers and measurable performance.
Verified operating: Centenario-Ratones is an operating DLE plant; Salar de Atacama is an established lithium-production system; Chile has an existing mining-desalination base.
Current implementation / operating transition: Centenario is still ramping and optimising; NovaAndino Litio provides the current Codelco–SQM governance structure for the Salar de Atacama; Aguas Horizonte was still publishing September 2026 construction progress for Distrito Norte, current mining-sector reporting described the system as being in commissioning and Techint continued to indicate 2026 completion.
Environmental / development stage: Albemarle’s proposed Atacama DLE transition and CRAMSA’s Aguas Marítimas corridor remain development-stage projects. Environmental review or approval does not establish financing, construction or operation.
Planned / future: additional DLE trains, expansion phases, broader reinjection systems and regional multi-user water corridors.
Unresolved: package-level suppliers, current RFQs, EPC or integrator responsibility for individual lithium-water systems, final DLE water balances, long-term reinjection performance, project-specific freshwater displacement and actual supplier qualification.
This article prioritises official project, company and institutional sources for current project status. Reuters and other secondary reporting are used for independent context. Supplier case studies are treated as self-reported technical evidence unless independently confirmed. Evidence updated through 26 September 2026.
Primary & official project sources
- Eramet — H1 2026 results: Centenario reached a 90% pace of nameplate capacity in June and expansion studies are progressing.
- Eramet Eramine — depleted-brine recirculation study approval: environmental approval for study wells and recirculation tests; not proof of routine full-scale reinjection.
- Albemarle — Atacama DLE environmental review: company description of the TED project, DLE efficiency and planned reduction in net brine pumping.
- Codelco — Distrito Norte desalination project: 840 l/s initial design capacity, expansion potential to 1,956 l/s, more than 160 km of pipeline and the Aguas Horizonte BOOT model.
- Aguas Horizonte — Distrito Norte project progress: September 2026 construction-progress reporting and current commissioning-stage context.
- Techint Engineering & Construction — SADDN project: EPC scope, three pumping stations, transmission infrastructure and expected 2026 completion.
- CRAMSA — Aguas Marítimas environmental approval: May 2026 RCA and planned capacity of up to 700,000 m³/day; approval does not establish financing or operation.
- Bechtel — Escondida Water Supply: desalination, 170-km pipelines and high-pressure pumping reference.
Institutional & technical sources
- IEA — Latin America and critical minerals.
- World Resources Institute — critical minerals and water impacts.
- International Bar Association — Chile’s desalination challenge.
- Watson-Marlow Fluid Technology Solutions: supplier case study on pump and dosing applications in Chilean lithium processing.
- Fluence: supplier reference on treatment technologies and lithium-brine water systems.
Secondary & contextual sources
- Reuters — Albemarle Atacama DLE environmental review.
- Reuters — Salar de Atacama subsidence study.
- Reuters — Catamarca permit restrictions and water concerns.
- Reuters — Rio Tinto / Arcadium DLE technology context.
- Reuters / Cochilco — Chile mining water and energy outlook.
- Minería Pan-Americana — Distrito Norte commissioning status, 1 September 2026: current industry reporting on the commissioning phase; used as secondary status context rather than as the project owner source.
Econosur project-level context
From lithium reserves to water-infrastructure reality
South America’s lithium expansion depends on more than salars and battery demand. The decisive questions are brine handling, DLE scale-up, water treatment, desalination, pumping systems, monitoring, community trust and supplier readiness.
Econosur prepares sector briefs, company reports and custom market analysis for companies, analysts and institutions evaluating lithium regions, water infrastructure, DLE, industrial suppliers, procurement structures and project execution.
Explore custom market analysisFAQ
Why are lithium regions also water-infrastructure regions?
Lithium brine extraction depends on brine pumping, evaporation or direct lithium extraction, process water, reinjection, treatment, monitoring and local water governance. In arid salars, the water system around lithium can become as important as the mineral resource itself.
What does Centenario show about industrial DLE?
Eramet’s Centenario-Ratones plant provides operating evidence that DLE is an integrated plant-execution problem rather than only an extraction technology. Eramet reported 8,440 tonnes LCE of H1 2026 production, 85% average nameplate utilisation in Q2 and a 90% pace in June. Earlier constraints included forced-evaporation equipment and gas supply.
Does direct lithium extraction remove the water problem?
Direct lithium extraction can reduce brine extraction and shorten processing times, but it does not remove the infrastructure challenge. It creates new requirements for brine chemistry, pre-treatment, reinjection, pumps, monitoring, energy and project-specific design.
Why is desalination relevant to lithium regions?
Desalination shows how mining in northern Chile is moving from local freshwater pressure toward large water infrastructure systems: coastal plants, pipelines, high-pressure pump stations, power lines, permits and brine discharge management.
What is the hidden equipment market behind lithium expansion?
The hidden equipment market includes pumps, valves, dosing systems, reverse osmosis, ultrafiltration, nanofiltration, brine concentration, wastewater reuse, process control, monitoring systems and engineering services.
What is the main risk for lithium projects in water-stressed regions?
The main risk is not only water volume. It is the interaction of water rights, brine extraction, aquifer data, cumulative impacts, permitting, indigenous consultation, transparency and social licence.