Chile · Mining Logistics · Port Infrastructure · Antofagasta · October 3, 2026
Antofagasta’s Logistics Expansion: Mining, Port Infrastructure and New Supplier Demand
Northern Chile’s largest mining investment region is expanding more than mine capacity. Puerto Antofagasta is tendering dredging works, adding inland logistics space and modernising its rail-linked support system, while Mejillones is competing for lithium, copper and cross-border cargo. The supplier opportunity is real, but it sits in specific projects, tenders and operating chains rather than in the headline investment total.
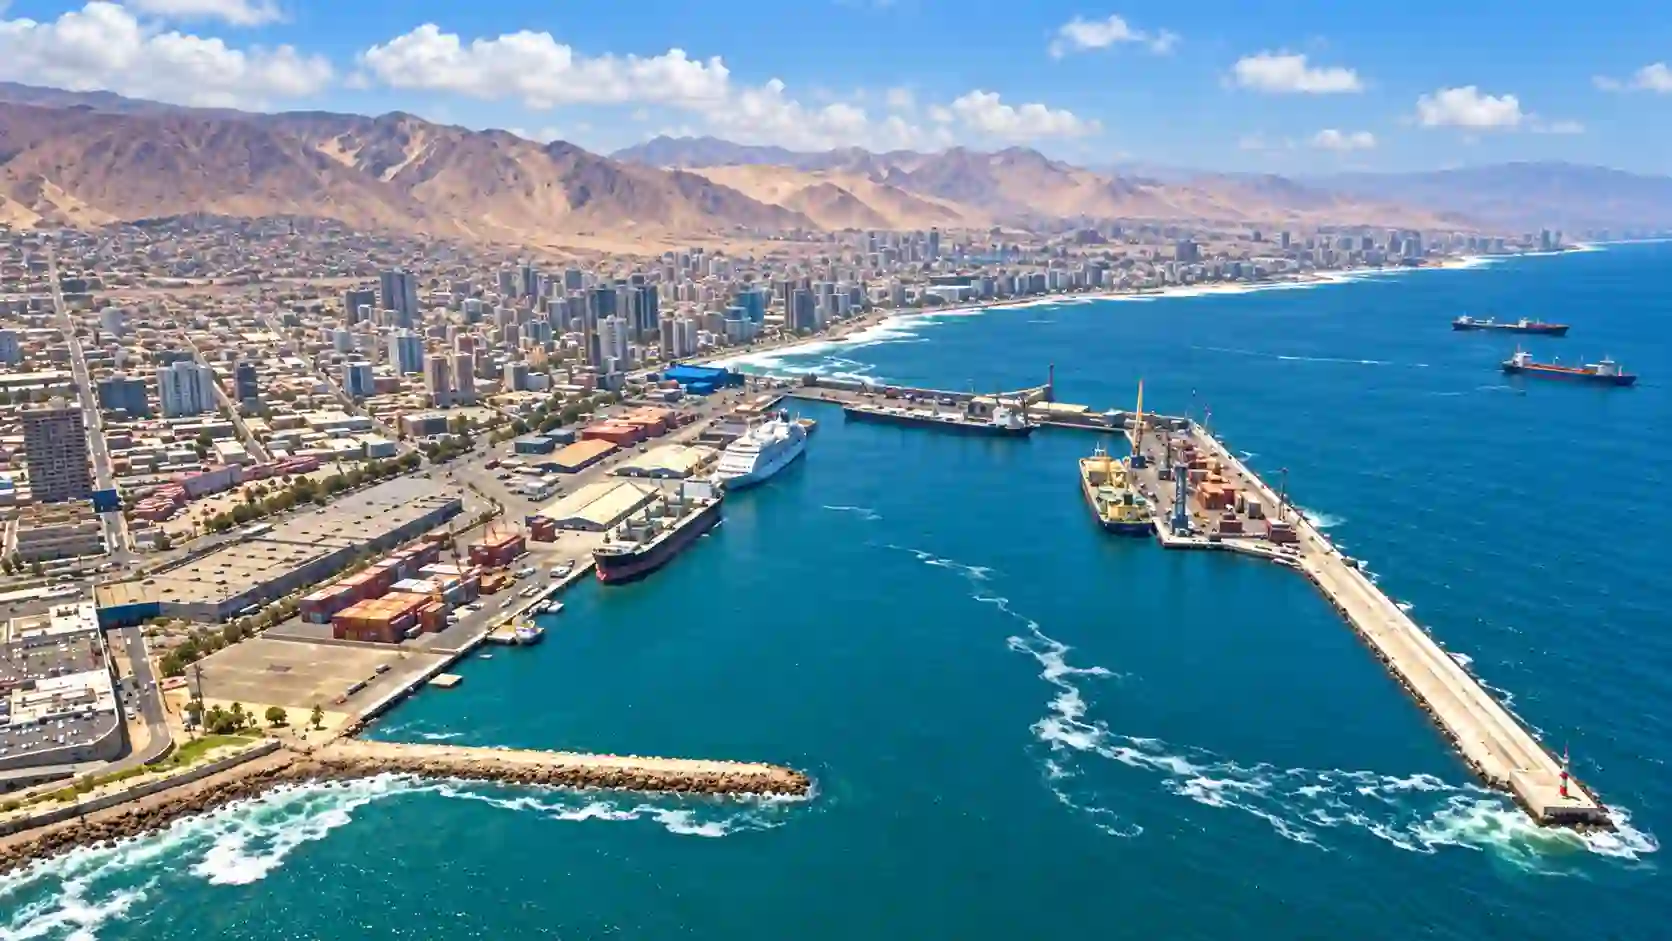
Antofagasta is moving from a mining-centred logistics base toward a broader port, inland-logistics and cross-border system, and parts of that shift are already generating identifiable supplier demand.
Cochilco places the Antofagasta Region at approximately US$40.7 billion in its 2025–2034 mining investment portfolio, making it Chile’s largest regional mining-investment concentration. Two projects illustrate the scale: BHP’s proposed Escondida New Concentrator is a US$5.4–6.3 billion plan that BHP says would have a significant impact on supplier development, while Antofagasta Minerals is building the US$4.4 billion Nueva Centinela expansion for start-up in 2027.
The logistics layer is advancing at the same time. Puerto Antofagasta is tendering dredging works, developing the 50-hectare Zona de Desarrollo Logístico La Negra and modernising the rail-linked Antepuerto Portezuelo. The port says these projects are designed to raise transfer capacity from about 3.5 million to a potential 7 million tonnes per year.
Supplier opportunity should nevertheless be separated into three levels: current procurement, such as dredging and operating services; project-driven future demand, such as mine expansion packages; and conditional demand tied to projects or cross-border cargo flows that still depend on permits, financing, infrastructure and customer decisions.
Antofagasta’s mining pipeline is large, but not one market
Antofagasta is the core of Chile’s copper economy and the largest regional component of Cochilco’s current mining-investment portfolio. In the 2025–2034 presentation, Cochilco gives the region a total of US$40.734 billion: the regional chart shows US$40.209 billion associated with copper and US$525 million with other minerals. For readability, this analysis uses approximately US$40.7 billion throughout.
That number matters because mine investment creates logistics requirements before, during and after construction: imported equipment, steel, process components, construction materials, replacement parts, warehousing, heavy transport, rail capacity, port transfer and maintenance. It also connects directly with Econosur’s broader analysis of Chile’s copper and lithium investment pipeline and the infrastructure constraints around seawater supply for northern mining .
The investment total does not describe one homogeneous procurement market. Cochilco classifies 41% of national investment as base, 6% as probable, 13% as possible and 40% as potential. It also shows that replacement projects account for 47% and expansion projects for 34%, meaning 81% of the portfolio is brownfield. New projects represent 19%. That matters for foreign suppliers because brownfield and continuity projects often work through established specifications, incumbent contractors, approved-vendor systems and operating-site requirements rather than open greenfield procurement.
The useful market question is not “How large is the mining pipeline?”
It is: which projects are approved, which packages are being procured, who controls qualification, which suppliers are already positioned, and where logistics capacity must expand to keep the project operating.
Mine projects show different demand clocks
Escondida New Concentrator
BHP submitted the project to Chile’s Environmental Assessment System in March 2026. BHP’s August 18 results revised the plan to US$5.4–6.3 billion; it would replace the historic Los Colorados plant with new capacity able to produce 230–270 thousand tonnes of copper per year.
BHP explicitly says the construction programme would have a significant impact on supplier development. It projects an average of 2,500 workers per month during construction and peaks of 6,000. First production could occur in 2031–2032 if environmental approval is obtained.
BHP’s August update gives a 50-million-tonne annual ore-processing capacity, about US$500 million in preparation funding and an expected final investment decision in 2027–2028. Preparation funding does not constitute approval of the full construction programme.
Nueva Centinela
Antofagasta Minerals is building a second concentrator at Minera Centinela. The company describes the expansion as a US$4.4 billion project and says the second concentrator is scheduled to enter operation in 2027.
The expansion extends the mine’s operating scale and life, while associated works include autonomous mining systems and supporting infrastructure. Its supplier relevance is therefore different from Escondida’s proposed concentrator: Centinela is already in execution, while the Escondida project still depends on environmental approval and subsequent construction decisions.
The distinction is important. A project in construction can create immediate demand for equipment, contractors, logistics and commissioning support. A project in environmental review can be commercially relevant for early positioning, specification work and partner mapping, but it should not be presented as an awarded contract opportunity.
Sierra Gorda adds another expansion timetable
Sierra Gorda, in Antofagasta Region, launched its US$725 million fourth grinding line in October 2026. KGHM schedules completion for end-2029. The project provides another regional investment signal; its disclosure does not identify a cargo terminal or open logistics contract. Read Sierra Gorda’s expansion economics.
Puerto Antofagasta is expanding the maritime and inland system together
Puerto Antofagasta’s current strategy is not limited to the waterfront. Its Plan Maestro combines marine works with inland logistics and rail-linked cargo management. The port’s stated objective is to increase transfer capacity from about 3.5 million tonnes per year to a potential 7 million tonnes as strategic projects are developed.
The most immediate procurement signal is the current tender for dredging Sites 1 and 2. Puerto Antofagasta’s September 2026 documentation gives a reference volume of 46,678 cubic metres: 35,568 cubic metres of sand and sediment and 11,110 cubic metres of rock. Companies can bid for the full project or separately according to material and specialisation. The reference execution period is 365 calendar days, with bathymetric measurement and environmental controls included in the monitoring structure.
As of October 3, the tender is still live: technical offers are scheduled to be received and opened on October 20, followed by economic offers on October 27. This is also the second call. Puerto Antofagasta launched the current process after the previous call was declared unsuccessful. The episode is a useful reminder that even a defined infrastructure requirement does not automatically become an awarded contract.
| Infrastructure layer | Documented status | Supplier relevance | Commercial timing |
|---|---|---|---|
| Dredging Sites 1 & 2 | Live second public tender | Marine engineering, dredging, environmental control, bathymetry, port coordination | Immediate |
| Breakwater / maritime expansion | Part of the master-plan build-out | Marine works, civil engineering, materials, specialist services | Project-dependent |
| La Negra | First stage urbanised; spaces being occupied | Warehousing, heavy transport, mining spares, fabrication, logistics and industrial services | Current and near-term |
| Portezuelo | Operating; modernisation and expansion | Rail-port coordination, mineral storage, cargo handling, equipment and maintenance | Current and expansion-linked |
| Bioceanic cargo | Developing corridor and pilot commercial flows | Transport, border services, storage, consolidation, distribution and multimodal logistics | Conditional / scaling |
La Negra moves part of the port economy inland
The Zona de Desarrollo Logístico La Negra is the clearest sign that the port’s strategy is extending beyond ship transfer. The platform covers 50 hectares near Route 5; roughly 30 hectares have been urbanised with internal roads, basic services and lighting. Puerto Antofagasta describes the site as a base for storage, conditioning, consolidation, deconsolidation and distribution of cargo, as well as industrial and service activity linked to regional production and foreign trade.
In July 2026 the port said the platform included 36 spaces for small and medium-sized companies, starting at 900 square metres, plus six larger industrial sites of roughly 1.3–2.4 hectares. It identified activities connected with lithium and other minerals as well as warehouses, distribution centres and cold-storage functions for other cargo.
The September update makes the supplier signal more concrete. Puerto Antofagasta said committed SME projects include heavy transport, mining-equipment spare parts, fabrication of structures, logistics services and circular-economy initiatives. That segment was reported at 75% occupancy, counting signed contracts and others in the signing process.
For industrial suppliers, this matters because logistics land can change the practical market-entry model. A supplier does not necessarily need to serve a mine only from Santiago or from an overseas warehouse. Local stock, repair capability, assembly, return logistics, spare-parts availability and distribution can become part of the commercial offer in a region where downtime and distance carry a high cost.
Portezuelo and FCAB provide the rail-linked operating base
Antepuerto Portezuelo already performs a function that the wider logistics strategy wants to scale: receiving, storing and managing cargo outside the waterfront before dispatch to the port. Puerto Antofagasta says Portezuelo handles mining concentrates, including Bolivian cargo transported mainly by rail, and provides more than 22,000 square metres of warehouse space in the La Negra area.
The rail layer is commercially important because FCAB is not only a train operator. It offers freight transport, storage, transfer, loading and unloading services and customs-document handling. Through connections with Ferronor and Empresa Ferroviaria Andina, FCAB describes its network as part of the corridor linking Antofagasta and Mejillones with northern Argentina, southern Bolivia, southern Brazil and Paraguay.
In January 2026 FCAB framed the challenge directly: announced mining-production growth in Chile and Argentina, including copper concentrates and lithium, together with the Bioceanic Corridor, requires coordination between rail, ports, public authorities and potential customers. That makes rail capacity part of the supplier and project equation rather than a separate transport topic.
Mejillones is a competing and complementary logistics node
A regional analysis cannot treat Puerto Antofagasta as the only outlet. Mejillones has a major operating port system of its own and is already specialised in mining and energy cargo. The most visible 2026 example is the lithium logistics platform built by Puerto Angamos for Novandino Litio.
Novandino says more than 95% of its international shipments leave through Puerto Angamos. It also reports terminal operability close to 99%. The logistics chain therefore shows how a mining producer can build a dedicated relationship around storage, consolidation, traceability and terminal reliability rather than simply choosing the nearest generic terminal. Econosur’s Novandino Litio company analysis provides the company context, while the broader Chile lithium analysis places the logistics model inside the national lithium framework.
Puerto Angamos is also looking east. At Argentina Mining Norte 2026 in Salta, the terminal promoted Mejillones as a Pacific logistics option for lithium and future copper projects in northwest Argentina. This does not mean those cargoes are secured. It does show that Chilean ports are already competing to shape the logistics route before some of the largest Argentine copper projects reach production.
The regional opportunity is therefore larger than one port.
Antofagasta city, La Negra, Portezuelo, FCAB, Mejillones and Puerto Angamos form overlapping logistics options. Cargo owners and suppliers will select among them according to commodity, handling requirements, contracts, route reliability, storage, rail or road access and shipping economics.
The Bioceanic Corridor adds optionality, not guaranteed volume
The Corredor Bioceánico de Capricornio expands the strategic geography from northern Chile toward northwest Argentina, Paraguay and Brazil. The Government of the Antofagasta Region lists rail development, port improvements, truck-rest areas, logistics zones and border-system work among the infrastructure actions required to make the corridor function at scale.
Some commercial flows are already occurring. The regional government reported imports from Argentina, Paraguay and Brazil during 2026, while mining logistics operators are actively courting Argentine mineral cargo. But the corridor still depends on border inspection, road capacity, digitalisation, truck facilities, commercial frequency and coordination between multiple public and private actors.
For mining, the more important long-term question is whether growing lithium and copper production in northwest Argentina develops repeatable Pacific export chains through Chile. Econosur has already examined the procurement side of Argentina’s lithium projects and the wider regional geography in its Bioceanic map analysis .
Supplier demand is emerging in different layers
“New supplier demand” is best understood as a set of separate procurement environments. A dredging contractor, a mining spare-parts distributor, a warehouse operator and an automation vendor may all benefit from the same regional expansion, but they enter through different buyers, qualification systems and project schedules.
The buyer structure also changes by layer. Port works may be tendered by the port company or its concession ecosystem. Mine packages can run through operators, EPC contractors, engineering firms and approved local distributors. Logistics services may be contracted by mining companies, terminal operators, freight companies or specialised project vehicles. A supplier strategy therefore has to identify the actual buying point rather than assuming that “the mining company” purchases every category directly.
Projects are not contracts
The strongest reason to avoid converting the regional investment pipeline into a simple supplier-market number comes from Cochilco itself. In the national 2025–2034 portfolio, 40% of investment is classified as potential, meaning it carries elevated technical, environmental or financial uncertainty. Another 6% is classified as probable and 13% as possible, while 41% falls into the base category.
The composition matters as much as the certainty. Cochilco shows 47% replacement projects and 34% expansion projects, meaning 81% of the portfolio is brownfield. New projects account for only 19%. Brownfield investment can be large, but it often favours suppliers that already understand site standards, safety systems, shutdown schedules, technical specifications and local service expectations.
Escondida’s new concentrator illustrates one form of conditionality. BHP has defined the project and submitted it for environmental review, and the company explicitly expects supplier-development effects. But first production is only expected in 2031–2032 if approval is obtained. That is commercially relevant for early positioning; it is not the same as an open purchase order.
The dredging process provides a different example at a much later commercial stage. The scope is defined and a public tender is active, yet the current process is already a second call after the previous procedure was declared unsuccessful. Even a visible procurement requirement therefore still has to pass bidder qualification, technical evaluation and award before it becomes contract revenue.
This analysis separates five statuses that are often mixed together in mining and infrastructure reporting:
announced investment → permitted project → financed / approved project → procurement package → awarded contract.
Supplier opportunity becomes more concrete as a project moves right across that sequence. Public information is strongest on project design and approvals; current supplier positioning, buyer requirements and package-level procurement often require direct commercial research.
The next useful signals are procurement signals
The regional investment story is already visible. What matters next is whether specific projects convert that investment logic into repeatable contracts, operating volumes and supplier access.
Antofagasta’s strongest logistics advantage is not one port project. It is the concentration of several demand systems in the same region.
The mining pipeline creates equipment and operating demand. La Negra creates space for suppliers to hold inventory, repair equipment, consolidate cargo and build local service capability. Portezuelo and FCAB connect that inland layer with rail. Puerto Antofagasta is expanding maritime capacity, while Mejillones and Puerto Angamos provide an alternative port and specialised mining-logistics platform. The Bioceanic Corridor adds the possibility of additional cargo from outside Chile.
That combination can strengthen Antofagasta as a supplier location, but it does not remove the barriers to entry. The high share of brownfield investment means many contracts sit inside established operating ecosystems. Foreign suppliers therefore need to understand who specifies the product, who qualifies vendors, whether a local distributor or service partner is required, how much stock must be held in the region and whether the buyer is the mine, an EPC, a contractor, a terminal or a logistics operator.
Mejillones is also important because it prevents an overly simple “Puerto Antofagasta wins” narrative. Novandino’s logistics model at Puerto Angamos shows that dedicated storage, traceability, terminal performance and customer-specific infrastructure can determine cargo routing. Novandino reports that more than 95% of its international shipments leave through Puerto Angamos and describes terminal operability as close to 99%.
For suppliers, the most useful entry point is usually below the headline investment number: a defined project, buyer, package, operating problem or logistics bottleneck that can be verified against current procurement and incumbent competition.
Commercial & Supplier Questions
The public project record establishes where capacity is being created. Commercial analysis has to establish who can sell into that capacity, through which procurement route and at what stage.
Where is supplier demand already visible?
The clearest immediate evidence is in Puerto Antofagasta’s live dredging process and in the La Negra tenant and service structure. The port has publicly identified heavy transport, mining-equipment spare parts, fabrication, logistics services and circular-economy projects among the activities already being committed in the SME segment. These are more concrete signals than the regional mining-investment total alone.
Where is the larger future demand?
Large mine expansions can create much bigger equipment and service packages, but timing differs. Nueva Centinela is already under construction and moving toward 2027 production. Escondida’s proposed new concentrator has a much later horizon and remains conditional on environmental approval. Supplier positioning has to match that project clock.
How important is local presence?
It depends on the category. For continuity-critical spares, field service, repair, fabrication and logistics, local response time can be part of the value proposition. Other equipment can be supplied internationally through EPCs, distributors or project-specific channels. La Negra increases the practical options for companies that need stock or service capacity close to mines and ports.
Does Argentine mining create a second market?
Potentially, but route economics must be verified mine by mine. Puerto Angamos is already marketing Mejillones to northwest Argentine mining, and FCAB frames Argentine copper and lithium growth as part of the future regional logistics challenge. Border capacity, road and rail connectivity, shipping schedules and customer contracts will determine whether that interest becomes recurring cargo.
Public sources can identify investment amounts, project status, port infrastructure, tenders and named logistics assets. They usually do not show the full approved-vendor list, current bidder field, buyer centre, technical disqualification criteria, local-partner expectations, incumbent supplier performance, target pricing or whether a specific package is still commercially open.
Antofagasta Mining, Logistics & Supplier Research Services
Marcus A. Volz provides custom and primary market research for international companies evaluating mining, logistics and industrial opportunities in Chile and the Southern Cone. The work starts with the documented project layer and then tests the commercial reality behind it.
Project and procurement tracking
Verify project status, approvals, construction stage, tender timing, procurement packages, EPC structures and the actors controlling execution.
Buyer and qualification mapping
Identify operators, contractors, technical influencers, purchasing roles, approved-vendor routes and local service or distributor requirements.
Competitor and supplier positioning
Map incumbent suppliers, local distributors, service capability, visible references and gaps where a new entrant may still have a realistic proposition.
Port and route comparison
Compare Puerto Antofagasta, Mejillones, rail and road options for a defined cargo, project or supply chain, including cross-border constraints where relevant.
Direct market verification
Where required, research can include company outreach, supplier and distributor checks, project-specific verification and structured interviews with relevant market participants.
Regional verification
For defined questions, research can include event observation, local supplier checks and practical verification in Argentina, Chile and the Southern Cone.
Where research identifies a concrete commercial fit, Econosur can also support B2B connections in South America . This is separate from the analytical work: a documented project is not presented as an introduction opportunity unless there is a relevant and verifiable fit.
Typical research questions:
- Which Antofagasta mining projects are closest to a procurement package relevant to our equipment category?
- Who specifies, qualifies and buys the product: operator, EPC, contractor, distributor or logistics company?
- Which competitors are already installed in Antofagasta, La Negra or Mejillones?
- Does our category require local stock, repair or field-service capacity?
- Which port and logistics chain is most realistic for a defined cargo or project?
- Are Argentine lithium or copper projects actually considering Chilean Pacific routes, and under what commercial conditions?
Investment figures, project status, port works, rail functions and corridor infrastructure are anchored first in government, public-company and operator-primary sources.
- KGHM, October 2, 2026 — Sierra Gorda expansion.
- BHP, August 18, 2026 — revised Escondida concentrator scope and investment.
- Cochilco — Mining Investment Portfolio 2025–2034 : national investment portfolio of US$104.549 billion and project framework.
- Cochilco — 2025–2034 investment portfolio presentation : approximately US$40.7bn for Antofagasta; 41% base, 6% probable, 13% possible and 40% potential investment nationally; 47% replacement, 34% expansion and 19% new projects.
- BHP, March 17, 2026 — Escondida New Concentrator : original US$4.4–5.9bn investment range and 220–260 ktpa copper capacity, subsequently revised in BHP’s August 18 results; supplier-development statement, construction workforce and possible 2031–2032 first production subject to approval.
- Antofagasta Minerals, July 7, 2026 — Minera Centinela expansion : US$4.4bn second concentrator and planned 2027 start-up.
- Puerto Antofagasta, September 25, 2026 — regional logistics investment : second dredging call, La Negra industrial land, named supplier activities, 75% SME-segment occupancy and Portezuelo’s role in rail-linked mineral flows.
- Puerto Antofagasta, September 21, 2026 — dredging tender technical scope : second call after the previous procedure was declared unsuccessful; 46,678 m³ total reference volume, 365-day reference period and tender timetable.
- Puerto Antofagasta, July 26, 2026 — La Negra and Portezuelo : 50-hectare platform, 30 hectares urbanised, 36 SME spaces, six industrial sites and more than 22,000 m² of Portezuelo warehouse space.
- Puerto Antofagasta, September 10, 2026 — supplier and contracting presentation : procurement procedures, technical and economic evaluation criteria, infrastructure projects and integration of regional suppliers into the logistics chain.
- FCAB, January 16, 2026 — strategic logistics development : mining growth in Chile and Argentina, the Bioceanic Corridor and the need to coordinate rail, ports and potential customers.
- FCAB — operations and customers : freight, storage, transfer and port services plus regional rail-network connections and major mining customers.
- Government of the Antofagasta Region, April 14, 2026 — Bioceanic Corridor : logistics, rail, port, truck-rest-area, border and infrastructure measures required for corridor development.
- Novandino Litio — logistics and traceability : more than 95% of international shipments through Puerto Angamos in Mejillones and terminal operability close to 99%.
- Novandino Litio — lithium carbonate logistics : additional primary-source confirmation of more than 95% dispatch through Puerto Angamos and 99% terminal operability.
- Asociación de Industriales de Antofagasta, September 10, 2026 : regional supplier perspective on projects presented by Escondida | BHP, Puerto Antofagasta and SQM to more than 400 AIA member companies.
- Reporte Minero, September 7, 2026 — Puerto Angamos at Argentina Mining Norte : Mejillones positioning for lithium and future copper cargo from northwest Argentina.
- PortalPortuario, May 8, 2026 — Puerto Angamos / Novandino lithium hub : eight warehouses and yard space totalling about 21,000 m² for receipt, storage, consolidation and dispatch of lithium.
- Reporte Minero, June 23, 2026 — Puerto Antofagasta master-plan interview : additional context on the 16-initiative expansion programme, Portezuelo, La Negra, the 3.5-to-7-million-tonne capacity target and the logistics requirements of regional mining.
- Evidence note: supplier opportunity is treated as documented only where a tender, active project, operating logistics requirement or named supplier activity can be identified. Broader mine and corridor investments are presented as future or conditional demand according to their current status.
Need to verify the market behind an Antofagasta project?
Public documents show investment amounts, project approvals, port infrastructure, logistics sites and named tenders. Custom and primary research can investigate what they do not: current procurement status, buyer requirements, approved-vendor routes, supplier positioning, local-service expectations and whether a commercially realistic entry point remains open.
Marcus A. Volz conducts project, company, competitor, buyer and procurement research for international companies evaluating Chile, Argentina and Southern Cone industrial markets.
Discuss a research questionFrequently asked questions
What is driving Antofagasta’s logistics expansion?
The immediate drivers are a large regional mining investment pipeline, active mine expansions, the need for more port capacity and resilience, new inland logistics space at La Negra, rail-linked mineral flows and the longer-term option of additional cargo from the Bioceanic Corridor.
How large is Antofagasta’s mining investment pipeline?
Cochilco’s 2025–2034 portfolio places the Antofagasta Region at approximately US$40.7 billion of mining investment. Its regional chart shows US$40.209 billion for copper plus US$525 million for other minerals, while the accompanying text gives a total of US$40.734 billion.
Is the full US$40.7 billion already committed?
No. Cochilco classifies 41% of Chile’s national mining-investment portfolio as base, 6% as probable, 13% as possible and 40% as potential. It also shows that 47% is replacement investment and 34% expansion investment, while new projects account for 19%. A project pipeline therefore cannot be treated as a list of open supplier contracts.
What is Puerto Antofagasta’s capacity target?
Puerto Antofagasta says its strategic projects are intended to lift transfer capacity from about 3.5 million tonnes per year to a potential 7 million tonnes per year.
What is the La Negra logistics zone?
La Negra is Puerto Antofagasta’s inland logistics and industrial platform beside Route 5. It covers 50 hectares, with about 30 hectares urbanised. Puerto Antofagasta says the platform includes 36 spaces for small and medium-sized companies plus six larger industrial sites.
What role does Antepuerto Portezuelo play?
Portezuelo is an inland support facility that receives, stores and manages mineral concentrates, including Bolivian cargo moved mainly by rail, before dispatch to Puerto Antofagasta. It provides an operating base for rail-port coordination and future additional cargo flows.
Why is rail important in the Antofagasta logistics system?
FCAB combines rail transport with storage, transfer and port services and connects the Antofagasta and Mejillones port system with mining operations and neighbouring countries through linked networks. Mining growth in Chile and Argentina increases the importance of coordinated rail, port and customer infrastructure.
Is Mejillones a competitor to Puerto Antofagasta?
It is both a competing and complementary logistics node. More than 95% of Novandino Litio’s international shipments leave through Puerto Angamos in Mejillones, and Novandino reports terminal operability close to 99%. For suppliers and cargo owners, the relevant question is which terminal and logistics chain fit a specific cargo, contract and destination.
Which supplier categories have visible demand signals now?
Current public evidence points to marine engineering and dredging, port construction, environmental and bathymetric monitoring, heavy transport, mining-equipment spares, metal structures, warehousing, cargo handling, logistics services and circular-economy activities. Mine projects create additional future demand, but package timing and qualification requirements must be verified project by project.
How could Argentine mining affect Antofagasta logistics?
Ports and logistics companies in the Antofagasta Region are actively positioning for lithium and future copper cargo from northwest Argentina. The commercial scale still depends on border procedures, road and rail performance, shipping economics and the preferences of individual mining projects.
What should suppliers watch next?
The most useful signals are awarded port tenders, new La Negra leases, mine-project approvals and construction packages, FCAB or other logistics contracts, recurring Argentine cargo flows, border-control improvements and named procurement packages rather than broad investment announcements.