Chile · Mining Investment · Copper · Lithium · Infrastructure
Chile’s Mining Investment Pipeline: Where Copper and Lithium Capital Is Going
Chile’s US$104.5 billion mining portfolio combines major copper reinvestment with a developing lithium industry. Most of the capital is committed or proposed around existing operations: replacing ageing capacity, sustaining output and securing water, electricity and transport. Updated project disclosures show why investment size, construction readiness and accessible supplier contracts need to be examined separately.
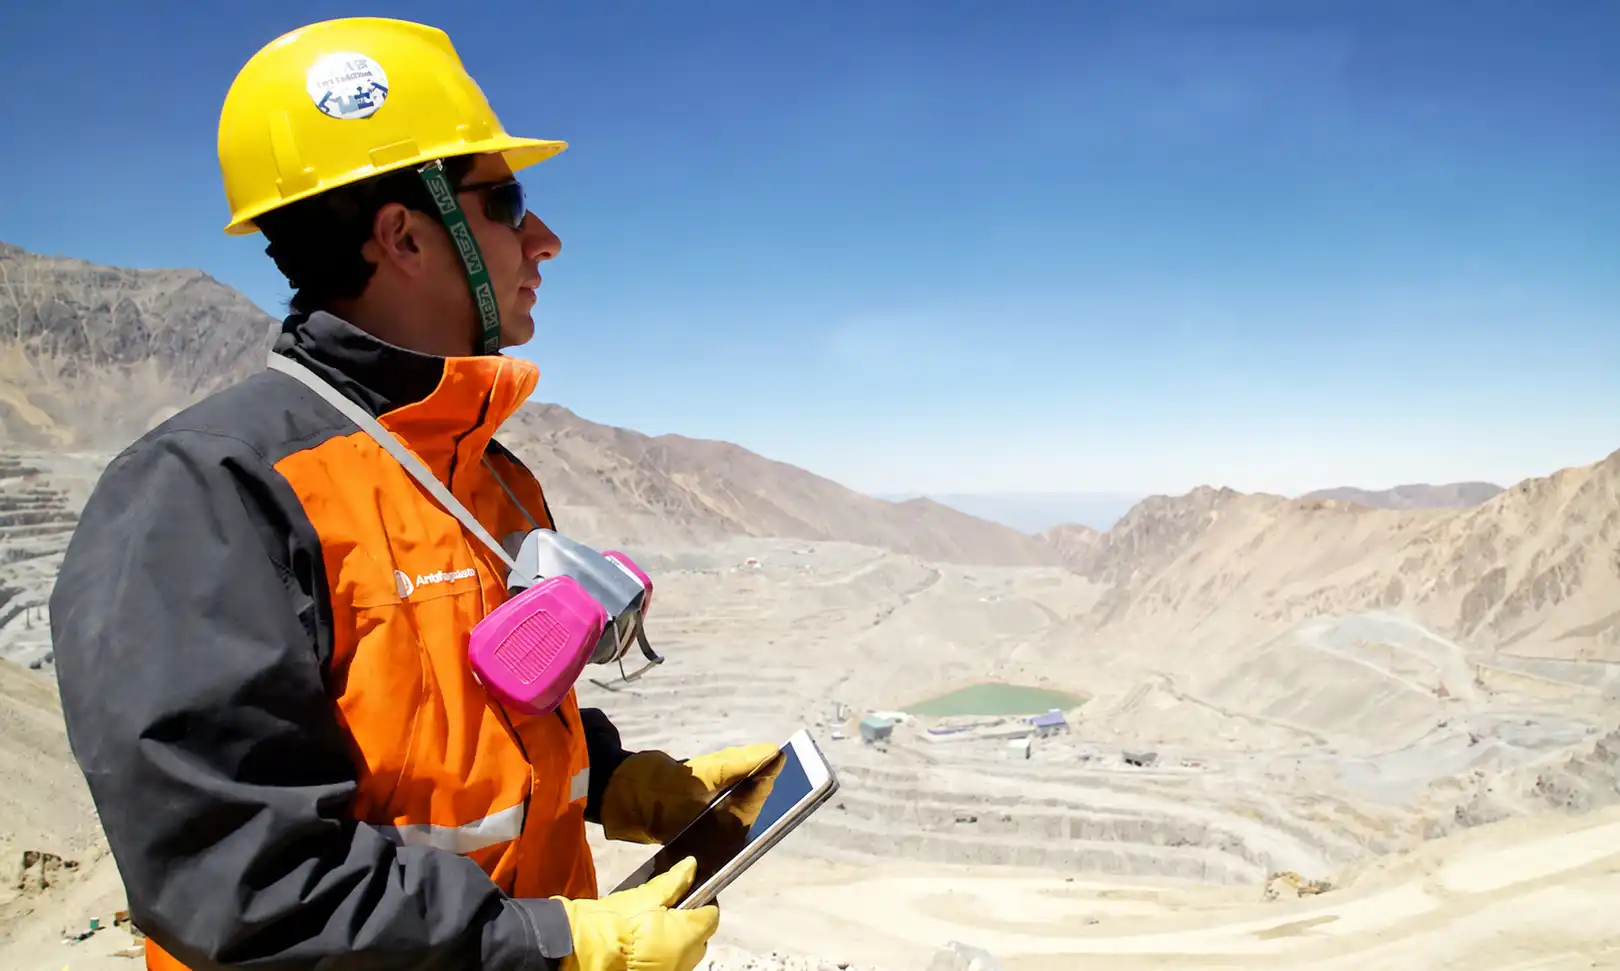
Chile’s US$104.549 billion mining investment portfolio combines production continuity, selective expansion and new lithium development.
Cochilco, Chile’s national copper commission, classifies 81% of its 2025–2034 portfolio as brownfield: replacement, continuity and expansion at existing operations. Copper represents 89.8% of the portfolio. These published figures describe a multi-year inventory of projects with different levels of maturity, rather than an amount already approved for construction.
The latest operator disclosures sharpen that distinction. BHP increased Escondida New Concentrator’s investment estimate to US$5.4–6.3 billion in August 2026. Codelco reported 564,000 tonnes of own copper production in the first half of 2026, down 11% year on year. Collahuasi’s desalination authorization remained an execution issue in Anglo American’s July reporting.
Infrastructure demand also extends outside mine boundaries. In northern Chile, Antofagasta’s port and industrial logistics development adds maritime works, storage, transport and supplier facilities to the commercial picture.
For suppliers, the central question is which investment programmes become accessible procurement packages, who controls those packages and when qualification or tendering begins.
The US$104.5 billion headline hides a reinvestment cycle
Cochilco’s 2025–2034 mining investment portfolio totals US$104.549 billion, an increase of US$21.369 billion over the previous portfolio. Copper represents 89.8% of the total. The more revealing distinction is project type: 81% is brownfield, while 19% is greenfield development at new operations.
Brownfield includes more than maintenance. It covers replacement, continuity and expansion of existing productive capacity. A large share of Chile’s investment is therefore directed into an established mining system: extending mine lives, replacing ageing plants, moving underground, processing more difficult ore and securing the infrastructure needed to sustain production.
Cochilco classifies 41% of the portfolio as base projects and 40% as potential projects. These are maturity categories within the published inventory. A substantial share of the later investment horizon remains dependent on engineering, environmental approvals, infrastructure, financing and investment decisions.
Antofagasta Region, in northern Chile, accounts for US$40.734 billion of the portfolio. This concentration helps explain why mining investment there has wider implications for industrial facilities, transport and coastal infrastructure.
Data basis: the national portfolio figures refer to Cochilco’s 2025–2034 inventory. Subsequent company updates below describe individual project changes and are not added to that total. Adding a revised project estimate or a separate port programme would risk mixing reporting periods, scopes or overlapping investment figures.
The investment paradox: more capital can be required to preserve productive capacity as ore grades decline, pits deepen, underground development becomes more complex and water and electricity requirements rise.
Where the capital is going
Representative projects show different uses of mining capital: copper replacement and recovery, water and power infrastructure, lithium development and industrial logistics. The dates and conditions attached to each disclosure matter as much as its investment value.
| Capital theme | Representative project / actor | Dated project signal | Commercial implication |
|---|---|---|---|
| Replace and improve copper processing | BHP · Escondida New Concentrator | August 2026: US$5.4–6.3bn estimate; 230,000–270,000 tonnes of copper per year; expected final investment decision in 2027–2028 | Replacement of Los Colorados with a revised, larger processing scope; preparation funding precedes full project approval. |
| Recover state copper production | Codelco | August reporting: H1 2026 own production of 564,000 tonnes, down 11%; US$2.422bn of 2025 profit retained for continuity and projects | Capital must translate into operational recovery while safety, maintenance and geological constraints affect execution. |
| Secure water for existing copper operations | Collahuasi, Tarapacá Region | July 2026 reporting: desalination authorization set aside following the May tribunal ruling; alternative water supplies used | Physical investment progress and permission to operate must be assessed separately. |
| Develop public-private lithium projects | ENAMI–Rio Tinto · Salares Altoandinos | US$3.2bn estimate in Cochilco’s published investment portfolio | New lithium development creates processing and infrastructure demand, subject to project-specific approval and execution. |
| Develop lithium extraction and processing | Codelco–Rio Tinto · Salar de Maricunga, Atacama Region | Agreement provides up to US$900m of milestone funding; Codelco announced the definitive lithium operating contract in February 2026 | Technology, reinjection and supporting infrastructure require separate verification; milestone funding is not total construction capex. |
| Transform operating lithium systems | Novandino Litio / Albemarle | Long-term Salar de Atacama joint venture; Albemarle’s proposed US$3.1bn direct lithium extraction transition submitted for environmental review in 2026 | Technology conversion, brine management, electricity and environmental performance shape future packages. |
| Support mining transport and industrial services | Puerto Antofagasta / La Negra logistics zone | September 2026: dredging tender under way; technical bids scheduled for October 20 and financial bids for October 27 | Port procurement and industrial land development create routes to work outside mine-owner purchasing structures. |
Copper: replacement projects can also improve future output
Short-term production forecast: Cochilco’s August 11, 2026 update estimates Chilean mined copper output at 5.27 million tonnes in 2026, down 2.6%, and 5.55 million tonnes in 2027. This dated forecast is separate from the longer-term outlook below.
Cochilco’s 2025–2034 production outlook illustrates why the investment portfolio cannot be read as a continuous production boom. It projects a short-term national copper-output peak around 2027, followed by adjustment as deposits deplete and individual mine plans change. Projects in execution and the wider portfolio would support a gradual recovery later in the period.
BHP’s Escondida New Concentrator, at the Escondida mine in Antofagasta Region, shows how replacement and growth objectives can overlap. The project will replace the historic Los Colorados plant. In its August 2026 results, BHP raised the investment estimate from US$4.4–5.9 billion to US$5.4–6.3 billion and the expected copper output range from 220,000–260,000 to 230,000–270,000 tonnes per year.
The revised design has a processing capacity of 50 million tonnes of ore per year, compared with 45 million previously. BHP continues to indicate a final investment decision in 2027–2028 and potential first production in 2031–2032.
BHP also announced approximately US$500 million of pre-commitment funding. This is an important preparation signal, but it does not establish that the whole construction programme has received its final investment approval.
For suppliers, replacement demand can be commercially substantial even where national output does not grow proportionally. Processing upgrades, underground development, tailings management, automation and reliability systems address an existing production base. Access depends on package timing, established suppliers and the owner’s contracting structure.
A replacement plant can protect existing production and improve future performance. Its full output should not be counted as an equivalent increase in national copper supply.
Sierra Gorda: expansion within an established operation
KGHM’s October 2, 2026 announcement puts Sierra Gorda’s fourth grinding line at US$725 million. Planned ore capacity rises from about 48 to 60 million tonnes annually, with full capacity targeted for the second half of 2030. These are project targets. Read Sierra Gorda’s expansion economics.
For supplier research, the existing operation makes shutdown coordination, installed equipment and contractor responsibilities relevant. The investment announcement alone does not identify unawarded packages.
Codelco: financing and project progress must deliver production recovery
Codelco, Chile’s state-owned copper producer, reported 564,000 tonnes of own copper production in the first half of 2026, 11% below the corresponding 2025 period. Its August 28 disclosure attributed the decline mainly to operational restrictions at El Teniente, major maintenance at Chuquicamata and lower ore grades at Ministro Hales.
Project progress remained uneven. The same disclosure reported 94% progress on the first phase of Level 1 continuity infrastructure at Chuquicamata Underground and 97% total progress at Rajo Inca in Salvador. Rajo Inca was in ramp-up, with design capacity expected during 2027.
The financing response is significant. On August 10, Chile authorized Codelco to retain 100% of its 2025 profits, US$2.422 billion, to support operational continuity and its project portfolio while reducing the need for additional debt.
Production-reporting controls are a separate issue. Codelco initially reported own copper production of 1.334 million tonnes for 2025. An internal audit subsequently identified 26,875 tonnes classified as finished production although the material required further processing. Codelco said the finding did not require a change to its audited 2025 financial statements. In July, its board commissioned KPMG to review production reporting for 2024 and 2025.
Andes Norte, an underground development project at El Teniente in central Chile’s O’Higgins Region, was temporarily suspended on August 4 because of newly identified deep-seismicity risks. In its September 3 update, Codelco announced reassignment options for affected workers and reiterated that the suspension covered Andes Norte development and construction, rather than the rest of El Teniente’s operations.
Codelco demonstrates the difference between funding, physical progress and productive output. Profit retention supports investment, but recovery also depends on commissioning, geological conditions, maintenance, safety and project sequencing. Suppliers need to establish which activities continue, which have been rescheduled and where purchasing responsibilities have moved.
Collahuasi: water infrastructure remains exposed to permitting risk
Collahuasi, a major copper operation in northern Chile’s Tarapacá Region, illustrates a different execution problem. On May 15, 2026, Chile’s Second Environmental Tribunal set aside the 2021 environmental authorization for the Infrastructure Development and Production Capacity Improvement project. Anglo American’s May disclosure described its desalination plant as almost complete.
The issue remained relevant in Anglo American’s July 30 half-year results. The company said the desalination plant’s environmental authorization had been set aside, that the mine would continue using alternative water supplies and that work with authorities and stakeholders was continuing to restart the plant.
For investment screening, the distinction is material: construction progress does not establish permission to operate. A supplier assessing water-system, commissioning or associated expansion packages needs to check the current authorization, revised execution plan and responsible contracting entity.
The broader commercial implication is that committed capital can remain exposed to environmental and legal conditions after substantial physical work has taken place. Project status should combine physical progress, operating permissions and the operator’s latest dated disclosure.
Water and electricity requirements extend the investment chain
Cochilco projects copper-mining electricity consumption rising from 27.6 terawatt-hours in 2025 to 33.2 terawatt-hours in 2034, an increase of 20.2%. Projected copper production rises by 8.3% over the same period. Ore concentration alone is expected to consume 18.1 terawatt-hours in 2034, with seawater use and pumping adding further demand.
Water supply changes even more substantially. Total copper-mining water demand is projected to rise from 18.5 cubic metres per second in 2024 to 20.6 in 2034. Seawater’s share is expected to increase from 40.7% to 67.6%. This measure includes seawater supply across the sector and should not be interpreted as desalinated water alone.
The investment chain therefore extends from mine-site equipment to coastal intakes, desalination, pumping stations, pipelines, substations, transmission capacity and control systems. These assets can be procured by mining companies, specialist infrastructure operators or separate project companies.
Econosur examines this layer in Chile’s seawater-mining infrastructure, the power-grid build-out, the Kimal–Lo Aguirre transmission project and battery storage and grid bottlenecks. These systems affect whether mining capacity can operate reliably and economically.
Antofagasta: mining investment creates demand beyond the mine
Antofagasta is both a city and a region in northern Chile. The region’s mining investment concentration creates demand for industrial supplies, equipment movements, storage and exports. The Port of Antofagasta and nearby industrial facilities form part of this supporting system, alongside other regional ports.
In September 2026, Puerto Antofagasta presented the second call for its dredging tender, covering a reference volume of 46,678 cubic metres of sand, sediment and rock. Its published timetable schedules technical bid opening for October 20 and financial bid opening for October 27, 2026. This is a tender-stage project, rather than evidence that dredging has already started.
The port’s La Negra logistics zone, beside Route 5, comprises 50 hectares, approximately 30 of them serviced. It offers space for storage, cargo handling and industrial support. The port’s September disclosure identifies activities such as heavy transport, mining spare parts, fabrication and logistics among projects in its small-business area.
Regional logistics demand must nevertheless be traced to actual shipping routes. Novandino Litio states that more than 95% of its international shipments leave through Puerto Angamos in Mejillones Bay, north of Antofagasta city. This company-specific route does not establish Novandino as a customer of Puerto Antofagasta’s dredging project.
The commercial implication is that equipment suppliers, transport companies and industrial service providers may encounter purchasing opportunities through port operators, logistics tenants and mine-service businesses, in addition to mine owners. The buyer, tender route and qualification requirements need to be identified for each package.
Antofagasta’s Logistics Expansion: Mining, Port Infrastructure and New Supplier Demand
Read the detailed analysis of maritime works, industrial logistics space and the different commercial routes serving northern Chile’s mining economy.
Lithium creates a distinct investment and technology cycle
Chile’s lithium pipeline is smaller than copper in aggregate capital, but individual developments create a substantial industrial market. Cochilco includes Salares Altoandinos, the ENAMI–Rio Tinto initiative, at an estimated US$3.2 billion. ENAMI is Chile’s state-owned mining company focused on supporting the mining sector; this project forms part of the country’s public-private lithium development model.
At the Salar de Maricunga in Atacama Region, Rio Tinto’s agreement with Codelco provides for a 49.99% interest and up to US$900 million of milestone funding: US$350 million toward studies and development, US$500 million following a decision to proceed and US$50 million if first lithium is achieved by the end of 2030. These commitments are not a published total construction budget.
Codelco announced the definitive Special Lithium Operating Contract, known in Chile as a CEOL, for Maricunga on February 12, 2026. Rio Tinto’s project page describes joint development using extraction, processing and reinjection technologies, with supporting power and road infrastructure. Regulatory permissions and final execution remain separate project conditions.
In the Salar de Atacama in Antofagasta Region, Novandino Litio brought together Codelco and SQM in late 2025, with an operating horizon extending to 2060. This is an existing lithium production system with new governance and long-term development requirements.
Separately, Albemarle submitted a proposed US$3.1 billion transition to direct lithium extraction for environmental assessment in 2026. Direct lithium extraction, or DLE, separates lithium from brine through a selected process technology. Albemarle describes a modular development of up to six production lines, with phased execution dependent on permits and a final investment decision.
These projects show why lithium research needs to cover the selected technology, brine management, reinjection, electricity, water balance and operating agreements. DLE is not one standardized equipment package. Different process routes create different needs for technology providers, engineering firms, chemicals, utilities and monitoring systems.
What the investment cycle means for international suppliers
A US$104.5 billion investment portfolio does not establish an equally large accessible supplier market. The relevant opportunity depends on project stage, contract structure, incumbent vendors, local sourcing, purchasing authority and package timing.
A final investment decision, or FID, is the formal decision to proceed with a project. Engineering, procurement and construction contractors, commonly called EPC contractors, may control design and purchasing packages. Under an engineering, procurement and construction management arrangement, or EPCM, purchasing responsibilities may be divided differently between the contractor and owner.
| Investment type | Typical supplier opportunity | What needs verification |
|---|---|---|
| Brownfield continuity / replacement | Replacement equipment, automation, maintenance, process optimization, underground systems, safety and reliability | Installed vendor base, framework agreements, shutdown windows, qualification rules and whether new suppliers can compete |
| Major concentrator / expansion | Engineering, crushing and grinding, flotation, pumps, materials handling, electrical systems, construction and long-lead equipment | Environmental status, final investment decision, contractor appointment, package release dates and approved vendor lists |
| Water & power infrastructure | Coastal intakes, desalination, pumping, pipelines, substations, transmission, storage, controls and operating services | Asset ownership, infrastructure business model, utility interface, procurement authority and shared versus dedicated assets |
| Lithium / direct lithium extraction | Process technology, pilot and commercial modules, sorbents or membranes where applicable, reinjection, chemicals, utilities and monitoring | Selected process route, technology licensor, intellectual property, scale-up evidence, permit conditions and engineering responsibility |
| Port & industrial logistics | Marine engineering, dredging support, surveys, cargo handling, storage, transport, industrial premises and equipment services | Tender eligibility, official bid timetable, port coordination requirements, logistics tenant, shipping route and package owner |
Companies need to identify where qualification or procurement is still open. Mature operations can have entrenched vendor relationships and framework agreements. New lithium process routes may offer earlier opportunities for specialist technologies, while infrastructure and logistics can involve buyers outside the mine owner’s procurement department.
An announced investment, approved preparation budget or visible construction site is useful evidence of activity. None of these alone establishes an unawarded contract or a realistic entry point for a new supplier.
Three business questions that require deeper research
Public investment portfolios show scale and direction. Commercial decisions require a more detailed view of project readiness, supplier access and the organizations responsible for purchasing.
Which copper, lithium and supporting infrastructure projects are likely to produce relevant tenders or purchasing packages over the next 24–36 months?
Answering this requires tracking environmental decisions, final investment approvals, engineering progress, contractor appointments, long-lead orders and construction sequencing. Published tender dates should be checked against official clarifications before a supplier commits resources.
Which equipment and service packages are open to new or international suppliers, and which are already covered by incumbents, framework agreements or existing contracts?
This requires mapping the installed supplier base, approved vendor lists, maintenance and shutdown arrangements, local fabrication capacity and the purchasing role of engineering and construction contractors.
Does the relevant buyer sit inside the mining company, or in the water, power, processing, transport or port system serving the operation?
The answer depends on asset ownership, contract boundaries, logistics routes and the roles of project companies, infrastructure operators and industrial tenants. Geographic proximity alone does not establish a customer relationship.
Public sources show the investment pipeline, but only part of the commercial pipeline.
They rarely reveal complete tender calendars, incumbent relationships, package ownership, qualification barriers or the likelihood that an early-stage project will reach procurement on its proposed timetable. These gaps determine whether a broad sector opportunity becomes a practical business target.
Research services for Chile’s mining investment pipeline
Econosur can structure custom research around a copper or lithium project, supplier category, infrastructure asset or procurement question. Typical assignments include:
Content updated October 8, 2026. The national investment baseline is Cochilco’s 2025–2034 portfolio. Individual project updates use the dated operator and institutional disclosures listed below. Investment estimates, tender schedules, production targets and project milestones remain subject to revision.
Government, regulator, company and infrastructure-operator disclosures supporting the factual figures and dated project developments.
- KGHM, October 2, 2026 — Sierra Gorda expansion.
- Cochilco, August 11, 2026 — 2026–2027 copper-production forecast.
- Cochilco — Mining Investment Project Portfolio 2025–2034: US$104.549bn national portfolio.
- Cochilco portfolio report — copper and brownfield shares, maturity categories, regional investment and Salares Altoandinos.
- Cochilco — Copper Production Outlook 2025–2034: projected short-term peak and subsequent adjustment.
- Cochilco — Electricity Consumption Outlook 2025–2034: electricity demand, concentration and seawater-related loads.
- Cochilco — Water Demand Outlook 2025–2034: total demand and changing supply sources.
- Cochilco, March 18, 2026 — seawater projected to account for 67.6% of copper-mining water use by 2034.
- BHP, March 17, 2026 — Escondida New Concentrator environmental submission and original project scope; investment figures subsequently revised.
- BHP, August 18, 2026 — full-year results and Escondida pre-commitment funding.
- BHP FY2026 exchange release — revised Escondida concentrator estimate, processing scope, copper output and indicative investment-decision timetable.
- Codelco, March 27, 2026 — initially reported 2025 production and financial results.
- Codelco, May 20, 2026 — internal audit findings concerning 2025 production classification.
- Codelco, July 21, 2026 — independent external review of 2024 and 2025 production reporting.
- Codelco, August 10, 2026 — retention of 100% of 2025 profits for operational continuity and projects.
- Codelco, August 28, 2026 — first-half production and structural project progress.
- Codelco, August 4, 2026 — preventive suspension of Andes Norte development and construction.
- Codelco, September 3, 2026 — Andes Norte worker reassignment plan and clarification of the suspension’s scope.
- Anglo American, May 18, 2026 — Collahuasi environmental authorization ruling.
- Anglo American, July 30, 2026 — half-year results, including the Collahuasi desalination update in the accompanying financial report.
- Rio Tinto, May 19, 2025 — Maricunga partnership agreement and milestone funding structure.
- Rio Tinto — Salar de Maricunga project page: joint development, technology and supporting infrastructure.
- Codelco, February 12, 2026 — definitive Special Lithium Operating Contract for Maricunga.
- Chile’s Environmental Assessment Service, March 30, 2026 — Albemarle’s US$3.1bn DLE transition proposal and regional assessment context.
- Albemarle, March 25, 2026 — environmental review, modular development and conditions for phased DLE investment.
- Codelco, December 27, 2025 — formation of the Codelco–SQM lithium joint venture.
- Novandino Litio — logistics and traceability: international shipments through Puerto Angamos in Mejillones.
- Puerto Antofagasta, September 21, 2026 — second-call dredging tender, reference volume and October bid-opening dates.
- Puerto Antofagasta, September 25, 2026 — La Negra industrial logistics land and mining-related service activities.
Broader investment and regulatory context, rather than sole support for individual project-status claims.
FAQ
How large is Chile’s mining investment pipeline?
Cochilco’s 2025–2034 portfolio totals US$104.549 billion. Copper accounts for 89.8% and brownfield projects for 81%. The portfolio is a published investment inventory, not a guarantee that every project will proceed.
Why is Chile’s mining investment pipeline mostly brownfield?
Brownfield projects replace, sustain or expand existing operations. Chile’s mature copper assets require investment in processing capacity, underground development, reliability, water and power as ore grades decline and operating requirements become more demanding.
What is the updated investment estimate for Escondida’s new concentrator?
BHP’s August 2026 results give an estimated investment of US$5.4–6.3 billion and expected copper production of 230,000–270,000 tonnes per year. A final investment decision is expected in 2027–2028, with potential first production in 2031–2032. Pre-commitment funding does not constitute final approval of the full project.
Does US$104.5 billion of investment mean Chilean copper output will rise continuously?
No. Cochilco’s 2025–2034 outlook projects a short-term production peak around 2027, followed by adjustment as deposits deplete and mine plans change. Investment supports existing capacity as well as selected growth projects.
Where does lithium fit into Chile’s investment cycle?
Lithium creates a smaller but distinct investment axis through Salares Altoandinos, Codelco–Rio Tinto at Maricunga, Novandino Litio in the Salar de Atacama and Albemarle’s proposed direct lithium extraction project. Technology selection, permits, operating agreements and infrastructure determine procurement opportunities.
Why does Antofagasta logistics matter for mining suppliers?
Antofagasta Region combines a major mining investment concentration with demand for transport, storage, industrial services and port infrastructure. Puerto Antofagasta is tendering dredging works, while La Negra offers industrial logistics space. Actual shipping routes must be verified separately: Novandino Litio reports that more than 95% of its international shipments leave through Puerto Angamos in Mejillones.
What should international suppliers verify before pursuing Chilean mining projects?
Suppliers should verify project stage, environmental permits, final investment decisions, engineering and construction responsibilities, package ownership, incumbent vendors, local sourcing requirements and tender timing. Water, power and logistics procurement may be controlled by separate infrastructure operators.